


Best restoration and disaster-recovery franchises to buy in 2027
Quality
Certified
The strongest restoration and disaster-recovery franchises to buy in 2027 split into two groups: residential-volume brands (SERVPRO, PuroClean, Rainbow Restoration, 911 Restoration) built on frequent, insurance-paid water, fire, and mold jobs, and commercial/large-loss brands (Paul Davis, BluSky) built on slower-closing property-manager and institutional accounts. Total investment runs $80,000 to $700,000+; match the brand to your capital, sales background, and tolerance for 24/7 emergency response.
The two (or more) options compared
Every restoration franchise decision in 2027 collapses into a choice between two operating models, with a third hybrid sitting between them. Which bucket a brand falls into matters more than the brand name, because the bucket determines your daily rhythm, your cash-flow pattern, and the skills you need on day one — long before you ever think about logo recognition or national ad spend.
The residential-volume model — SERVPRO, PuroClean, Rainbow Restoration, and 911 Restoration — runs on a high number of smaller disaster jobs: a burst pipe in a kitchen, smoke damage confined to one bedroom, a mold patch behind a bathroom wall. These jobs close fast, typically two to five days from first call to final invoice, with average tickets between $3,000 and $15,000. The model depends on volume and referral density — plumbers, real estate agents, property managers, and insurance adjusters all need to call you first, every time. Marketing spend is continuous and hyper-local: door-to-door relationship building with trades, sponsorship of local adjuster associations, and co-op ad funds the franchisor typically administers on your behalf. The upside is faster cash cycling and a shorter learning curve for a first-time owner; the downside is that revenue is a sum of many small, somewhat unpredictable events, so staffing and scheduling must flex week to week, sometimes day to day, as storm activity and seasonal pipe-freeze cycles push volume up and down.
The commercial/large-loss model — Paul Davis at the upper end of its territory offerings, and BluSky as a commercial-only specialist — targets hotel chains, retail landlords, multifamily portfolios, and industrial facilities. A single commercial claim can run $50,000 to $500,000 or more, and the engagement stretches from weeks into months rather than days. But landing that first national or regional account takes six to eighteen months of relationship-building, RFP responses, and proof-of-capacity demonstrations; property managers do not hand a six-figure recovery job to an unproven local operator. This model rewards owners who already carry construction, project management, or B2B sales backgrounds, because the day-to-day skill set resembles running a general contracting operation far more than it resembles dispatching a cleanup crew to a residential emergency.
The hybrid model, which PuroClean explicitly structures into separate training tracks, lets a franchisee start residential for cash flow and layer in commercial capability once the business has working capital and a trained crew behind it. This is often the pragmatic answer for a 2027 buyer who wants commercial economics eventually but cannot absorb eighteen months of near-zero revenue while chasing a first national account. Rainbow Restoration, through its Neighborly network ties, offers a lighter version of the same idea: cross-referrals from sibling Neighborly brands — plumbing, electrical, lawn care — feed residential volume while the franchisee builds toward larger commercial jobs independently and at their own pace.
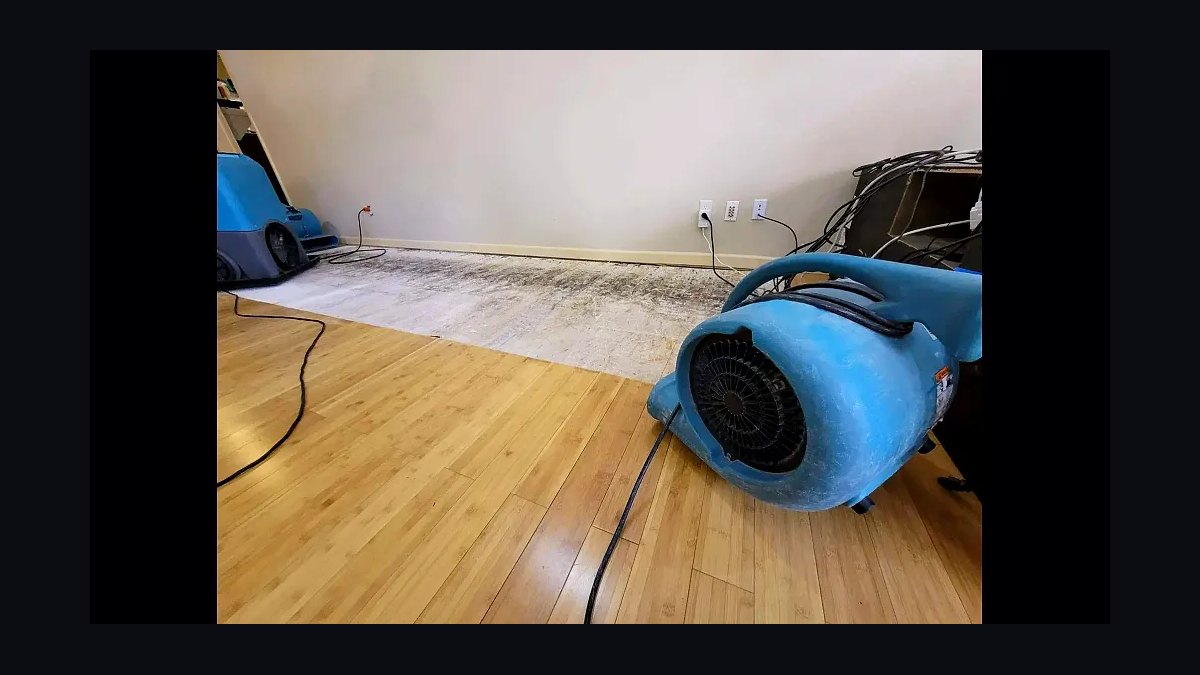
A related, adjacent angle worth weighing alongside the model choice: several residential brands are increasingly bundling light reconstruction (drywall, flooring, trim) into the same visit as the initial mitigation work, which raises average ticket size without requiring the franchisee to chase a separate general-contracting license in every state. This "mitigate-then-rebuild" bundling is becoming a meaningful differentiator between otherwise similar residential brands, since it captures a second, larger invoice from a customer you've already won — the insurance carrier is already engaged, the adjuster relationship is already warm, and the crew is already on site.
The practical comparison a buyer should run is not "which brand is biggest" but "which cash-flow pattern and sales motion matches what I can fund and what I'm good at." A $150,000-capital buyer with no B2B sales background chasing a commercial-only model like BluSky is mismatched; so is a well-capitalized former construction-company owner settling for a pure residential volume play when their existing network already includes property management executives who control large portfolios.
How to decide between them
The decision tree above is really a two-variable test: capital and sales background. Capital determines which door is even open to you, since franchisors set minimum net-worth and liquidity thresholds alongside the headline Item 7 range — a $700,000-ceiling Paul Davis territory will ask for substantially more liquid capital and net worth than its range implies on paper, because the franchisor wants proof you can survive a slow insurance-payment stretch without missing payroll. Sales background determines whether the eighteen-month commercial sales cycle is a viable bet or a cash-flow trap that quietly drains your reserves before the first big check arrives.
A second filter that belongs in this decision, even though it isn't capital-related, is your tolerance for being on call indefinitely. Every brand in this category requires true 24/7 emergency response — a sewage backup at 2 a.m. does not wait for business hours — but commercial brands can sometimes schedule larger jobs with more lead time once the relationship is established, while residential brands face genuine round-the-clock unpredictability for the life of the business. If being woken at odd hours indefinitely is a dealbreaker, that alone should push you toward a multi-unit residential model where you can eventually hire a night-dispatch manager, rather than staying the on-call owner-operator permanently.
A third, often-overlooked filter is geography and climate exposure. Markets with frequent freeze-thaw cycles, coastal storm exposure, or seasonal flooding generate more consistent residential disaster volume than arid, temperate markets — which is part of why territory selection inside a brand can matter as much as the brand choice itself. A SERVPRO territory in a hurricane-adjacent coastal county behaves nothing like a SERVPRO territory in a dry inland market, even though the franchise agreement, royalty structure, and training are identical.
Territory availability is the final practical gate: SERVPRO's density means many metro territories are already sold, while 911 Restoration and PuroClean still have more open territory in mid-sized markets as of recent franchise disclosure filings. Always confirm current territory maps directly with the franchisor's development team before anchoring on a brand purely by reputation or name recognition.
Concrete numbers behind each option
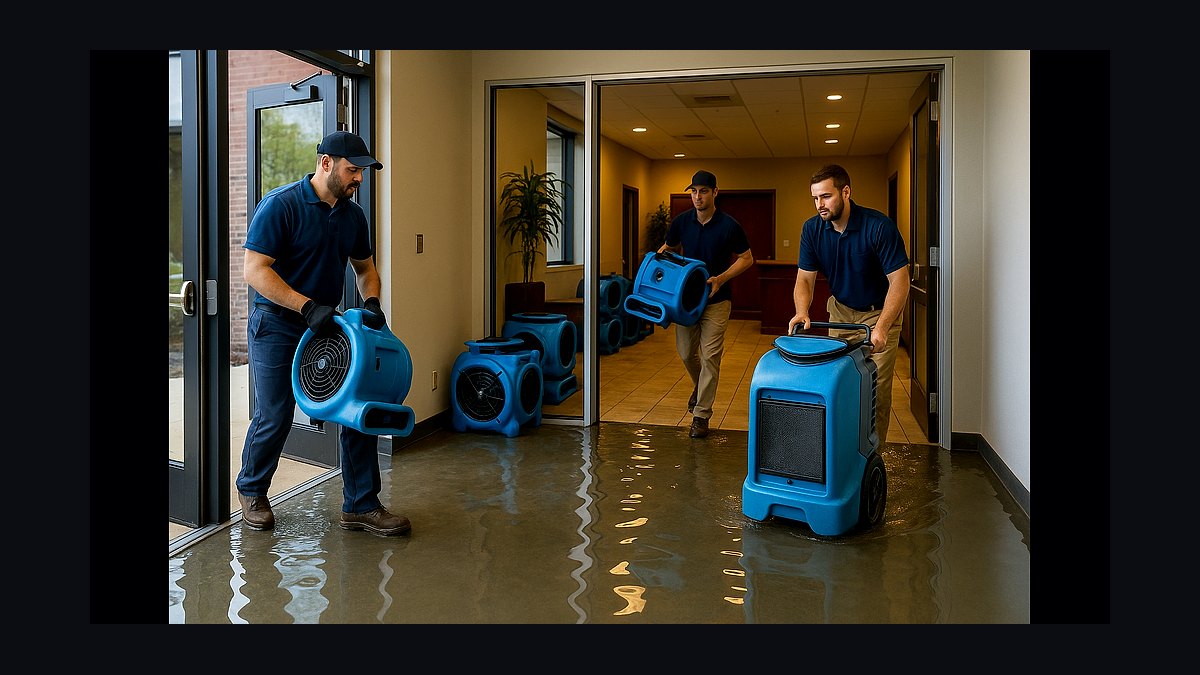
The figures below reflect the Franchise Disclosure Document ranges most recently reported by each brand; always request the current-year FDD before relying on any number, since these are reissued annually and ranges shift with inflation, insurance claim trends, and brand expansion plans.
- SERVPRO — Item 7 total investment commonly $210,000 to $270,000; franchise fee around $49,000; royalty on a sliding scale roughly 3% to 10% of gross revenue as volume grows. Deepest insurer-referral network in the category, which shortens the ramp to steady volume for a new owner.
- PuroClean — Item 7 commonly $95,000 to $245,000, among the lower entry points for a nationally recognized restoration brand; royalty around 10% plus a brand development fund contribution. Strong first-time-owner onboarding and the clearest residential-to-commercial training path of any brand in the category.
- Paul Davis Restoration — Item 7 commonly $280,000 to $700,000+, reflecting larger territories and built-in commercial capability; royalty around 2.5% to 3%, notably lower than peers, which partly offsets the higher upfront investment over a multi-year horizon.
- Rainbow Restoration — Item 7 commonly $190,000 to $300,000; royalty around 3% to 10%; benefits from shared Neighborly back-office infrastructure — call center, cross-brand referrals, shared software — that lowers overhead a standalone brand would carry alone.
- 911 Restoration — Item 7 commonly $80,000 to $250,000, the lowest floor in the category, built on a marketing-driven lead-generation model rather than deep insurer relationships; verify the current lead-cost structure carefully, since this model shifts more of the ongoing cost into paid digital marketing rather than referral networking.
- BluSky Restoration — commercial and large-loss focus with a materially higher capital bar than the residential brands; confirm the current FDD directly, as BluSky's investment range is less standardized across territories than the residential brands' published figures.
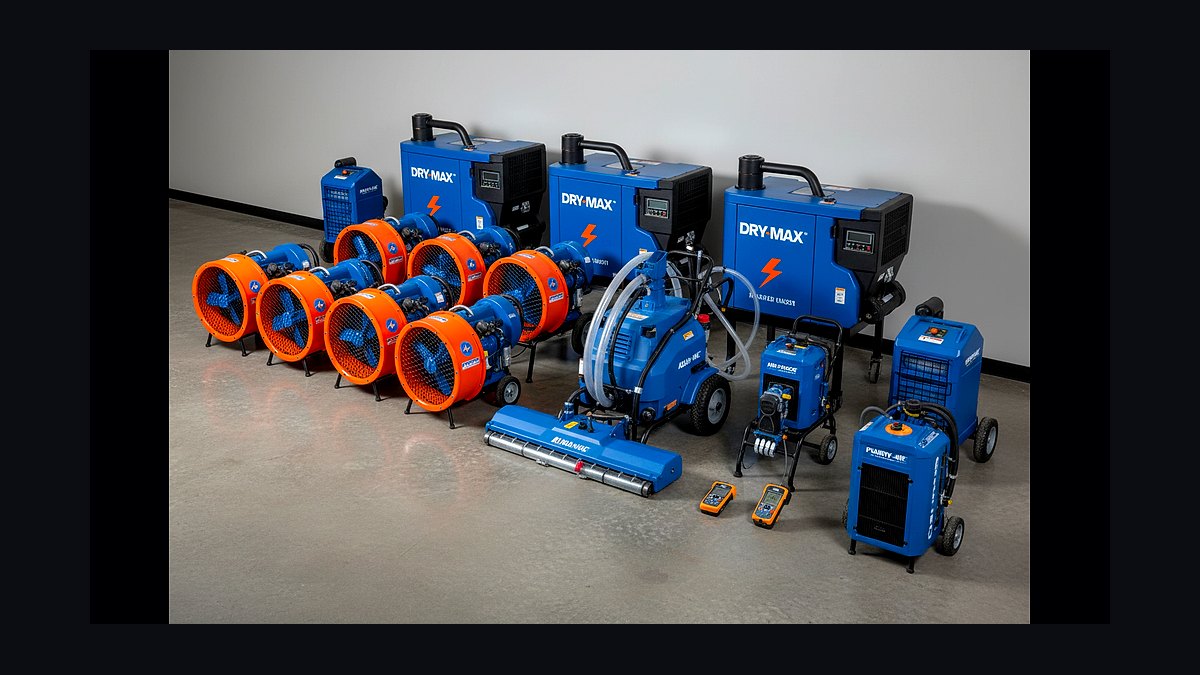
Beyond Item 7, every brand in this category shares a second cost layer the headline range does not fully capture: working capital to bridge the 30-to-90-day gap between performing the disaster-recovery work and collecting from an insurance carrier. Underfunding this gap — not underfunding the franchise fee — is the most common cause of early failure in restoration, because payroll and equipment costs are due immediately while reimbursement lags well behind. First-year equipment spend (air movers, dehumidifiers, moisture meters, HEPA vacuums, containment barriers, generators for extended power-loss jobs) commonly runs $50,000 to $120,000 on top of Item 7, and brands pushing drone-based roof and large-site inspection add another $15,000 to $30,000. Technician certification through the IICRC adds a smaller but recurring training-line cost as you scale headcount, and fleet costs — vans, trailers, and the fuel and maintenance that come with 24/7 dispatch — are frequently underestimated by first-time buyers comparing brands purely on the published Item 7 ceiling.
A related economic wrinkle worth flagging: several brands now report that commercial mold-remediation and biohazard/trauma-scene cleanup add-on services carry materially higher margins than standard water and fire mitigation, because fewer competitors are certified to perform them and insurance reimbursement rates for specialized remediation tend to run higher per labor hour. A franchisee evaluating two otherwise-similar residential brands should ask each development team how actively they support these adjacent certifications, since that answer often predicts long-run margin more reliably than the headline royalty rate.
Implementation details and sequencing
The sequencing above matters because skipping steps — particularly the validation calls and the working-capital buffer — is where most restoration franchise failures originate, not in the operational cleanup work itself. Start by requesting the current-year FDD and reading Item 7 (investment), Item 6 (the full royalty and fee schedule, including any escalation clauses tied to revenue tiers), Item 19 (financial performance representations, which many restoration brands omit entirely or present only in narrow ranges), and Item 20 (unit counts, closures, transfers, and the franchisee list you'll use for validation calls).
Call at least ten to fifteen current franchisees, weighting toward owners in their third to fifth year, since that tenure has typically weathered a full storm cycle plus at least one slow season. Ask each one: average job size, jobs per month in peak versus off-season, the percentage of revenue from insurance referrals versus direct marketing, actual collection time from carriers, and crew turnover rate — restoration work is physically demanding and irregular-hours, and turnover above roughly 40% annually signals a brand or territory that will struggle with response-time quality and, downstream, with referral retention from adjusters who need reliable crews.
Once you've chosen a brand and territory, the capital-raise step should explicitly size the 30-to-90-day receivables gap, not just the Item 7 total — this is the single most common underestimate in restoration franchise budgeting, and lenders familiar with the category will often ask for this number directly before extending a line of credit. Equipment ordering and IICRC certification enrollment can run in parallel with the final financing steps, since lead times on industrial dehumidifiers and technician certification scheduling can stretch several weeks, particularly during peak storm season when every brand's franchisees are ordering simultaneously.
Referral-relationship building — the plumber, adjuster, and property-manager network — should start before your grand opening, not after. A restoration franchise with no referral pipeline at launch sits idle waiting for a first call, burning working capital with no incoming revenue while the clock on loan payments and lease obligations keeps running regardless. Only once equipment, certified crew, and an initial referral list are in place should you consider the territory "live" for true emergency dispatch. A final sequencing note that applies across every brand in this category: many new owners under-invest in a basic answering/dispatch system for the first ninety days, assuming they can personally field every call — a single missed 2 a.m. call to a competing restoration company in the same disaster event can cost a referral relationship permanently, since adjusters and property managers remember who answered and who didn't.
Related questions
How long does it take a restoration franchise to break even?
Most franchisees report break-even within 12 to 24 months, extending to 36 months in competitive markets. Speed depends on how quickly you build insurer and property-manager referral relationships and how well you've funded the insurance-payment working-capital gap.
Can I run a restoration franchise part-time?
No. Restoration requires true 24/7 on-call emergency response, since water, fire, and storm damage do not wait for business hours. Franchisors generally require active daily owner involvement, especially in the first several years of the territory.
Do residential restoration franchises require construction experience?
Not necessarily — most franchisors provide full technical training. A background in sales, operations, or trades shortens the learning curve, but the core skills are crew management, insurance-claim navigation, and rapid emergency response.
What's the difference between restoration and general contracting franchises?
Restoration responds to sudden damage events (fire, flood, mold, storm) and is largely insurance-paid with urgent timelines; general contracting is typically planned, scheduled renovation work billed directly to the property owner without the same emergency-response demand.
How does storm season affect restoration franchise cash flow?
Storm season drives sharp volume spikes that strain crew capacity and equipment availability, while the off-season brings leaner, more predictable work. Franchisees who staff and stock for peak storm demand year-round often carry excess cost during calmer months.
FAQ
What is the typical profit margin for a restoration franchise? Profit margins generally range from 10% to 20% of gross revenue, with first-year margins often lower due to startup costs. Margins depend on controlling labor, equipment, and marketing expense while maintaining strong insurance-reimbursement rates.
How quickly can I expect to break even on my investment? Most franchisees report breaking even within 12 to 24 months, with some taking up to 36 months in competitive markets. Speed depends on how fast you build insurer and property-manager relationships and local demand for disaster-recovery services.
Do I need prior restoration or construction experience to succeed? No — most franchisors provide comprehensive training, though a background in business management, sales, or trades shortens the learning curve. The core skills are crew management, insurance-claim navigation, and round-the-clock emergency response.
What ongoing royalty and marketing fees should I expect? Royalties typically run 3% to 10% of gross sales, with marketing fund contributions adding another 1% to 3%. Several brands use tiered structures where the effective rate decreases as revenue grows, so review each current FDD carefully.
How do restoration franchises generate customers? Customer flow comes primarily from insurance-company referrals, property managers, plumbers, and real estate agents rather than mass advertising. Building and maintaining those referral relationships is an ongoing, hands-on effort even with co-op marketing fund support.
Is commercial or residential restoration more profitable per job? Commercial jobs carry far larger tickets ($50,000-$500,000+ versus $3,000-$15,000 residential) but take months to close and complete, with a much longer sales cycle to land accounts. Residential volume is less lucrative per job but cycles cash faster and has a shorter learning curve.
Sources
- U.S. Federal Trade Commission, Franchise Rule and FDD disclosure requirements (Items 6, 7, 19, 20)
- SERVPRO Franchise Disclosure Document
- PuroClean Franchise Disclosure Document
- Paul Davis Restoration Franchise Disclosure Document
- Rainbow Restoration Franchise Disclosure Document
- U.S. Small Business Administration, franchise financing and loan eligibility guidance
- Institute of Inspection, Cleaning and Restoration Certification (IICRC), technician training standards
- International Franchise Association, franchisee validation and due-diligence guidance
Related on PULSE
- Should I open or buy a Restoration 1 franchise in 2027?
- Should I open or buy a BluSky Restoration franchise in 2027?
- Should I open or buy a Rainbow Restoration franchise in 2027?
- Should I open or buy a 911 Restoration franchise in 2027?
- Should I open or buy a Paul Davis Restoration franchise in 2027?
- Should I open or buy a Rainbow International Restoration franchise in 2027?
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-franchisesBest ice cream and frozen dessert franchises to buy in 2027
 pulse-franchisesBest moving and junk-removal franchises to buy in 2027
 pulse-franchisesHow much does it really cost to open a franchise in 2027?
 pulse-franchisesShould I open or buy a Jan-Pro franchise in 2027?
 pulse-franchisesShould I open or buy a Days Inn franchise in 2027?
 pulse-franchisesWhat should you know before investing in Franchises in 2027?
 pulse-franchisesHow do franchise royalty and marketing fees work in 2027?
 pulse-franchisesBest franchises for veterans in 2027
 pulse-franchisesBest franchises to buy under $100,000 in 2027
 pulse-franchisesBest home services franchises to buy in 2027