
Should I open or buy a Goddard School franchise in 2027?
 Curated byKory White · Fractional CRO · Maryland
 PULSEKNOWLEDGE LIBRARY
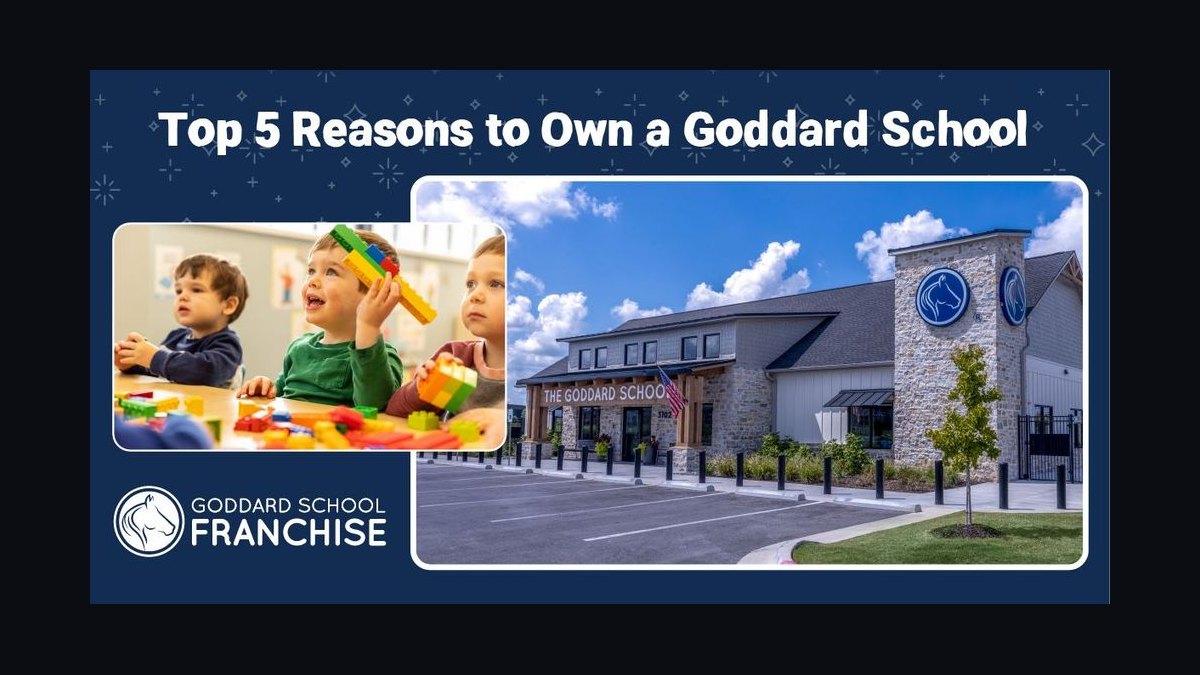
Open or buy a Goddard School franchise in 2027 only if you can deploy $350,000+ liquid capital, meet the $700,000 net worth floor, personally guarantee a $1M+ build-to-suit lease, and work on-site full-time for 24 months. Expect $952,500–$1,363,000 total investment, breakeven near month 18–24, and mature-unit AUV around $2.3M.
The outcome you should expect
A Goddard School franchise is not a passive investment, and the outcome curve is shaped almost entirely by how fast you fill classrooms. The realistic 2027 picture looks like this: you sign a 20-year franchise agreement, wire a $135,000 initial franchise fee, and then spend 10–16 months on site selection, construction, and state childcare licensing before a single tuition dollar arrives. During that pre-opening window you are paying rent, insurance, and key staff salaries with no offsetting revenue, which is why working capital of $180,000–$235,000 sits inside the initial investment range.
Once the doors open, assume you start with 40–65 enrolled children against a licensed capacity of 140–180. At an average tuition of roughly $1,650–$2,400 per child per month depending on metro, that is annualized revenue of about $900,000–$1,500,000 in year one. Royalty and brand fund alone consume 11% of that, so $99,000–$165,000 leaves the building before payroll. Year-one cash flow realistically lands somewhere between negative $80,000 and positive $120,000 — a wide band that is entirely a function of enrollment velocity, not luck.
By year two, a well-run school typically ramps to 90–120 children, pushing revenue to $1.9M–$2.4M and EBITDA into the $280,000–$420,000 range. By year three and beyond, mature units in the system report a median annual unit volume near $2.3M with average EBITDA around $521,987, which implies an EBITDA margin near 22.7%. That is a genuinely strong unit economic profile for service franchising — comparable to or better than many restaurant and fitness concepts — but it is only reachable if you survive the ramp without exhausting your liquidity.
The payback math follows directly. On a build-to-suit lease, cash-on-cash payback typically runs 4–6 years. If you instead buy land and build your own facility, total investment jumps to roughly $5.23M–$8.57M and payback stretches to 8–12 years, though you also capture real estate appreciation and avoid lease escalation. Most first-time Goddard franchisees choose the lease path because it preserves capital for the operating ramp.
The single most important variable in that entire model is the School Director. A strong Director holds teacher turnover down, keeps classrooms in ratio, and converts waitlist inquiries into enrolled families. A weak Director produces the opposite: staff churn, parent complaints, Google reviews that suppress inquiry volume, and an enrollment ceiling that never lifts. Budget $75,000–$95,000 base plus bonus for this hire and treat it as the highest-leverage dollar you spend.
What drives that outcome
Four levers determine whether your Goddard School lands at the top or bottom of the outcome band: site demographics, enrollment velocity, labor cost control, and licensing speed. Each one compounds the others, which is why the failure modes cluster rather than distribute evenly.
Site demographics. The build-out cost is essentially fixed regardless of location, but the revenue ceiling is not. A site with median household income above $110,000, dual-income household rates above 65%, and more than 4,500 children ages 0–6 within a three-mile radius can support 140–180 enrolled children and $2.3M+ in revenue. The same building in a corridor with $85,000 median household income caps out near 90 children and roughly $1.4M. Same capital outlay, roughly $900,000 less annual revenue. This is the most expensive mistake in the model and it is made before you open.
Enrollment velocity. Tuition is recurring revenue, so every month of delay in filling seats is permanent revenue you never recover. Top operators start pre-marketing 90–120 days before opening through hospital partnerships, pediatrician offices, and local parent Facebook groups. Schools that open with 40 children instead of 65 take an extra 6–9 months to reach the same revenue run rate, which directly extends the payback period.
Labor cost control. Payroll needs to stay near 45% of revenue for healthy unit economics. The national childcare turnover rate runs around 26% annually, and schools that pay 15–20% below local market for lead teachers lose enrollment because parents notice classroom instability. Underpaying teachers is a false economy: the savings show up in payroll and disappear twice over in enrollment.
Licensing speed. State childcare licensing can take 6–14 months. Signing a lease before licensing approval means burning $30,000–$60,000 in rent with zero revenue. Sequence licensing paperwork to start the day you sign the franchise agreement, not after construction completes.
Benchmarks and realistic ranges
These are the numbers to hold yourself to during diligence and during the first 24 months of operation. They come from the franchisor's published disclosure materials and from the operating realities of the childcare sector.
Capital requirements. Minimum liquid capital is $350,000 and minimum net worth is $700,000. In practice, operators who arrive with $500,000+ liquidity and $1.2M+ net worth survive the ramp without panic. The $350,000 floor is where you sweat every payroll cycle.
Initial investment. Total initial investment for a build-to-suit lease scenario runs $952,500–$1,363,000. That breaks down roughly as: $135,000 franchise fee; $25,000–$75,000 in site selection and real estate deposits; $250,000–$475,000 construction allowance or tenant improvement; $185,000–$245,000 in equipment, furniture, and playground; $65,000–$95,000 in curriculum, technology, and signage; $20,000–$35,000 pre-opening marketing; $15,000–$25,000 training and travel; $180,000–$235,000 working capital; and $77,500–$138,000 in insurance, licenses, and legal. Buying land and building outright runs $5,230,000–$8,570,000.
Ongoing fees. Royalty is 7% of gross revenue, paid weekly. Brand fund contribution is 4% of gross revenue. Combined, 11% of every tuition dollar leaves before you pay a single teacher.
Revenue benchmarks. Mature units open 18+ months report a median AUV of approximately $2,300,000 across roughly 660 US units. Average EBITDA for mature units is approximately $521,987, implying a margin near 22.7%. Year-one revenue for a school at 65 children paying $1,950 average monthly tuition annualizes to about $1,521,000 — well below mature AUV, which is the entire point of the ramp.
Cost benchmarks. Payroll at 45% of revenue is the target. Lead teacher wages rose 8.4% in 2026 per Bureau of Labor Statistics data, and property insurance for childcare facilities rose roughly 22% year over year in 2026. Both are real headwinds to margin that you should model explicitly rather than assume away.
Time benchmarks. Licensing: 6–14 months. Breakeven: month 18–24. Payback on build-to-suit: 4–6 years. Owner hours: 55–65 per week for the first 24 months, dropping to 40–50 once a strong Director is seated.
Risks, edge cases, and failure modes
The failure modes in this franchise are well documented and largely avoidable, but only if you name them before you sign.
The passive-investor trap. Goddard requires owner-operator engagement. You must live within driving distance and be on-site daily for the first year. Franchisees who treat this as absentee ownership consistently underperform because no hired manager has the equity incentive to grind through the ramp.
The personal guarantee. Every Goddard lease requires a personal guarantee from the franchisee. If the school underperforms and you cannot make rent, the landlord can pursue your home equity and other personal assets. This is not a theoretical risk — it is the mechanism by which a bad site decision becomes a personal financial event. Negotiate carve-outs and a guarantee burn-down schedule with your franchise attorney.
The wrong-site decision. Covered above, but it deserves repetition as a failure mode: a site below the demographic thresholds caps enrollment near 90 children instead of 160, permanently. There is no operational fix for a bad trade area.
Slow licensing. Operators who sign a lease before licensing approval burn $30,000–$60,000 in rent with zero revenue. Sequence this correctly.
The weak Director hire. Replacing a bad Director after 12 months typically costs $40,000–$80,000 in lost enrollment, plus the recruiting cost of the replacement and the institutional knowledge that walks out the door. Hire slowly, pay above market, and involve yourself in the first 90 days of their tenure.
Waitlist neglect. Top Goddard schools maintain waitlists of 30–60 families. Operators who stop recruiting pregnant mothers through hospital partnerships and pediatrician referrals start each year with 20–30% enrollment gaps. Enrollment marketing is not a launch activity; it is a permanent operating function.
Market saturation. Dallas–Fort Worth, Phoenix, Charlotte, and Nashville are oversupplied with premium childcare capacity. Suburban Northeast, Pacific Northwest, suburban Chicago, and suburban Atlanta remain underserved. Territory quality varies enormously and is worth validating independently.
Regulatory and cost inflation. Fourteen states raised minimum teacher qualifications in 2026, which advantages franchise systems with established training infrastructure but raises your labor cost. Property insurance and wage inflation are the two largest margin headwinds entering 2027.
A practical rollout plan
Ninety days from inquiry to franchise agreement signature is achievable if you move deliberately. Here is the sequence that works.
Days 1–14: Qualify yourself. Submit the franchise inquiry through the official Goddard franchise site and complete the confidential personal profile. Verify you clear the $350,000 liquidity and $700,000 net worth floors with a CPA-stamped personal financial statement. If you are below the floors, stop here.
Days 15–25: Read the FDD. Take the initial call with franchise development, then request and read the full Franchise Disclosure Document. Focus on Item 7 (initial investment), Item 19 (financial performance representations), Item 20 (system outlets and franchisee list), Item 21 (franchisor financials), and Item 22 (contracts). Read Item 19 carefully — it is the only place the franchisor is legally accountable for performance claims.
Days 26–40: Attorney review. Hire a franchise attorney ($4,000–$8,000) to red-line the 20-year franchise agreement and the build-to-suit lease. Non-negotiable items to flag: territory protection radius, personal guarantee carve-outs and burn-down, transfer fees, and post-term non-compete scope.
Days 41–55: Validation calls. Call 8–12 existing franchisees from the Item 20 list. Ask each one the same four questions: real year-one revenue, time to breakeven, weekly hours worked, and would you do it again. A system where more than half of validators say they would do it again is healthy.
Days 56–65: Site selection. Goddard's real estate team identifies 3–5 candidate sites in your approved territory. Pull the demographics yourself: child population ages 0–6 within three miles, median household income, dual-income household rate, and competitor density. Reject any site below 4,500 children in the three-mile ring.
Days 66–75: Discovery Day. Travel to Goddard headquarters in King of Prussia, Pennsylvania. Meet leadership, tour an active school, and treat it as mutual evaluation — the franchisor rejects a substantial share of candidates at this stage.
Days 76–82: Financing. SBA 7(a) loans are the most common path, with approvals above $1M for qualified candidates and 10-year amortization at SBA-capped rates. Lenders with existing Goddard portfolios include Live Oak Bank, Byline Bank, Celtic Bank, and First Bank of the Lake.
Days 83–88: Sign and wire. Execute the franchise agreement and wire the $135,000 franchise fee. Begin state childcare licensing paperwork the same week — this is the longest pole in the tent.
Days 89–90: Hire the Director. Make your School Director offer before construction completes. Pay above market. Start community pre-marketing through hospital partnerships, pediatrician offices, and local parent groups.
Related questions
How much liquid capital do I need to open a Goddard School in 2027?
The franchisor requires a minimum of $350,000 in liquid capital and $700,000 in net worth. In practice, operators who arrive with $500,000+ liquidity and $1.2M+ net worth navigate the 18-month enrollment ramp far more comfortably, because working capital of $180,000–$235,000 sits inside the initial investment.
Can I buy an existing Goddard School instead of opening a new one?
Yes, and it is often the faster path. Buying an existing school means you inherit an enrolled family base, a licensed facility, and a trained staff, which eliminates the 10–16 month pre-opening window. Expect to pay a multiple of EBITDA for a mature unit, and expect the franchisor to review you under the same capital and owner-operator standards.
What ongoing fees does a Goddard School franchisee pay?
Royalty is 7% of gross revenue, paid weekly, plus a 4% brand fund contribution that funds national and local marketing. Combined, 11% of gross tuition revenue. At $1.5M in year-one revenue, that is roughly $165,000 in fees before payroll, rent, or any other operating cost.
How long until a Goddard School breaks even?
Most owners reach breakeven between month 18 and month 24 after opening. Year-one cash flow ranges from negative $80,000 to positive $120,000 depending on enrollment ramp speed. Build-to-suit cash-on-cash payback typically runs 4–6 years; buying land and building stretches payback to 8–12 years.
Do I have to be a full-time owner-operator?
Yes. The franchisor requires full-time owner-operator engagement, and you must live within driving distance of the school and be on-site daily for the first year. You also sign a personal guarantee on the lease, so passive or absentee ownership is not a viable structure for this franchise.
FAQ
What is the minimum liquid capital required to open a Goddard School in 2027? You need at least $350,000 in liquid capital and a net worth of $700,000 or more. These are franchisor-set thresholds. Practically, arriving with $500,000+ liquidity gives you room to absorb the year-one cash flow swing of negative $80,000 to positive $120,000 without stress.
How much does it cost to build a Goddard School from scratch? Total initial investment in a build-to-suit lease scenario runs $952,500–$1,363,000, including the $135,000 franchise fee, construction and tenant improvement, equipment, furniture, playground, curriculum and technology, pre-opening marketing, training, working capital, and licensing costs. Buying land and building outright runs $5,230,000–$8,570,000.
What ongoing fees does a Goddard School franchisee pay? A 7% royalty on gross revenue plus a 4% brand fund contribution, for a combined 11% of gross tuition revenue. Royalty is paid weekly. At a mature AUV of $2.3M, that is roughly $253,000 per year in combined fees.
How long does it take to break even on a Goddard School? Most owners reach breakeven between month 18 and month 24 after opening. The variable that moves this most is enrollment velocity in the first six months, which is driven by site demographics and pre-opening marketing rather than by anything you can fix after opening day.
What is the typical revenue and profit for a mature Goddard School? Mature units open 18+ months report a median AUV of approximately $2,300,000 and average EBITDA of approximately $521,987, implying a margin near 22.7%. Individual results vary widely based on site demographics, tuition pricing, labor cost control, and Director quality.
Can I be a passive investor in a Goddard School? No. The franchisor requires full-time owner-operator engagement, on-site daily presence for the first year, and residency within driving distance. You also sign a personal guarantee on the build-to-suit lease, so the downside risk is personal, not just corporate.
Sources
- The Goddard School Franchise Disclosure Document — Item 5, Item 6, Item 7, Item 19, Item 20, Item 21, Item 22
- International Franchise Association Economic Outlook — franchise sector growth and regulatory trends
- US Bureau of Labor Statistics — childcare worker wage data and employment projections
- US Small Business Administration — SBA 7(a) loan program terms and eligibility
- IBISWorld Day Care Industry Analysis — US childcare market size and growth rate
- Grand View Research US Child Care Market Report — long-range childcare market projections
- Franchise Business Review — franchisee satisfaction data across childcare brands
- Federal Reserve Economic Data — household income, labor participation, and inflation series
- Child Care Aware of America — state licensing requirements and childcare supply data
- US Census Bureau — demographic data for trade area analysis
Related on PULSE
- [Should I open or buy a Primrose Schools franchise in 2027?](/knowledge/fr1057)
- [Should I open or buy a The Learning Experience franchise in 2027?](/knowledge/fr1058)
- [Should I open or buy a Celebree School franchise in 2027?](/knowledge/fr0921)
- [Should I open or buy a Lightbridge Academy franchise in 2027?](/knowledge/fr1059)
- [Should I open or buy a Kids 'R' Kids franchise in 2027?](/knowledge/fr1060)
- [Should I open or buy a School of Rock franchise in 2027?](/knowledge/fr1056)
Read it free — or make it yours for $1.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
 franchiseShould I open or buy a Chipotle franchise in 2027?
 franchiseShould I open or buy a Cooper's Hawk Winery & Restaurants franchise in 2027?
 franchiseShould I open or buy an L&L Hawaiian Barbecue franchise in 2027?
 franchiseShould I open or buy a Harvey's franchise in 2027?
 franchiseShould I open or buy a Pizza Inn franchise in 2027?
 franchiseShould I open or buy a Closets by Design franchise in 2027?
 franchiseShould I open or buy a Pollo Tropical franchise in 2027?
 franchiseShould I open or buy a Mountain Mike's Pizza franchise in 2027?
 franchiseShould I open or buy a Panera Bread franchise in 2027?
 franchiseShould I open or buy a sweetFrog franchise in 2027?