
Financial Advisor — 60-Min Training
 Curated byKory White · Fractional CRO · Maryland
 PULSEKNOWLEDGE LIBRARY
A 60-minute financial advisor training installs one discipline: run discovery in five stages — FRAME, LIFE, MONEY, GAPS, PATH — and never open a portfolio deck before the gaps land. Wrap it in three compliance pillars: best interest, disclosure, no pressure. Ask about the family before the assets, always.
Two ways to build the hour: teach the framework, or drill the failure
Every branch manager who schedules a 60-minute advisor training faces the same fork, and most pick wrong by default. Option A is the teach-forward hour: spend the bulk of the time explaining a discovery framework, walking the compliance overlay, showing a slide with the five stages, and reserving whatever minutes survive for questions. Option B is the drill-forward hour: spend a compressed block installing vocabulary, then hand the majority of the clock to live role-play against realistic prospect deflection, and close with a written commitment tied to a named, real, unconverted prospect.
The teach-forward hour feels productive because it covers ground. An advisor leaves able to name FRAME, LIFE, MONEY, GAPS, PATH, and to describe what each stage does. That is recognition, not capability. Recognition decays fast — the practitioner rule of thumb across sales enablement is that un-rehearsed content has a short shelf life measured in weeks, and the reversion shows up first under pressure. The moment a prospect says "so what do you actually do?" at minute eight, the advisor who has only heard the framework described reaches for the deck, because the deck is the thing they have said out loud a hundred times and the FRAME opener is the thing they have said zero times.
The drill-forward hour feels chaotic and produces better field behavior, for a boring reason: the advisor has now spoken the words under mild social pressure while a peer plays a skeptical widow or a time-starved founder. That is the entire mechanism. Language you have physically produced once is retrievable; language you have only read is not.
There is a third option worth naming because managers reach for it constantly: the ride-along-only approach, where no classroom hour happens and coaching occurs entirely in the field. It has real advantages — the reps are live, the stakes are genuine, the feedback is specific to that advisor's actual book. Its failure is throughput. A branch manager with twelve advisors who observes one discovery per advisor per quarter delivers forty-eight coaching touches a year across the whole team. The 60-minute group hour plus a weekly CRM note audit delivers something closer to twelve touches per advisor per quarter at a fraction of the manager's calendar. Ride-alongs are the right *supplement* and the wrong *substitute*.
The recommendation: run drill-forward, with a hard-capped teach block. Cold open five minutes, teach seventeen, structured discussion ten, two role-plays twenty, debrief and commitment five, leave-behind three. The seventeen-minute teach cap is the load-bearing constraint. It is not a suggestion — it is the thing that prevents the hour from silently converting into option A. A manager who lets the teach run to thirty minutes has run a different meeting than the one they scheduled, and the role-plays get amputated first because they are last on the clock.
How to decide between them
The decision is not purely philosophical; it turns on four readable conditions in your specific branch.
Condition one: does the team already have shared vocabulary? If nobody in the room can name a discovery sequence, you need a real teach block — you cannot drill language that does not exist yet. If this is the second or third run of the same training, cut the teach to eight minutes and buy back twelve for a third role-play. The teach block is front-loaded investment that amortizes across repeat sessions.
Condition two: what does the CRM actually say? Before you pick a format, pull ninety days of discovery notes for the team. If the notes are fact-finder forms with checkboxes and account balances and nothing about the family, the gap is LIFE and GAPS, and role-play is the only fix — you cannot lecture someone into asking a better open-ended question. If the notes are rich but second meetings never get calendared, the gap is PATH, which is a much narrower fix and might not need the full hour at all.
Condition three: tenure mix. A room of third-year producers building a book needs the teach; they are still assembling a repeatable motion. A room of twenty-year senior partners taking multi-generational referrals needs the drill and will resent the teach — and they are also the population most likely to be carrying habits formed before Reg BI and before the SEC's 2022 marketing rule tightened performance and testimonial claims. The uncomfortable framing for that room: the habits that built your book are now exam-deficiency categories. That lands better as a role-play consequence than as a slide.
Condition four: does the manager have the appetite for the follow-through? This is the one that actually decides whether the hour was worth running. Neither option survives without a weekly audit ritual. If the manager will not pull one discovery note per advisor per week and review it in the 1:1, run the cheaper hour and be honest that it is a morale event, not a capability build.
A note on sequencing that managers get backwards: the diagnostic discussion belongs *before* the role-play, not after. Ten minutes where each advisor names a real unconverted prospect and identifies which stage collapsed does two things — it makes the role-play personal instead of theatrical, and it gives the manager the data for the debrief. Advisors who have just admitted out loud that they skipped the no-pitch contract role-play the no-pitch contract very differently from advisors who have not.
The five stages, and the numbers each one moves
The framework is the content of the teach block. It describes a client discovery meeting of roughly forty-eight minutes — which is a different thing from the sixty-minute training that teaches it, and conflating the two is the single most common confusion in the room. Say it explicitly at minute five.
FRAME — five minutes. Set the no-pitch contract, disclose the engagement type, put Form CRS on the table. The verbatim: *"For the next hour, my only job is to understand what matters to you and your family. I won't pitch you anything today. If at the end you'd like to keep talking, we'll schedule a second meeting where I bring a written plan. If not, you'll walk out with three things you could act on with anyone. Sound fair?"* Then slide Form CRS across and walk it verbally — how you're paid, the relationship type, the conflicts. The load-bearing two words are *sound fair* — you need the verbal yes. Without explicit permission the prospect spends the next forty minutes waiting for the pivot, and everything they say is guarded. The most common collapse: skipping the contract entirely because it feels like a script.
LIFE — fifteen minutes. Open-ended questions about family, values, concerns, and what changes in the next three to five years. No product mentions of any kind. Hand-written notes on a legal pad — a laptop is a physical barrier and every advisor who has tried both knows it. Four questions carry the stage: walk me through your family, who depends on you and who you worry about; what does a great financial year look like, not in dollars but in what you'd be doing; what keeps you awake at three in the morning about money; have you worked with an advisor before, and what worked and what didn't. Then the discipline that separates competent from excellent: do not interrupt the silence after the three-in-the-morning question. That silence is the stage. Advisors who fill it with a reassuring sentence have converted a discovery into a comfort call.
MONEY — fifteen minutes. Now, and only now, the financial inventory. Account by account, by custodian. Held-away 401(k)s at every prior employer, brokerage, alternatives, crypto, business equity, rental property, vested-but-unexercised options, concentrated positions. Then liabilities, income, insurance in force, estate documents — will, revocable trust, durable power of attorney, healthcare proxy, with dates on each. Then tax: last return, effective rate. The held-away question is the one that separates advisors who consolidate from advisors who manage a slice: *"where else are assets held, even small accounts?"* Asked every time, out loud, because prospects genuinely forget the rollover from two employers ago, and that forgotten rollover is frequently the largest single account in the household.
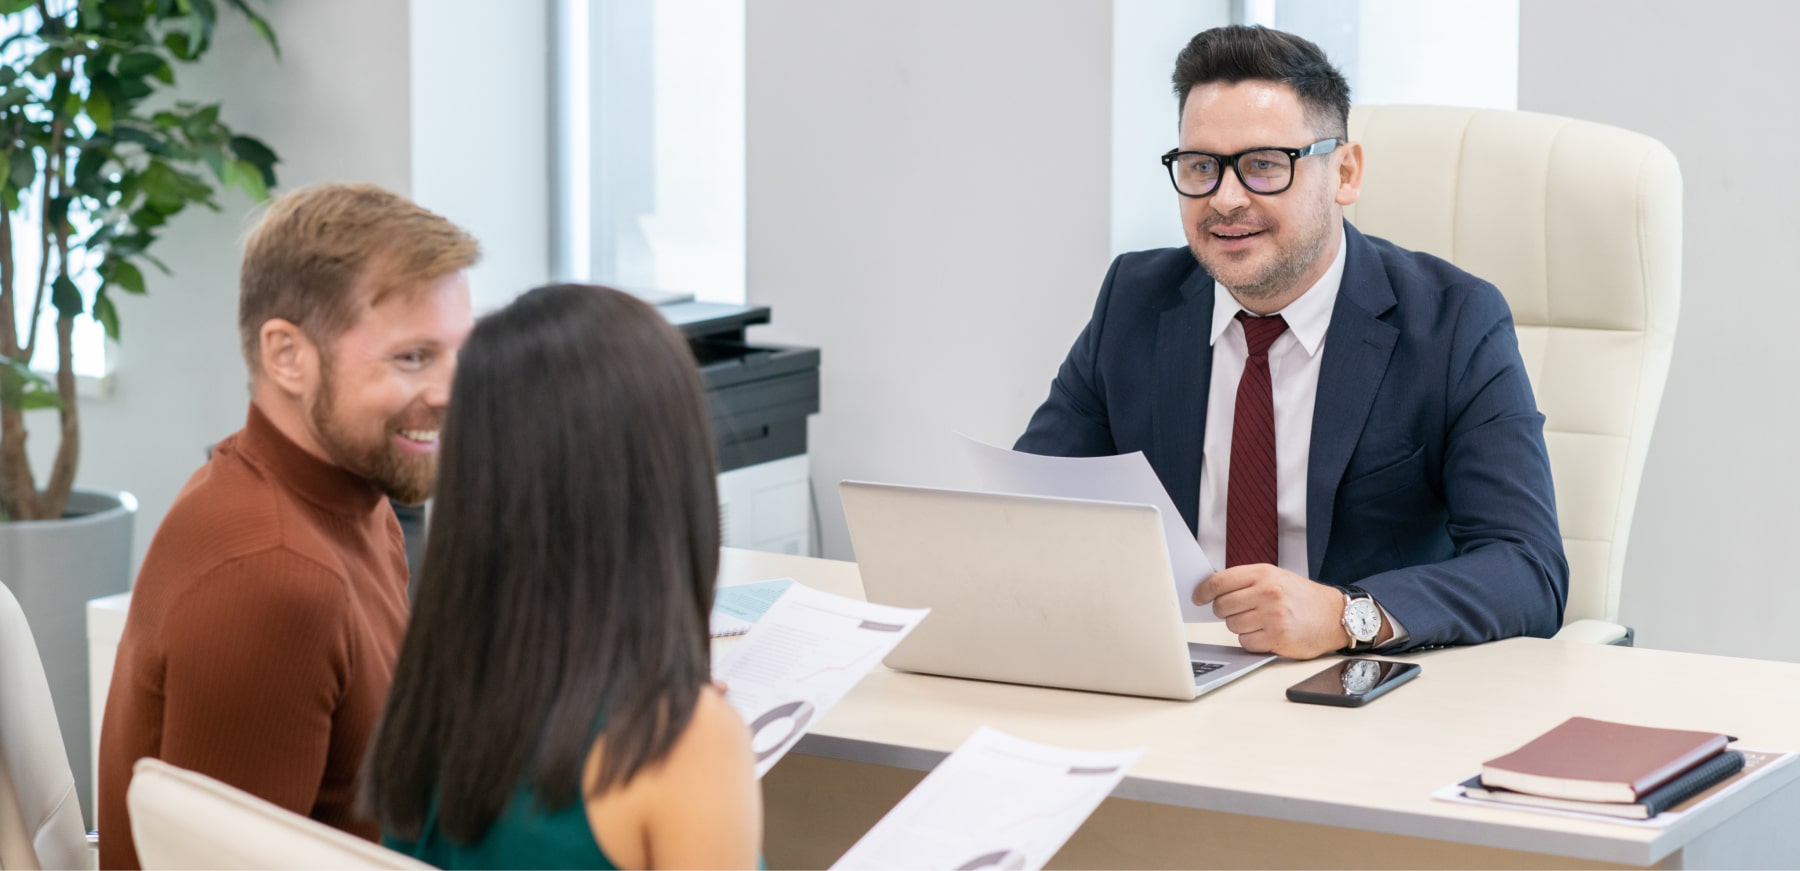
GAPS — eight minutes. State what is missing or broken, on paper, in real time, as observations and never as solutions. Three of them. Not six — six is a lecture and the prospect stops hearing individual items. The framing that makes it work is *"with or without me"*: *"your IRA beneficiary is still listed as your ex-spouse. That's a ten-minute fix at any custodian, with or without me."* The prospect hears competence with no sales pivot attached, which is a combination they have likely not experienced from the other advisors they have interviewed. The collapse is predictable and near-universal in untrained advisors: observing a concentrated single-stock position and immediately saying what you would do about it. That sentence retroactively converts every prior minute into a setup.
PATH — five minutes. A non-pressure menu, not a close. Restate the three things to act on regardless. Describe what a second meeting would cover, drawn from what *they* raised — not from your standard deck. Then calendar it in the room, before you leave, with the calendar physically open. "I'll send you a proposal" produces almost no second meetings; a date on both calendars produces most of them. And if there is a spouse who was not present, the second-meeting invitation is where you fix that: married-couple prospects convert at materially lower rates when only one spouse attended the first meeting, and the fix costs one sentence.
Wrapped around all five is the compliance overlay — three pillars, taught in five minutes. Best interest: recommend for the client, not for comp, and document the why-this-not-that rationale, because "recommendation rationale not documented" is the deficiency examiners cite first. Disclosure: Form CRS at the first meeting, ADV Part 2A brochure and 2B supplement, conflicts stated verbally rather than buried, and the *all-in* cost spoken aloud — advisory fee plus fund expense ratios plus transaction costs, not just the advisory number. No pressure: no false urgency, no performance guarantees, and no "we outperformed the market last year," which the SEC's marketing rule restricts even when the claim is true.
The two failure geometries are worth naming for the room. Stages without pillars produces an advisor who closes well and collects a disclosure event in year three. Pillars without stages produces an immaculately compliant advisor whose book stalls. You need both, and the hour teaches both because they are taught in the same breath in the field.
Running the hour: sequencing, role-plays, and the commitment ritual
The cold open gets five minutes and no slides. Say the numbers, tell one story, stop. The numbers that matter to a room of advisors are about switching and about why prospects walk: high-net-worth households now interview multiple advisors before choosing, the conversion window is roughly ninety days, and the most-cited reason for non-engagement is some version of *they talked about products before they understood what I cared about*. The generational wealth transfer underway through the mid-2040s means prospect flow is not the constraint. Discovery discipline is.
Then one composite story, ninety seconds, with a before and after. A twelve-year producer takes a CPA referral — a recently widowed engineer with a rollover IRA, a joint brokerage, concentrated employer stock, a paid-off house. The deck comes out at minute eight. Asset allocation by minute fourteen. The prospect goes quiet at minute twenty-five. Three days later: *we're going to stay with our current advisor.* Same advisor, same archetype, six months later, running the five stages: LIFE surfaces a sibling conflict over an estate, MONEY surfaces a forgotten rollover the prior advisor never asked about, GAPS observes a beneficiary designation still naming a long-divorced ex-spouse, PATH calendars a family meeting with the adult daughter present. Same prospect profile, same underlying need, different sequence, different outcome. Stories beat statistics in a branch meeting; use both, story last.
The discussion block, ten minutes. Whiteboard the five stage names across the top. Each advisor names their most recent unconverted prospect with real specifics — name, asset scope, meeting date, the last thing the prospect said — and identifies which stage broke. Refuse vagueness. "A CPA referral last spring" is not an answer; force the detail. Then count to five after each prompt. The silence is doing work; managers who fill it get shallow answers. What the whiteboard reliably shows is that FRAME and GAPS collapse most often, and those two also have the clearest verbatim fixes, which makes them the highest-leverage coaching targets for the next quarter of 1:1s.
The role-plays, twenty minutes, two rounds of about nine and a half with a sixty-second reset. Pair advisors; the manager takes the extra in an odd room. Round one should be an emotionally weighted archetype — a recently widowed prospect with inherited assets, an adult child pushing a competing advisor, and a request the advisor must refuse. The refusal is the point of the drill: when the prospect says *just promise me I won't run out of money*, the correct answer is that no advisor can promise that, and the honest answer is probabilistic. Refusing the promise is the fiduciary move, and advisors need to have said that sentence once in a low-stakes room before they say it to a grieving prospect.
Round two should be structurally different — a business owner with a pending liquidity event, a blended family, a trusted CPA already in the picture, and friends pushing an illiquid real-estate concentration. The drill here is coordination without ego conflict. The advisor must resist implying the CPA has missed things, must concede the pieces that genuinely belong to the client ("the brokerage trades are yours"), and must stay in observation mode about the estate documents that predate the current family structure. Managers should walk the room during this round specifically listening for the ego-conflict slip, because it is the most common and the most expensive.
Score both rounds against a short checklist so the debrief has data: was FRAME run verbatim with the *sound fair* ask, was Form CRS placed early, was the three-in-the-morning question asked and the silence left alone, was a held-away account surfaced, were gaps stated as observations, was the improper promise refused, was the second meeting calendared with the right people invited.
The debrief and commitment, five minutes. Three questions: which stage felt strongest and which weakest, which compliance pillar did you nearly miss, and who is the prospect you will re-run discovery with this month. Then the ritual that makes the hour survive contact with next week: every advisor opens their CRM on their phone and writes four lines — the target prospect with name and scope and original meeting date, the stage they will lead with, one verbatim language change written as the actual words they will say, and the date by which the follow-up call is logged. Read all four aloud. Coach the vague ones immediately: "I'll be more client-focused" is not a commitment; "read the FRAME opener out loud, right now" is how you fix it.
The manager's closing line does the real work: *in our 1:1 within fourteen business days I'm pulling the CRM detail on this exact prospect — not whether you got the signed agreement, but whether you ran the five stages and stayed on the three pillars.*
Where this training sits next to the rest of the enablement stack
A 60-minute discovery training is not a standalone artifact, and treating it as one is how it becomes a once-a-year ritual nobody references. It sits in a stack, and the adjacent pieces determine whether it holds.
Upstream is the referral and prospecting motion. The five stages assume a prospect who agreed to a meeting. If the branch's pipeline is thin, a better discovery hour improves conversion on a small denominator and the net-new asset number barely moves. Diagnose which constraint you actually have before scheduling the training — count first meetings per advisor per month, then conversion. If first meetings are the scarce thing, run a centers-of-influence training instead and come back to this one next quarter.
Downstream is the second meeting and the plan presentation, which is a genuinely different skill and deserves its own hour. Advisors who nail discovery and then present a forty-slide plan document at the second meeting undo the trust the first meeting built. The second-meeting discipline is roughly inverse: fewer questions, more synthesis, and a written plan built visibly from the client's own language. If you can only run two trainings a year, run discovery and second-meeting presentation, in that order.
Laterally, the same architecture transfers to other high-consideration sales motions, which is worth naming because it makes the framework easier to remember. A complex B2B discovery call has the same bones — set the agenda and get agreement, understand the operating reality before the product, inventory the current state including the systems nobody mentioned, name gaps as observations, and end with a mutually calendared next step. What does *not* transfer is the regulated disclosure perimeter and the multi-stakeholder family system. A B2B seller does not put a Form CRS on the table and does not need to think about whether the adult daughter's friend at a competing firm is in the decision. Advisors coming from a general sales background often import the mechanics and skip the family system; advisors coming from planning backgrounds often do the reverse.
The manager coaching loop is the piece that actually decides ROI, and it is not part of the hour. One discovery note per advisor per week, reviewed in the 1:1. The note should show four things: the answer to the three-in-the-morning question in the client's own words, a held-away inventory, three written observations, and a calendared second meeting with the right attendees. Notes missing all four are the coaching agenda. Rollouts without this loop revert — advisors drift back to the fact-finder form within about a month because the form is faster and nobody is looking.
Tooling matters less than managers think, but it is not neutral. Whatever CRM the practice runs, the discovery note template should have named fields for the four things above, because a free-text box gets an account balance and nothing else. Scan the hand-notes into the record; the legal pad is for the meeting, the CRM is for the audit.
Adjacent training that compounds with this one, in rough priority order: objection handling for fee conversations, which is where the pressure actually shows up; the coordination call format for bringing a client's CPA or estate attorney into a four-way conversation without ego conflict; and multi-generational engagement, which is the highest-value adjacent skill given how much wealth is about to move to a generation that has no relationship with the incumbent advisor.
When the framework is the wrong tool
Honesty about limits keeps a cohort from over-applying the hour and then dismissing the whole thing when it doesn't fit.
The full five-stage sequence is built for a first meeting with a prospective new household of meaningful complexity. It is the wrong shape for an existing client adding a held-away account — the relationship is already earned, and running a full discovery on someone who has been a client for six years reads as a strange formality. Run a focused MONEY-plus-GAPS conversation instead.
It is wrong for a prospect who only wants a one-time financial plan. The PATH stage's consolidation framing is a mismatch; scope a flat-fee planning engagement, deliver it well, and let the relationship find its own shape.
It is wrong for an institutional or retirement-plan-sponsor prospect, where a committee process and a formal request-for-proposal govern the sequence. The psychology the framework is built around is individual and family psychology.
It is wrong for a prospect in active crisis — a death last week, a divorce filed yesterday. Triage the immediate need, do the one useful thing, and schedule discovery for weeks later. Running a structured fifteen-minute LIFE stage on someone in acute grief is the wrong instinct even though the questions are good ones.
And it is wrong when the economics don't work. A referral well below the practice's service threshold deserves a warm hand-off to the firm's digital or associate channel, not a sixty-minute meeting that ends in a decline. That conversation is also a discipline worth training, separately.
The most common manager objections deserve short answers. *My advisors already know discovery* — pull ninety days of notes before you assume; the difference between the top and bottom of a branch shows up in the notes with no ambiguity. *Compliance and growth are in tension* — the inverse is closer to true; disciplined producers tend to carry both the higher conversion and the cleaner exam history, because both come from the same underlying habit of documenting why. *Senior advisors don't need this* — seniors trained before the current regulatory posture are carrying the specific habits that are now deficiency categories. *We're dually registered, doesn't Reg BI cover it* — Reg BI governs the broker-dealer recommendation, the Advisers Act fiduciary standard governs the advisory side, and state insurance best-interest rules and CFP Board obligations layer on top. The standard moves with the recommendation, which is exactly why a three-pillar mental model beats memorizing which rule applies when.
Finally, re-run the training about every ninety days, with fresh unconverted-prospect audits and rotated role-play archetypes. Third run, swap in harder scenarios: a pre-retiree executive with concentrated employer stock and a trading plan, a single executor managing an estate with adult-child friction, a divorcing spouse with a qualified domestic relations order in play. The framework stays fixed; the pressure changes.
Related questions
How long should the discovery meeting itself be?
Roughly forty-eight minutes of structured conversation — five for FRAME, fifteen for LIFE, fifteen for MONEY, eight for GAPS, five for PATH. Book sixty to leave room for arrival, family context, and the calendar close without rushing the final stage.
What if the prospect pushes for investment talk in the first five minutes?
Acknowledge and re-frame: that's exactly what the second meeting covers, and I'll bring a written plan to it — to make that plan worth your time, I need this hour to understand the family it's for. Their eagerness is data, not permission.
Should Form CRS really go on the table at minute one?
Yes. The prospect has been pitched by other advisors who led with capability and disclosed later. Leading with disclosure signals nothing to hide. Regulators permit delivery at or before the recommendation; early is the best-practice choice, not merely the compliant one.
Does the same five-stage structure work for a virtual meeting?
Mostly. Two adjustments: the legal-pad advantage disappears, so narrate your note-taking explicitly, and the silence after the three-in-the-morning question is harder to hold on video — count deliberately rather than trusting instinct.
How do I know the training worked?
Three ninety-day signals: per-advisor first-meeting conversion, disclosure delivery rate at the first meeting, and the percentage of first meetings that end with a second meeting calendared in the room. That third number is the fastest-moving and most honest.
FAQ
Does this apply to captive wirehouse advisors, or only to independent RIAs?
Entirely, both. The five stages are conversation discipline and carry no registration assumption. What shifts is the compliance overlay — a wirehouse producer operates primarily under the broker-dealer best-interest standard, a registered investment adviser under the Advisers Act fiduciary standard, and a dually registered advisor wears whichever hat the specific recommendation requires. The three pillars are written to cover all three cases, which is why they're framed as behaviors rather than as rule citations.
Is the "60 minutes" the training or the client meeting?
The training. The branch meeting runs a full hour: cold open five, teach seventeen, discussion ten, role-plays twenty, debrief five, leave-behind three. The client discovery meeting it teaches is a separate conversation of roughly forty-eight structured minutes. Say this out loud at minute five, because the room will otherwise assume the seventeen-minute teach block is a live demonstration of the discovery meeting.
What's the minimum viable version if I only have thirty minutes?
Cut the cold open to two minutes, the teach to eight, drop the discussion block, run one role-play at twelve minutes, and keep the full five-minute commitment ritual. The commitment ritual is the last thing you cut, not the first — a room that leaves with named prospects and written verbatim changes has gotten value from thirty minutes; a room that leaves having heard a framework described has not.
How do I handle an advisor who closes well but ignores the stages?
Coach to process, not to the outcome. High close rates without the disclosure and documentation discipline are the profile most likely to produce a regulatory event later, and the advisor's own results make them immune to argument. The productive move is auditing their notes for documented rationale rather than debating their conversion rate — that's a specific, checkable gap they cannot dismiss with results.
Should the leave-behind be printed or digital?
Both, but the printed one-pager is the one that changes behavior. It goes in the discovery binder and gets glanced at in the parking lot before the meeting. The digital copy lives wherever the team's templates live and gets attached to the CRM record. A one-pager that only exists in a shared drive is a one-pager nobody reads.
What's the single highest-return thing a manager does after the hour?
The weekly note audit. One discovery note per advisor, reviewed in the 1:1, checked for four things: the client's own words about what worries them, a held-away inventory, three written observations, and a calendared second meeting. Everything else in the rollout is optional; this is not.
Sources
- https://www.sec.gov/rules/final/2019/34-86031.pdf — SEC Regulation Best Interest adopting release
- https://www.sec.gov/investment/form-crs-faq — SEC Form CRS frequently asked questions
- https://www.sec.gov/investment/form-adv — SEC Form ADV information and instructions
- https://www.finra.org/rules-guidance/key-topics/regulation-best-interest — FINRA Regulation Best Interest guidance hub
- https://www.sec.gov/investment/marketing-faq — SEC Investment Adviser Marketing Rule FAQ
- https://www.cfp.net/ethics/code-of-ethics-and-standards-of-conduct — CFP Board Code of Ethics and Standards of Conduct
- https://www.cerulli.com/ — Cerulli Associates asset and wealth management research
- https://advisorservices.schwab.com/insights-hub/rias/benchmarking-study — Schwab RIA Benchmarking Study
- https://www.irs.gov/retirement-plans/rollovers-of-retirement-plan-and-ira-distributions — IRS guidance on retirement plan and IRA rollovers
- https://www.investor.gov/introduction-investing/getting-started/working-investment-professional — SEC Investor.gov guidance on working with investment professionals
Related on PULSE
- [Discovery Call Framework: Structuring the First Conversation](/knowledge/st0001)
- [The Sandler Selling System: Ready-to-Run Mini-Training for New Hires](/knowledge/st0794)
- [Overcoming Call Reluctance: Coaching Template for a Weekly Morning Huddle](/knowledge/st0793)
- [Selling with Stories: Narrative Structure Template for a 45-Minute Sales Workshop](/knowledge/st0792)
- [Sales Forecasting Accuracy: Template for a Team Meeting Focused on Data Hygiene](/knowledge/st0796)
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
 sales-trainingLife Insurance Needs Analysis — 60-Min Training
 sales-trainingMed Spa Consult-to-Package Conversion — 60-Min Training
 sales-trainingMedical Device Sales — 60-Min Training
 sales-trainingRestaurant Supply — 60-Min Training
 sales-trainingHVAC Replacement vs Repair Conversation — 60-Min Training
 sales-trainingGym Tour and Same-Day Close — 60-Min Training
 sales-trainingTitle Insurance — 60-Min Training
 sales-trainingReal Estate Listing Presentation — 60-Min Training
 sales-trainingRetained Search Pitch — 60-Min Training
 sales-trainingSolar Door-to-Door — 60-Min Training