


10 Most Affordable Places to Retire on Under $40,000 a Year (2027)
Quality
Certified
The 10 best 10 most affordable places to retire on under $40,000 a year (2027) are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Knoxville, Tennessee
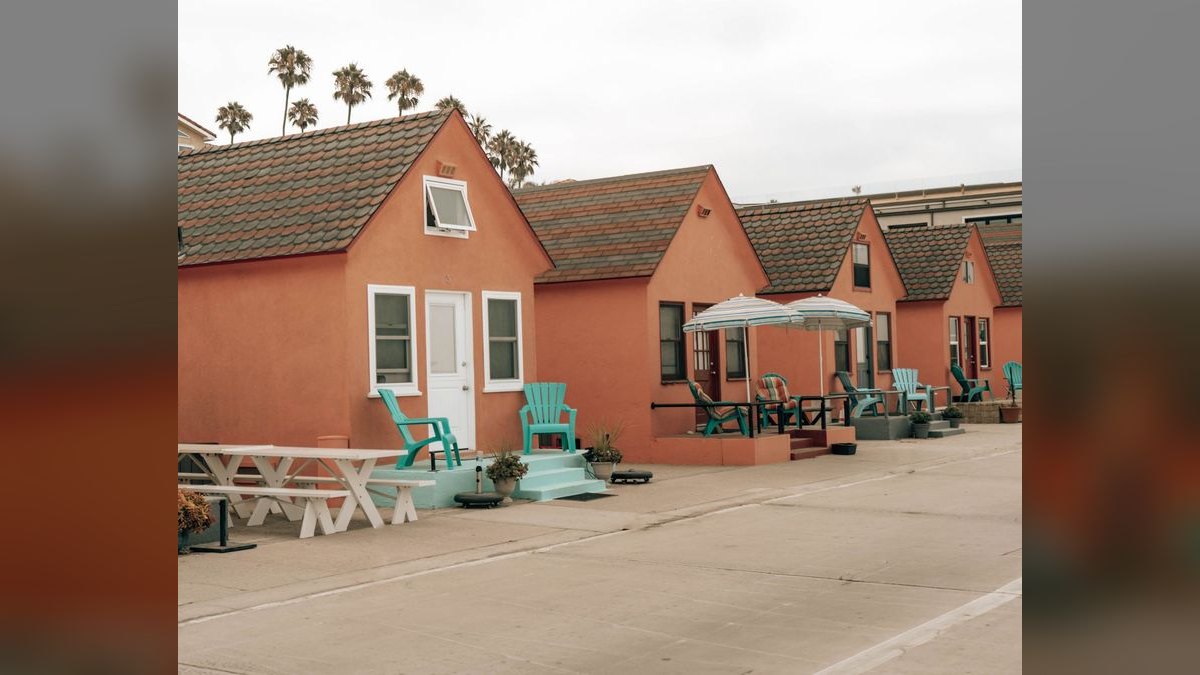
Knoxville ranks first because Tennessee levies no state income tax at all, so a $40,000 retirement arrives untouched by the state. Median home prices sit near $320,000 and two-bedroom rents average around $1,300 a month. The University of Tennessee Medical Center anchors healthcare, and the Great Smoky Mountains sit at the city's edge.
This suits couples who want four seasons, real amenities, and zero state income tax complexity. The trade is a combined sales tax near 9.55%, which costs a couple spending $18,000 on taxable goods roughly $1,700 a year. Greenville offers milder winters but a higher $330,000 median and a revocable retirement-income deduction.
2Fort Wayne, Indiana
Fort Wayne ranks second for raw value: a median home price near $235,000, two-bedroom rents around $1,050, and a cost of living roughly 12% below the national average. Indiana's flat 3.05% income tax applies only to non-Social-Security income. Parkview Health provides the regional hospital system.
Renting at $1,050 spends $12,600 a year on housing against a $38,000 spendable budget, leaving the widest margin on this list. Cold, snowy winters are the admission price. Knoxville edges it out on climate and zero state income tax, but Fort Wayne wins on housing cost and monthly slack.
3Huntsville, Alabama
Huntsville ranks third on the strength of Alabama's effective property tax rate near 0.4%, among the lowest in the nation. On a $300,000 home that is roughly $1,200 a year. The state taxes neither Social Security nor most pension income, and the cost of living runs about 10% below average.
Huntsville Hospital is a strong regional system, and the aerospace economy keeps the city growing. Summers are hot and humid. Fort Wayne offers cheaper housing and a wider monthly margin; Huntsville counters with lower property tax and a stronger job-driven local economy that supports services.
4Jackson, Mississippi
Jackson ranks fourth because Mississippi's statewide median home price near $190,000 is the lowest entry point on this list. The state exempts all retirement income, including Social Security, pensions, and 401(k) withdrawals. The University of Mississippi Medical Center serves as the metro's main hospital.
The caveats are thinner healthcare access outside that academic anchor and severe summer heat. Huntsville above it pairs a similar tax posture with a stronger regional economy and better specialty depth. Jackson is for retirees prioritizing the absolute lowest housing line over amenity and access.
5Tulsa, Oklahoma
Tulsa ranks fifth with a median home price near $230,000 and a cost of living roughly 13% below the national average. Oklahoma exempts Social Security and layers on additional retirement-income deductions. Saint Francis and Ascension both serve the metro, and downtown and riverfront reinvestment has been genuine.
Tornado risk is the regional caveat and belongs in the insurance line, not the footnotes. Jackson above it has cheaper housing and broader retirement-income exemption; Tulsa counters with more urban momentum and a deeper hospital footprint. Retirees who want a mid-sized city with arts and river trails get more here.
6Pittsburgh, Pennsylvania
Pittsburgh ranks sixth for healthcare per dollar: UPMC, one of the largest health systems in the country, anchors a metro with median home prices near $235,000 and two-bedroom rents around $1,300. Pennsylvania exempts Social Security, pensions, and IRA/401(k) distributions for retirement-age filers.
Museums, professional sports, and walkable neighborhoods come included, along with the most usable transit of these ten cities. Winters are gray and cold. Tulsa above it is cheaper on housing and sales tax; Pittsburgh trades that for specialty medical depth that few metros at this price can match.
7Greenville, South Carolina
Greenville ranks seventh despite the highest median home price here, near $330,000, because property taxes sit near 0.5%, Social Security is untaxed, and those 65 and older get a retirement-income deduction up to $15,000. Prisma Health anchors the region, and downtown has a polished, walkable feel.
Because of the price, a single retiree or a couple without home-sale proceeds should target the lower end of the market deliberately. Pittsburgh above it offers a comparable median with stronger specialty care; Greenville counters with milder winters and a lower property tax rate.
8Springfield, Missouri
Springfield ranks eighth with a median home price near $245,000 and a cost of living about 12% below average. Missouri exempts Social Security and offers pension deductions. CoxHealth and Mercy both serve the metro, giving it two large systems rather than one.
Lakes and Ozarks outdoor recreation are the lifestyle argument; hot summers and mild-to-moderate winters are the climate reality. Greenville above it has a stronger downtown and lower property tax; Springfield counters with a lower purchase price and dual hospital systems. It suits retirees who want water access and low daily costs.
9Augusta, Georgia
Augusta ranks ninth because Georgia's retirement-income exclusion of up to $65,000 per person at 65 and older effectively erases state income tax for anyone on a $40,000 budget. The median home price sits near $250,000, and Social Security is not taxed. Augusta University Medical Center provides strong healthcare.
Winters are mild; summers are hot and humid. Springfield above it has a lower median and cheaper daily costs, but Augusta wins on tax exclusion size and specialty medical depth. The exclusion is statutory, so it can be amended by a future legislature in a way a nonexistent income tax cannot.
10Cedar Rapids, Iowa
Cedar Rapids ranks tenth with a median home price near $215,000, a well-below-average cost of living, and Iowa's recent full exemption of retirement income for those 55 and older alongside a low flat rate on other income. Mercy and UnityPoint serve the area.
Cold, snowy winters are the price of admission, and the state's tax break is the newest and least tested on this list. Augusta above it offers a larger, longer-standing exclusion and milder winters; Cedar Rapids counters with a lower purchase price. Retirees arriving with home-sale proceeds can eliminate the housing line entirely here.
How we ranked these
Each city was scored on four weighted cost layers: state income-tax treatment of retirement income (30%), median home price and typical two-bedroom rent (30%), effective property-tax rate and insurance load (25%), and healthcare depth measured by the presence of an academic or major regional hospital system (15%). Only metros where a couple could plausibly live on roughly $38,000 after-tax spendable income qualified for ranking.
Deliberately excluded: climate preference, cultural amenities, walkability scores, proximity to family, and subjective lifestyle ratings. Those matter enormously to individual retirees but cannot be scored comparably across ten cities, and they would have quietly smuggled coastal and Sun Belt bias into a list built to measure arithmetic. Also ignored were one-off relocation incentives and temporary tax credits that expire before 2027.
What to look for
Between these ten, the deciding variable is not the sticker price of the house — it is the all-in carrying cost. A $215,000 Cedar Rapids home with Iowa's retirement-income exemption can leave more monthly slack than a $190,000 Jackson home once insurance, storm risk, and specialist access are priced in. Run property tax, insurance quote, and maintenance reserve on the specific address before comparing cities.
The mistake most buyers make is purchasing on a pleasant shoulder-season visit after budgeting from gross income. They omit the 1%-of-value maintenance reserve, skip the actual insurance quote, and never confirm specialist panel availability. A twelve-month rental first costs far less than unwinding a purchase, and it surfaces the hard season, the real utility bills, and the drive times that brochures never show.
Related questions
Does no state income tax always beat a retirement-income exclusion?
No. Georgia's $65,000-per-person exclusion at 65+ produces the same zero state tax on a $40,000 budget as Tennessee's absence of an income tax, and Georgia's sales tax runs lower than Tennessee's roughly 9.55% combined rate. The real difference is durability, not arithmetic — an exclusion can be amended, a nonexistent tax cannot.
How much should a retiree budget for home maintenance?
Roughly 1% of the home's value per year, set aside whether or not anything breaks. On a $250,000 house that is about $2,500 annually. This is the line most fixed-income budgets omit entirely, and it is the one that most often forces unplanned borrowing when a roof or HVAC system fails.
Is $40,000 a year enough for a single retiree?
Generally yes, and with more slack than a couple has. Housing and utilities do not halve when you live alone, but groceries, healthcare premiums, and transportation largely do. The binding constraint shifts from total cost to whether a single Social Security benefit can carry the housing line by itself.
Should I buy or rent when I first arrive?
Rent for twelve months. A round-trip real estate transaction — closing costs, commission, moving expenses — can exceed $30,000, which is most of a year's budget destroyed by a decision made on one pleasant visit. Renting also reveals the hard season, real utility costs, and actual drive times before you commit capital.
Which of these cities has the lowest property tax?
Huntsville, Alabama, where the effective rate sits near 0.4%. On a $300,000 home that is roughly $1,200 a year. Greenville, South Carolina, is close behind at about 0.5%. Compare that to a 2% jurisdiction, where the identical house costs $6,000 annually — a $4,800 swing with no offsetting benefit.
Do I still owe federal tax on Social Security in these cities?
Possibly. Federal taxation of Social Security depends on combined income, not geography, so moving to a no-income-tax state does not eliminate it. A portion of benefits becomes taxable above certain thresholds. Build your budget from the amount that actually lands in the bank after Medicare Part B premiums and any federal withholding.
How important is hospital access compared to housing cost?
More important than most buyers admit. A major hospital nearby is necessary but not sufficient — what matters is whether the specific specialists you already see accept new Medicare patients within a reasonable drive. That question converts from theoretical to urgent without warning, and no amount of housing savings compensates for delayed care.
Will these tax exemptions still exist in 2027?
Some may change. Georgia's $65,000 exclusion, Iowa's retirement-income exemption, and South Carolina's deduction are statutory and can be amended by future legislatures. Tennessee's absence of a state income tax is structural and harder to reverse. Retirees who value certainty sometimes prefer the structural absence over a generous but revocable carve-out.
FAQ
Can a couple really retire on under $40,000 a year?
Yes, in the ten cities listed. The arithmetic works because housing, property tax, and state income tax consume a smaller share of a fixed check. A Fort Wayne couple renting near $1,050 spends roughly $12,600 on housing, leaving about $25,400 for everything else — groceries, utilities, insurance, transportation, and uncovered medical costs.
What is the single biggest expense to control?
Housing, by a wide margin. It is the largest line and the one with the widest spread across these cities — from roughly $190,000 median in Jackson to near $330,000 in Greenville. A $130,000 difference financed is several hundred dollars monthly for thirty years; paid in cash, it is capital that stays invested.
Which city on the list has the cheapest homes?
Jackson, Mississippi, where the statewide median sits near $190,000. Mississippi also exempts all retirement income, including Social Security, pensions, and 401(k) withdrawals. The trade-offs are thinner healthcare access outside the academic medical center and severe summer heat and humidity.
Which city offers the best healthcare per dollar?
Pittsburgh, Pennsylvania. Median home prices near $235,000 pair with UPMC, one of the largest health systems in the country, plus museums, professional sports, and walkable neighborhoods. Pennsylvania exempts Social Security, pensions, and IRA or 401(k) distributions for retirement-age filers. Winters are gray and cold.
How much does Medicare actually cost a retiree couple?
Budget roughly $6,000 to $9,000 annually for Part B premiums, a supplement, dental, and vision, depending on plan choice. Part B premiums are deducted directly from Social Security checks before the money arrives, so the gap between your benefit statement and your bank deposit is commonly $2,000 to $4,000 a year.
Do these cities require a car?
Mostly yes. Public transit outside downtown cores is limited — Knoxville and Fort Wayne have basic bus systems, but assume a vehicle. Set aside $150 to $250 monthly for a used-car replacement fund so a $12,000 purchase does not arrive with no funding source and force borrowing.
What is the biggest mistake retirees make when relocating?
Buying before renting, and visiting only in the good season. Every city on this list has a hard season — Knoxville in July, Cedar Rapids in January, Augusta in August. A twelve-month rental costs far less than unwinding a purchase, and it surfaces utility bills, drive times, and specialist access.
How do sales taxes affect the budget?
They run opposite to income-tax savings. Tennessee's combined state and local sales tax approaches 9.55%, so a couple spending $18,000 annually on taxable goods pays roughly $1,700. That is real money, though still less than a mid-single-digit income tax on $40,000 would extract. Sales tax is the layer you can still adjust after moving.
Should I verify state tax rules myself?
Yes. Exemption rules carry age thresholds, income phase-outs, and varying definitions of retirement income. Iowa's exemption starts at 55, South Carolina's larger deduction at 65, and Georgia's $65,000 exclusion is per person at 65 and older. Confirm your specific facts with a tax professional rather than relying on any list.
What if I cannot afford to move at all?
Staying put and cutting costs in place is a legitimate alternative. Downsizing within your current metro, appealing a property tax assessment, or dropping to one vehicle can free $500 to $900 monthly without severing a support network. Moving is the bigger lever, but it carries $5,000 to $12,000 in relocation costs most budgets omit.
Sources
- https://www.ssa.gov/benefits/retirement/planner/agereduction.html
- https://www.irs.gov/faqs/social-security-income
- https://www.medicare.gov/basics/costs/medicare-costs
- https://www.census.gov/quickfacts/fact/table/US/PST045223
- https://www.bls.gov/cex/
- https://www.hud.gov/topics/rental_assistance
- https://www.taxadmin.org/state-tax-rates
- https://www.cdc.gov/nchs/fastats/older-american-health.htm
- https://www.consumerfinance.gov/owning-a-home/
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-livingThe 10 Best Cities for Families in Florida in 2027
 pulse-living10 Best Small Towns to Retire in 2027 (Affordable, Walkable, Charming)
 pulse-livingTop 10 Safest Suburbs in the Northeast in 2027
 pulse-livingBest Walkable US Cities for Car-Free Young Professionals in 2027
 pulse-living10 Best College Towns to Live in 2027
 pulse-livingThe 10 Safest Suburbs in America for Families in 2027
 pulse-living10 Best Mountain Towns to Retire in 2027 (Scenery, Clean Air, Outdoor Life)
 pulse-livingThe 10 Best Suburbs Near New York City in 2027
 pulse-livingThe 10 Best Suburbs of Chicago for Families and Schools in 2027
 pulse-livingBest US Cities for Outdoor-Loving Remote Workers in 2027