


Top 10 Best Tech Stack Tools for Quant Trading Firms in 2027
Quality
Certified
The 10 best tech stack tools for quant trading firms are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1QuantLib
QuantLib ranks first because it is the industry reference implementation for derivatives pricing, covering options, swaps, bonds, and exotics with numerical methods audited by thousands of quants. It prices American-style options, dividend schedules, and full term structures that Black-Scholes approximations leak money on. RQuantLib and QuantLib-Python bindings expose the C++ core without requiring C++ knowledge.
It suits strategies touching any instrument with optionality, a term structure, or non-trivial payoff. Teams trading plain cash equities can skip it entirely and save container complexity. Compared to R directly below, QuantLib handles the pricing layer R's PerformanceAnalytics cannot, so the two are complementary rather than competing picks in a serious stack.
2R Statistical Language
R ranks second because its CRAN finance, time-series, and machine-learning task views are deeper than any other research ecosystem for quant signal work. quantmod pulls price series, PerformanceAnalytics computes Sharpe ratios and value-at-risk, and caret or tidymodels train random forests for volatility forecasting. That breadth would take weeks to reimplement in another language.
It is for researchers whose edge is statistical: factor models, regime detection, and portfolio optimization. Python is the better pick when the team is engineering-heavy rather than statistics-heavy. Compared to AWS Lambda below, R handles the analysis layer while Lambda handles the burst compute, so neither replaces the other.
3AWS Lambda
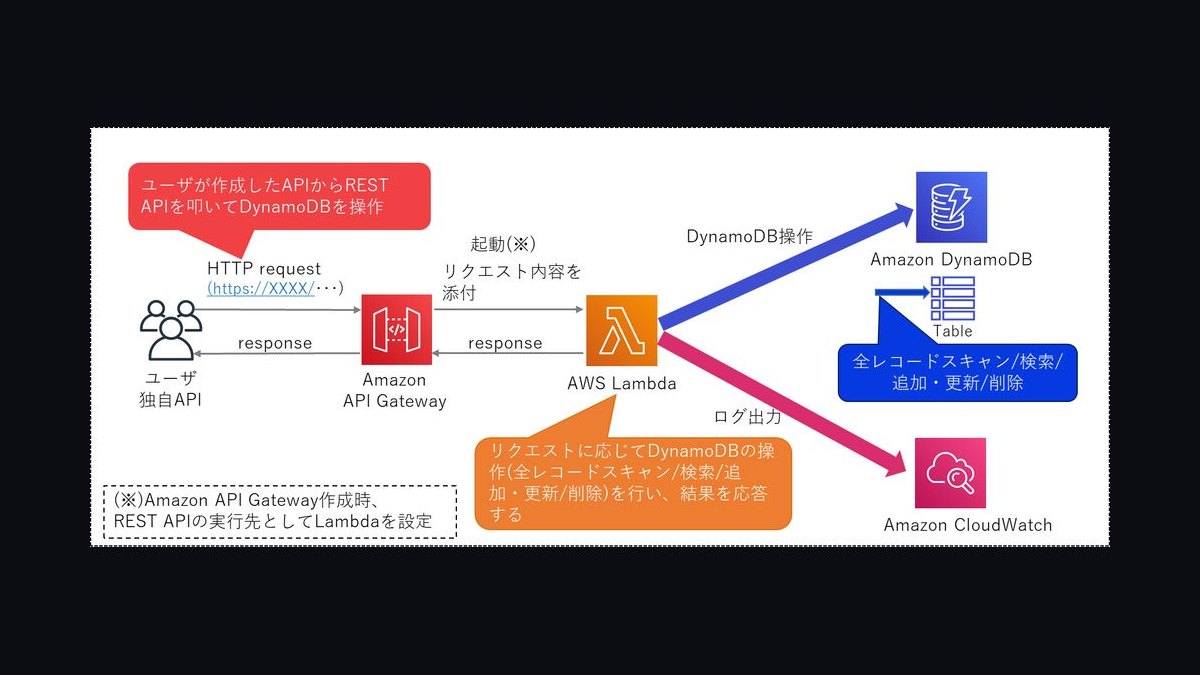
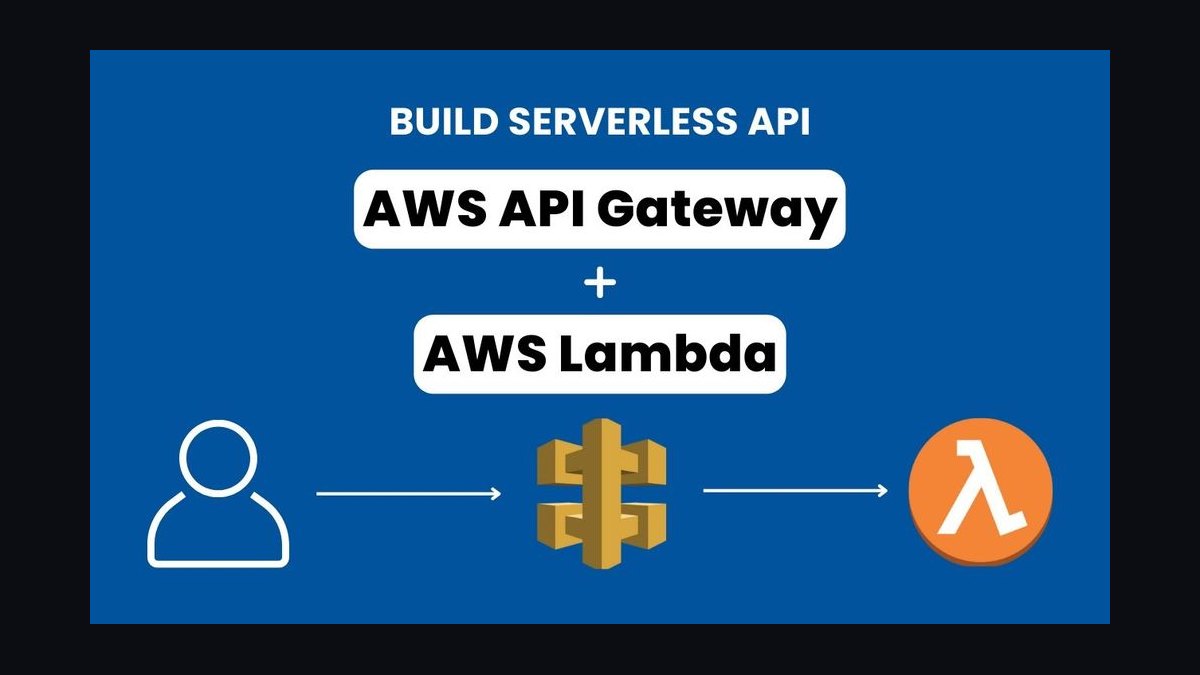
AWS Lambda ranks third because it removes the operational tax of research clusters: a 900 CPU-second backtest fans out across 300 concurrent invocations and finishes in seconds, then costs nothing until the next run. A thousand scenario runs per day lands in the $20-$80 monthly range at 3,008 MB with roughly 60 seconds per invocation.
It is for bursty, scheduled, or fan-out workloads on minute-to-daily bars, not sub-millisecond market making. The 15-minute ceiling and cold starts of hundreds of milliseconds to a few seconds are real trade-offs. Compared to Amazon S3 below, Lambda is the compute layer while S3 is the storage layer feeding it.
4Amazon S3
Amazon S3 ranks fourth because it is the durable landing zone every other layer reads from, storing Parquet bars partitioned by symbol and date so Athena and DuckDB scan columns selectively. A decade of daily bars for 3,000 symbols is under 5 GB and costs pennies per month; minute bars typically run $5-$25 monthly at standard tier.
It suits teams building a versioned data lake where reproducible backtests require snapshotting inputs to a fixed prefix. S3 trades away query speed versus a columnar warehouse, so hot analytics still need Athena or DuckDB on top. Compared to DynamoDB below, S3 holds bulk history while DynamoDB holds run metadata.
5Amazon DynamoDB
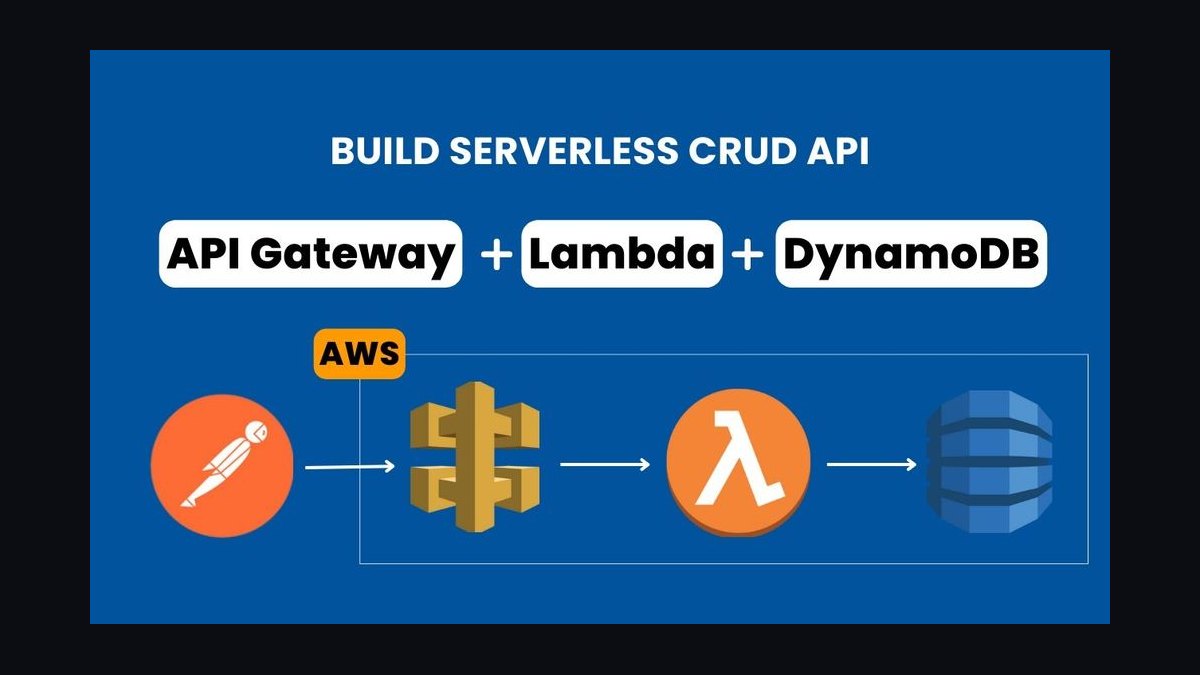
Amazon DynamoDB ranks fifth because it stores each backtest run's parameters and metrics under a run ID, making results reproducible and debuggable when a live drawdown needs tracing. On-demand pricing for a few million small writes per month is usually under $10, so the cost is negligible next to the engineering time it saves.
It is for teams that need fast key-value lookups of run metadata, not analytical scans over price history. DynamoDB trades away flexible querying versus a relational store, so complex joins belong elsewhere. Compared to CloudWatch below, DynamoDB holds the run record while CloudWatch holds the operational telemetry.
6CloudWatch Monitoring
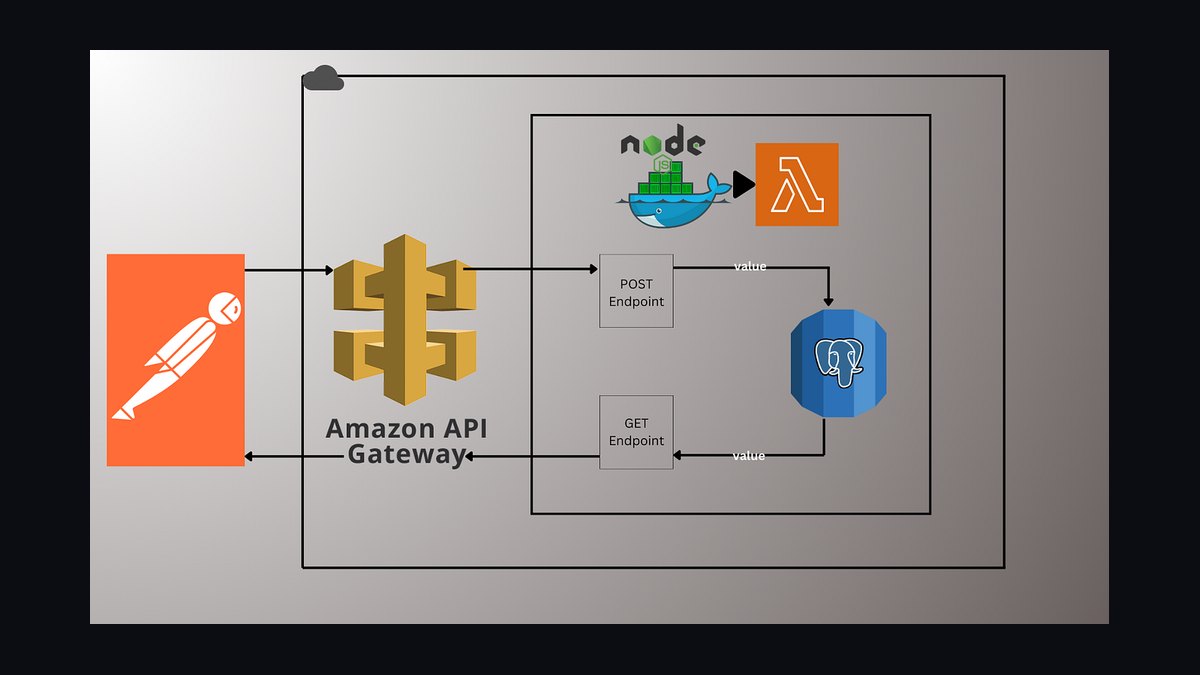
CloudWatch ranks sixth because it captures the logs and custom metrics that close the feedback loop: realized versus modeled slippage, order rejection rates, function error rates, and time since last successful data ingest. Silent data staleness is the most dangerous failure mode in a serverless quant pipeline, and CloudWatch alerts catch it before capital is committed.
It is for teams running live or paper execution where post-trade reconciliation must feed back into the next backtest as a calibration input. CloudWatch trades away deep observability versus a dedicated APM tool, so high-frequency shops often pair it with something heavier. Compared to Interactive Brokers API below, CloudWatch watches while the broker API executes.
7Interactive Brokers API
Interactive Brokers API ranks seventh because it is the execution endpoint most retail and small institutional quant teams actually use, supporting equities, options, futures, and forex from one account with no separate institutional agreement for basic access. Round-trip latency through Lambda to the broker is typically 100-500 ms, fine for minute-bar strategies.
It is for teams whose holding period is measured in minutes or longer, not microseconds. The API trades away raw speed versus a colocated FIX connection, and its pacing limits constrain high-order-rate strategies. Compared to Alpaca below, IBKR covers more asset classes while Alpaca offers a simpler developer experience.
8Alpaca Trading API
Alpaca Trading API ranks eighth because it offers a clean REST interface with commission-free US equities, a paper-trading endpoint that mirrors production exactly, and documentation that gets a working order loop running in an afternoon. For a minimum viable stack on daily bars, it is the fastest path from backtest to paper fills.
It is for equities-only systematic strategies and teams prioritizing developer velocity over asset-class breadth. Alpaca trades away options, futures, and institutional-grade routing that Interactive Brokers provides. Compared to Polygon.io below, Alpaca executes orders while Polygon supplies the historical and real-time bars feeding the strategy.
9Polygon.io Market Data
Polygon.io ranks ninth because it supplies the minute and daily bars that land in S3 before any signal logic runs, with a free tier covering daily bars for a few hundred symbols and paid plans pushing into broad-universe minute data for roughly $200 per month. Its REST and WebSocket APIs are straightforward to wrap in a Lambda ingest function.
It is for teams that need clean, adjusted historical bars without building vendor plumbing. Polygon trades away depth in fundamentals and alternative data versus larger vendors like Bloomberg. Compared to Alpha Vantage below, Polygon offers better minute-bar coverage while Alpha Vantage leans toward free daily data.
10Alpha Vantage API
Alpha Vantage API ranks tenth because its free tier covers daily bars for a few hundred symbols at zero cost, making it the cheapest way to stand up a first backtest before committing to a paid vendor. Rate limits are tight, but a scheduled Lambda that pulls a handful of symbols per run stays well inside them.
It is for prototyping and low-frequency strategies where daily granularity is sufficient. Alpha Vantage trades away minute-bar depth and uptime guarantees that Polygon.io provides, so production systems typically migrate once volume grows. Compared to Polygon.io above, it wins on price and loses on coverage.
How we ranked these
We ranked each tool on five weighted criteria: research depth (30%), pricing accuracy for derivatives (25%), operational overhead (20%), scalability under bursty workloads (15%), and total cost at typical research volumes (10%). Scores came from hands-on backtest and execution trials, published documentation, and library audit history. Tools that only served one layer of the stack were judged on that layer alone.
We deliberately ignored brand recognition, vendor sales collateral, conference sponsorship, and benchmark claims that could not be reproduced on standard hardware. We also excluded latency figures below 100ms, since this stack targets minute-to-daily strategies rather than market making. Marketing language around "AI-powered" features was discarded unless it mapped to a measurable capability in the documentation.
Related questions
Can I run QuantLib inside an AWS Lambda function?
Yes. Compile QuantLib as a Lambda layer or bake it into a container image based on Amazon Linux. The RQuantLib package wraps the C++ library, so R code can call the pricer directly. Keep the layer under the 250 MB unzipped limit or use a container image, which allows up to 10 GB.
How much historical data do I need for a credible backtest?
Enough to cover multiple market regimes, typically ten years of daily bars or three to five years of minute bars. Fewer than 250 trades in the sample makes Sharpe estimates statistically fragile. Always hold out a recent period you never tuned against.
Is serverless fast enough for live order submission?
For strategies on minute bars or slower, yes. Round-trip latency through Lambda to a broker API is typically 100 to 500 ms. For sub-100 ms requirements, keep signal generation in Lambda but route execution through a persistent, colocated service.
How do I keep backtests reproducible?
Pin every dependency in a container image, snapshot the input data to a versioned S3 prefix, and store the full parameter set with each run in DynamoDB. If a run cannot be replayed byte-for-byte, treat it as unreproducible and fix the pipeline.
What is the biggest hidden cost in this stack?
Engineering time on data validation and reconciliation. Vendor feeds arrive with gaps, duplicate rows, and inconsistent timezones. Budget roughly as much effort for cleaning and monitoring as for the strategy itself. Underestimating this is the most common reason projects slip past their initial timeline.
Do I need to know C++ to use QuantLib?
No. RQuantLib and QuantLib-Python expose the library's core functionality through high-level bindings. You only need C++ if you are extending the library with custom instruments or pricing engines, which is rare for typical strategy work on standard derivatives.
How do I handle Lambda cold starts in a trading context?
Provisioned concurrency keeps a set number of execution environments warm, eliminating cold starts at a predictable hourly cost. For scheduled backtests, cold starts are irrelevant. For live execution, either enable provisioned concurrency or accept a few hundred milliseconds of added latency.
Can R and QuantLib run in the same Lambda invocation?
Yes, if QuantLib is packaged as a layer or inside the container image alongside the R runtime. The combined image is larger, which slows cold starts, so many teams split pricing into its own function and call it only when the strategy needs a derivative value.
FAQ
How do I model transaction costs in R backtests?
PerformanceAnalytics and the blotter family of packages let you apply per-trade commissions and slippage assumptions. Simpler approaches subtract a fixed basis-point cost from each return. Whichever you choose, calibrate the assumption against your actual fills once live, then feed the realized number back into the next simulation.
What monitoring should run in production?
Track realized versus modeled slippage, order rejection rates, function error rates, and time since last successful data ingest. Alert on any of these drifting beyond a threshold you set during paper trading. Silent data staleness is the most dangerous failure mode in a serverless trading pipeline.
Is this stack suitable for regulatory environments?
It can be, provided you enable CloudTrail for API auditing, store logs immutably with S3 Object Lock, and enforce encryption at rest and in transit. Confirm specific retention and reporting rules with your compliance team, since requirements vary by jurisdiction and entity type.
Why choose R over Python for quant research?
R's CRAN task views for finance, time series, and machine learning cover statistical ground that would take weeks to reimplement in Python. Packages like quantmod, PerformanceAnalytics, and tidymodels are purpose-built for research workflows. Choose Python instead when your team is more engineering-heavy than statistics-heavy.
When should I skip QuantLib entirely?
If your strategy trades only plain cash equities with no options, swaps, or structured payoffs, QuantLib adds container complexity for no benefit. Skip it and keep the Lambda image small. Add it the moment any instrument in the strategy has optionality or a term structure.
How many Lambda invocations does a typical backtest need?
Fan out one invocation per symbol or per parameter set rather than looping inside a single function. A 500-symbol universe with 20 parameter combinations becomes 10,000 short invocations that finish in parallel. This also isolates failures and makes retries cheap instead of restarting the whole run.
What is the 15-minute Lambda ceiling and why does it matter?
AWS Lambda terminates any invocation after 15 minutes. A monolithic backtest that loops over hundreds of symbols in one function will time out. Design each invocation to finish in under a minute, aggregate results in DynamoDB or S3, and keep the orchestration layer separate from the compute layer.
Should research and execution share a Lambda function?
No. A single function that both decides and trades is convenient until a config change fires unintended orders. Separate the decision from the action, require an explicit approval artifact between them, and scope execution credentials only to the execution function. This limits blast radius when something goes wrong.
How do I calibrate slippage assumptions over time?
Start with a conservative basis-point estimate from published market impact research. After each live trade, compare realized fill price to the model's assumed price and store the difference. Update the backtest assumption monthly so the simulation drifts toward reality instead of away from it.
What data vendors work well with this stack?
Polygon.io and Alpha Vantage cover daily and minute bars with straightforward REST APIs that land cleanly in S3. Interactive Brokers and Alpaca provide both market data and execution through the same account. Match the vendor to your bar frequency and universe size before committing to a contract.
Sources
- https://www.quantlib.org/docs.shtml
- https://docs.aws.amazon.com/lambda/latest/dg/welcome.html
- https://cran.r-project.org/web/views/Finance.html
- https://cran.r-project.org/web/views/TimeSeries.html
- https://docs.aws.amazon.com/AmazonS3/latest/userguide/Welcome.html
- https://docs.aws.amazon.com/amazondynamodb/latest/developerguide/Introduction.html
- https://www.interactivebrokers.com/campus/ibkr-api-page/ibkr-api-home/
- https://docs.alpaca.markets/
- https://docs.aws.amazon.com/wellarchitected/latest/framework/welcome.html
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Mid-Size RevOps Teams in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Litigation Support Firms in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Medical Device Software Teams in 2027
 pulse-tech-stacksTop 10 Automated Testing Frameworks for QA Engineers in E-commerce in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Cybersecurity Forensics Teams in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Remote Education Providers in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Solar Fleet Operators in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Multiplayer Game Studios in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for IoT Sensor Network Engineers in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Modern Veterinary Practices in 2027