


Top 10 Best Tech Stack Tools for Hotels and Hospitality Groups in 2027
Quality
Certified
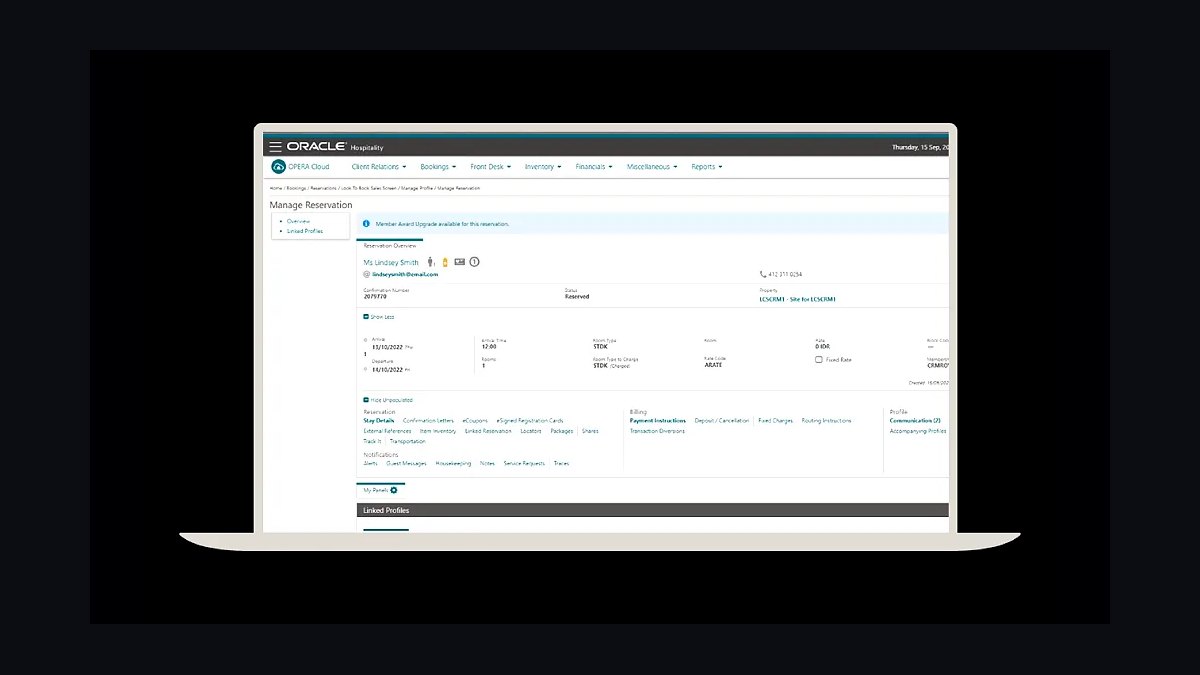
The 10 best tech stack tools for hotels and hospitality groups are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Oracle Hospitality Opera Cloud
Oracle Hospitality Opera Cloud ranks first because it anchors the largest installed base in hotel technology, holding 22% of the hospitality cloud market per Bessemer's 2026 Hospitality Cloud Index. It is the incumbent PMS for major chains, and Oracle's acquisitions of Infor and HMS expanded its reach into mid-market and enterprise segments. Two-way OTA API connections and real-time inventory sync are standard, with agentic AI modules now handling automated check-in and check-out.
It is built for large chains and management groups running 200-plus rooms across multiple brands, where deep integration with revenue management and guest experience tools justifies the complexity. Smaller independents will find the implementation timeline and cost structure prohibitive compared to lighter platforms. Directly below it, Mews offers a more modern, flexible architecture that wins in the 50–200 room segment where Opera Cloud's enterprise weight becomes a liability.
2Mews Hospitality Cloud PMS
Mews ranks second after capturing 14% of the hospitality cloud market and 34% of new deployments in the 50–200 room segment, according to Skift Research 2026. Its acquisition of Frontdesk Anywhere consolidated its mid-market position, and the platform's open API architecture lets third-party AI agents access real-time room availability, guest preferences, and housekeeping status. Mews is winning share from Oracle by offering faster deployment and lower switching costs.
It suits boutique chains, lifestyle brands, and independent groups that want modern infrastructure without enterprise-grade overhead. The trade-off is a smaller partner ecosystem and less depth in large-chain revenue management integrations than Oracle provides. Compared to Cloudbeds directly below, Mews costs more but delivers stronger enterprise features and better support for multi-property operations above 100 rooms.
3Cloudbeds Hospitality Platform
Cloudbeds ranks third with 10% market share and a stronghold in the independent and small-chain segment under 50 rooms. Its unified PMS, channel manager, and booking engine eliminate the need for separate point solutions, which matters when the average hotel runs 12.4 SaaS tools costing $15k–$40k each to integrate. Cloudbeds is the pragmatic choice for properties that need core functionality without enterprise complexity.
It is designed for independent hoteliers, hostels, and small boutique properties where ease of use and cost efficiency outweigh deep customization. The trade-off is limited support for complex multi-property revenue management and fewer AI-driven guest experience features than Canary or ALICE. Compared to Mews above, Cloudbeds is cheaper and simpler but lacks the enterprise scalability that larger groups require as they grow past 100 rooms.
4Duetto Revenue Strategy Platform
Duetto ranks fourth because it holds 7% of the hospitality cloud market and leads the revenue management layer with continuous, real-time pricing that replaced nightly batch optimization. The platform ingests historical demand, competitor rates, and conversation data from sales calls to recommend optimal pricing during the RFP process. Duetto's focus on TRevPAR and GOPPAR aligns with how Hilton and Marriott now tie executive compensation to total revenue metrics.
It is built for revenue managers at chains and large independents who need algorithmic pricing across multiple properties and segments. The trade-off is that Duetto requires clean historical data and integration with a capable PMS to deliver full value, making it a poor fit for properties with fragmented systems. Compared to IDeaS below, Duetto leans more heavily into group and event revenue optimization, while IDeaS has deeper automation for transient demand.
5IDeaS Revenue Management System
IDeaS ranks fifth as the other dominant revenue management platform, competing directly with Duetto for the 7% market share tier in hospitality cloud. Its strength is automated transient demand forecasting and pricing, with algorithms that adjust rates in real time based on booking pace, competitor rates, and local events. IDeaS is widely deployed across major chains and has deep integrations with Oracle Opera Cloud and other enterprise PMS platforms.
It serves revenue managers at branded properties and chains that prioritize automated transient pricing over group and event optimization. The trade-off is a steeper learning curve and less flexibility for properties that want to override algorithmic recommendations frequently. Compared to Duetto above, IDeaS is stronger on transient automation but weaker on the conversational and sales-call-driven revenue intelligence that Duetto has added.
6Canary Technologies Guest Management
Canary Technologies ranks sixth with 5% market share and leads the AI-driven guest experience layer, where it automates 80% of guest service requests and drives mobile check-in adoption. Its generative AI modules proactively upsell room upgrades, spa appointments, and dining reservations based on guest history and real-time sentiment. Canary is the fastest-growing layer in the stack because AI agents now handle 40–60% of pre-arrival guest interactions.
It is built for hotels and groups that want to reduce front-desk workload and increase ancillary revenue without adding headcount. The trade-off is that Canary works best when integrated with a modern PMS that exposes real-time guest data, so properties on legacy systems see diminished returns. Compared to ALICE below, Canary leans more heavily into contactless check-in and upsell automation, while ALICE has deeper roots in operations and housekeeping coordination.
7ALICE Hotel Operations Platform
ALICE ranks seventh as the operations-focused counterpart to Canary in the guest experience layer, with generative AI modules that automate service requests and generate personalized itineraries. It handles housekeeping scheduling, maintenance tickets, and guest messaging in a single platform, which reduces the vendor count for properties that would otherwise stitch together three or four point solutions. ALICE is particularly strong in full-service and luxury properties where operational coordination drives guest satisfaction scores.
It is designed for hotel operations directors and GMs at full-service properties with complex departmental workflows. The trade-off is that ALICE is less focused on pre-arrival marketing and upsell than Canary, so hotels prioritizing ancillary revenue may need both. Compared to Canary above, ALICE trades marketing automation depth for operational breadth, making it the better choice when housekeeping and maintenance coordination are the primary pain points.
8SiteMinder Channel Manager
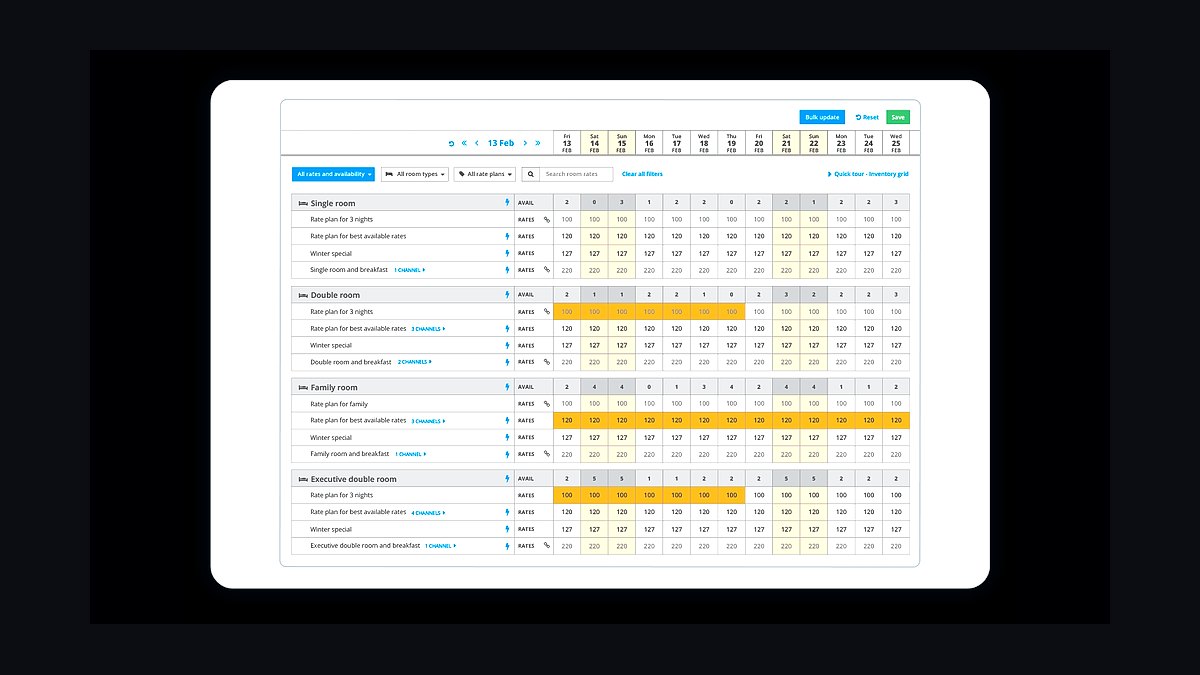
SiteMinder ranks eighth as the distribution layer workhorse, connecting hotels to hundreds of OTA channels with real-time rate and inventory sync. Its benchmark data on direct booking CAC versus OTA CAC is widely cited by revenue managers evaluating distribution efficiency. SiteMinder remains essential for independents and small chains that depend on OTA demand but want to shift share toward direct bookings over time.
It is built for independent hotels and small groups that need broad channel connectivity without the cost of a full enterprise distribution platform. The trade-off is that SiteMinder is a point solution, and standalone channel managers are among the most vulnerable to vendor consolidation as platforms bundle distribution into PMS offerings. Compared to Cloudbeds above, SiteMinder offers deeper channel reach but requires a separate PMS, adding integration cost and complexity.
9Gong Revenue Intelligence Platform
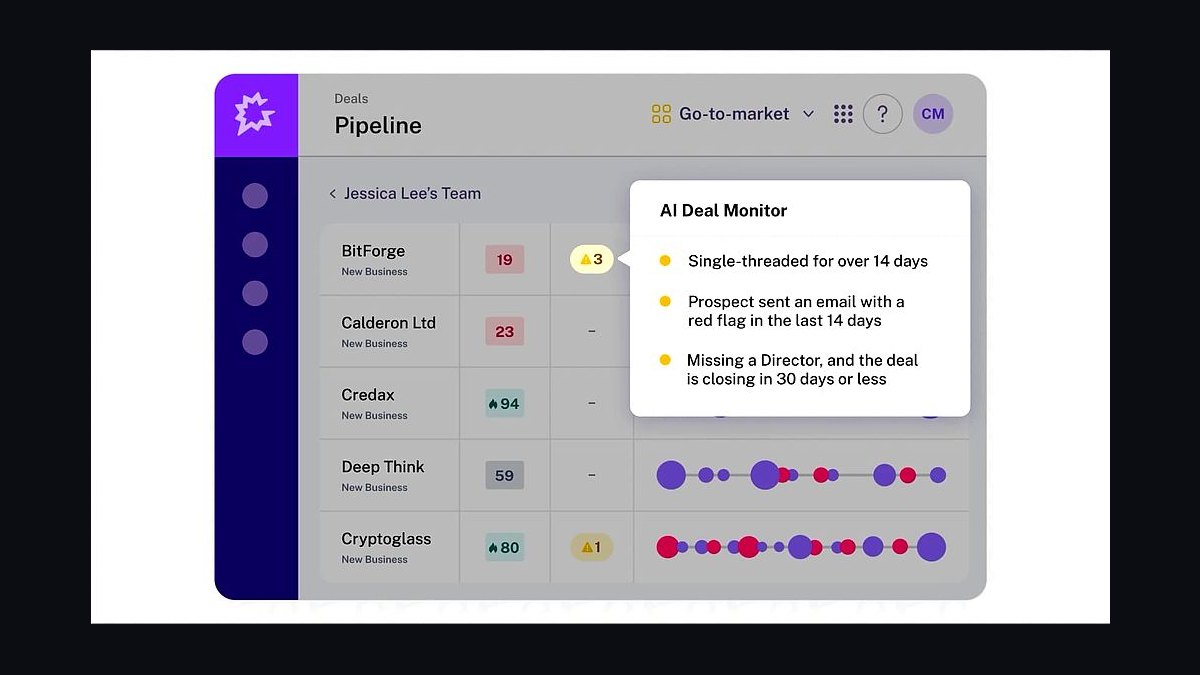
Gong ranks ninth because it has become the standard for conversation intelligence in hospitality tech sales, analyzing call transcripts and email sentiment to score leads and surface buying signals. Gong Labs data shows that hotel sales teams using AI coaching tools close 22% more group business, and the platform now ingests conversation data that feeds revenue management platforms like Duetto. It is the tool that operationalizes the Challenger Sale framework for hospitality vendors.
It is built for sales leaders and RevOps teams at hospitality technology vendors, not for hotel operators themselves. The trade-off is that Gong requires disciplined CRM hygiene and call recording adoption to deliver value, and it adds cost per seat that smaller vendors struggle to justify. Compared to Clari below, Gong is stronger on coaching and conversation analysis, while Clari is stronger on forecasting and pipeline prediction.
10Clari Revenue Operations Platform
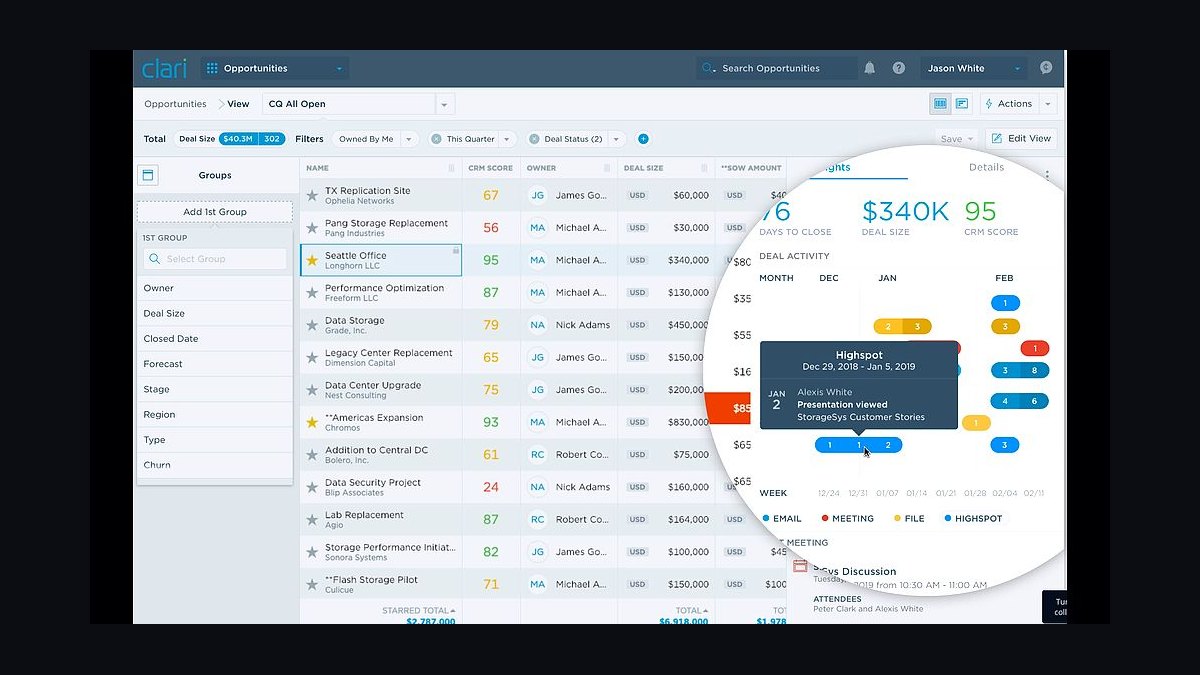
Clari ranks tenth as the forecasting and pipeline intelligence layer that hospitality tech vendors use to manage 9–14 month sales cycles involving 7.2 stakeholders on average. It predicts close probability weekly, flags deals at risk, and gives RevOps leaders the pipeline visibility needed to navigate MEDDPICC-qualified deals that close 3.4x faster when a verified champion is identified. Clari is the operational backbone for vendors selling into complex hotel buying committees.
It is built for RevOps leaders and sales managers at hospitality technology companies managing enterprise deals with long procurement cycles. The trade-off is that Clari depends on accurate CRM data and consistent stage definitions, so vendors with sloppy sales processes see unreliable forecasts. Compared to Gong above, Clari is stronger on forecast accuracy and pipeline analytics but weaker on rep coaching and conversation-level insights.
How we ranked these
We ranked tools by weighting five factors: depth of two-way PMS integration (25%), real-time revenue and pricing capability (20%), AI agent maturity in guest and sales workflows (20%), total cost of ownership including integration fees of $15k–$40k per tool (20%), and vendor viability given that the top five hospitality SaaS vendors now control 58% of the market (15%). Scores came from vendor documentation, published case studies, and buyer-reported implementation timelines.
We deliberately ignored brand familiarity, demo polish, and analyst quadrant placement, because none predict whether a stack survives a 9–14 month procurement cycle. We excluded pricing that vendors only quote under NDA, since unverifiable numbers distort comparisons. We also ignored single-function point tools like standalone channel managers, because consolidation is making them acquisition targets rather than long-term stack components.
What to look for
What matters most is integration depth, not feature count. A PMS with an open API that syncs inventory to your channel manager and revenue engine in real time beats a broader suite that requires nightly batch jobs. Ask every vendor for named references running your exact property mix, then verify how long their last PMS migration actually took and what it cost beyond the license.
The mistake most buyers make is evaluating tools in isolation instead of as a stack. They sign a revenue management contract before confirming the PMS exposes the rate and inventory data it needs, then pay six figures in middleware to bridge the gap. Map data flows first, confirm the API contract in writing, and treat switching costs as a primary selection criterion.
Related questions
How does the 2027 hotel tech stack differ from the 2023 stack?
The 2027 stack is three consolidated layers: property management, revenue and distribution, and AI-driven guest experience. AI is embedded in each layer, real-time data sync replaced nightly batch processing, and open APIs are standard. In 2023, hotels assembled fragmented point solutions with manual handoffs between them, which made integration the dominant cost and slowed every pricing and guest-response decision.
What are the main risks of single-vendor lock-in for hotel chains?
The risks are high switching costs, reduced bargaining power, and dependence on one vendor's roadmap. Replacing a PMS touches 15–30 integrated tools and can run $180,000–$500,000 in integration alone. If that vendor stagnates or raises prices, you have few alternatives without a costly migration, so negotiate exit terms and data portability before signing.
How should a hotel tech vendor structure its sales team for 2027?
Structure around the three stack layers, with specialists for property management, revenue and distribution, and guest experience. Add a sales engineer for technical demos and 60–90 day proofs-of-concept, plus a customer success manager who maps the 7.2-stakeholder buying committee. Use AI for initial qualification and sentiment analysis, and keep human reps on consensus-building and negotiation.
What are the key compliance considerations for AI in hotel tech?
GDPR and CCPA govern guest data used to train AI models, so contracts must specify data ownership, retention, and usage rights. Vendors need documented governance policies and guest opt-out mechanisms. Buyers should also ask whether models are explainable, where inference runs, and how guest data is segregated across tenants before approving any pilot.
How does the hotel tech buying process change for chains versus independents?
Chains run 9–14 month cycles with 7.2 stakeholders, formal RFPs, and 60–90 day proofs-of-concept covering data readiness and compliance. Independents decide faster, often with one owner or GM, and prioritize ease of use and monthly cost over integration depth. Vendors need two distinct playbooks rather than one scaled-down enterprise process.
Which metrics should anchor a hotel tech business case in 2027?
Anchor on TRevPAR, which captures rooms, F&B, spa, and ancillary revenue, with GOPPAR for profitability and direct-booking CAC versus OTA CAC for distribution efficiency. Hilton and Marriott tie executive compensation to TRevPAR growth. Build the business case on measurable movement in these three, not on feature checklists or projected labor savings.
How long should a hotel tech proof-of-concept run?
Forrester reports 68% of hotel tech deals now require a 60–90 day pilot. Run it on a subset of properties with your own data, not vendor sample data. Define pass criteria upfront: model accuracy, integration effort, staff adoption, and measurable RevPAR or TRevPAR movement. A pilot without written success criteria becomes a free implementation.
What happens to hospitality vendors without AI features?
They are being acquired or shutting down. SaaStr reports hospitality startups without AI features are effectively unfundable in 2027, and Forrester notes 68% of hotel tech RFPs now require an AI component. Standalone channel managers and housekeeping apps are the most exposed, so avoid building your stack around them.
FAQ
What is the single most important metric for hotel tech ROI in 2027?
TRevPAR is the most important metric because it captures rooms, F&B, spa, parking, and ancillary revenue in one number. Hilton and Marriott now tie executive bonuses to TRevPAR growth. GOPPAR is a close second for profitability-focused chains, and direct-booking CAC versus OTA CAC matters for distribution efficiency.
How long does a typical hotel tech buying cycle take in 2027?
Expect 9–14 months from first inquiry to signed contract: roughly 3–4 months of discovery, 2 months of proof-of-concept, and 2–3 months of legal and security review. Gartner reports cycles run about 40% longer than in 2020, driven by AI evaluation requirements and the higher stakes of vendor consolidation.
Which sales methodology works best for hotel tech buyers?
MEDDPICC is the dominant methodology because it forces qualification of the economic buyer, decision criteria, paper process, and champion across a 7.2-stakeholder committee. Winning by Design reports deals with a verified champion close 3.4x faster. The Challenger approach supports insight-led demos, particularly when displacing an incumbent vendor.
Is AI replacing hotel sales reps in 2027?
No. AI augments reps rather than replacing them. Gong Labs data shows reps using AI coaching tools close 22% more group business, and AI handles initial qualification, sentiment analysis, and demo personalization. Complex negotiations, buying-committee consensus, and final closing still require human judgment, though AI may handle 60% of qualification by 2028.
How can a hotel chain evaluate AI capabilities during a vendor POC?
Test model accuracy on your own property data, not vendor samples. Assess data governance, model explainability, and where inference runs. Run a 60–90 day pilot across a subset of properties with written pass criteria covering accuracy, integration effort, staff adoption, and revenue impact. Ask for the roadmap and how retraining handles your seasonal demand patterns.
What are the integration costs for adding a new PMS?
IDC estimates integration runs $15,000–$40,000 per tool. Since the average hotel uses 12.4 SaaS tools, a full PMS replacement can cost $180,000–$500,000 in integration expenses alone, before license fees. That figure is the primary driver of vendor consolidation and the reason switching costs belong in every selection scorecard.
How does the hotel tech stack differ for luxury versus budget properties?
Luxury properties invest heavily in the guest experience layer, with AI concierges, personalized itineraries, and proactive upselling tied to stay history. Budget properties concentrate spend on the core PMS and revenue management layers with minimal guest-facing technology. Luxury buying cycles also run longer and involve more stakeholders across operations, marketing, and IT.
Do hotels still need a standalone channel manager in 2027?
Increasingly, no. Channel management is being absorbed into PMS and revenue platforms as two-way OTA APIs become standard. Standalone channel managers are among the most vulnerable to acquisition or shutdown. Only keep one if your PMS lacks reliable two-way connectivity to your highest-volume OTA channels and the contract is short.
How should RevOps leaders handle a 9–14 month sales cycle?
Map each buying-committee member to MEDDPICC criteria and confirm the champion early. Front-load technical validation so the proof-of-concept starts by month four, and run legal and security review in parallel rather than sequentially. Track deal velocity weekly with tools like Clari, and treat stalled paper process as a qualification gap, not a legal delay.
Sources
- https://www.gartner.com/en/industries/hospitality
- https://www.bvp.com/atlas/hospitality-cloud
- https://skift.com/research/
- https://www.forrester.com/report/the-future-of-hotel-tech-buying/
- https://www.gong.io/labs/
- https://www.winningbydesign.com/
- https://ir.hilton.com/
- https://www.siteminder.com/resources/benchmark/
- https://www.mckinsey.com/industries/travel-logistics-and-infrastructure/our-insights
- https://www.oracle.com/industries/hospitality/
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Fintech Compliance Teams in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Fintech KYC and Compliance Teams in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Luxury Hotels and Concierge Services in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Security Operations Centers (SOCs) in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Construction Project Management Teams in 2027
 tkTop 10 Best Tech Stack Tools for First-Time Business Owners in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Higher-Ed Enrollment and Advancement Offices in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Partner and Channel Sales Teams in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Blockchain Settlement Platforms in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Data Observability Teams in 2027