


Top 10 Best Tech Stack Tools for Self Storage Facilities in 2027
Quality
Certified
The 10 best tech stack tools for self storage facilities are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Storable storEDGE
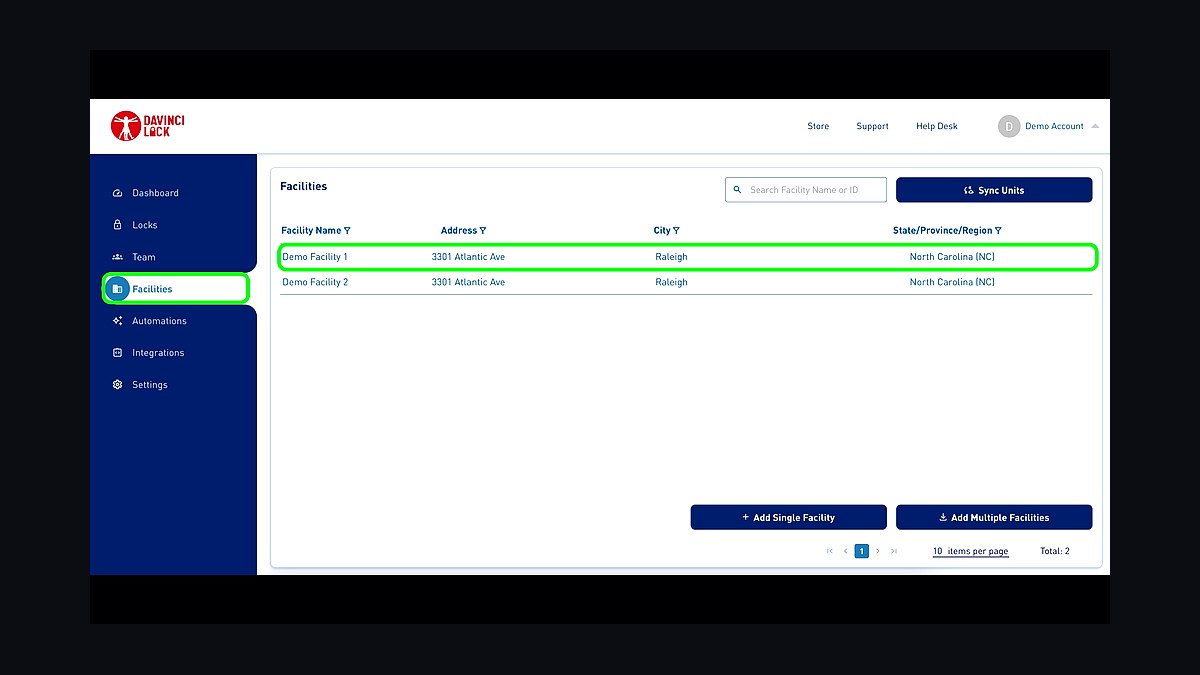
storEDGE ranks first because it puts the entire rental lifecycle under one vendor, from the tenant-facing website through online rentals, billing, payment processing, tenant protection, and a call center. Storable owns every handoff, so an online rental becomes a billed tenant with gate access without an integration seam. Pricing typically scales with unit count or as a percentage of collections rather than flat per-seat fees.
It suits multi-site operators who value a single accountable vendor over best-of-breed flexibility, and who expect to run unattended. The trade-off is coupling: Storable's economics come from the bundle, so swapping a payment processor or insurance program later means the parts were priced as a system. SiteLink, ranked second, offers the opposite bargain — more integration breadth, but you own the seams.
2SiteLink
SiteLink ranks second because it is the industry's integration hub, connecting access control vendors, call centers, listing sites, insurance providers, and revenue management tools through a broad third-party marketplace. Multi-site operators who want to run PTI at one property, a different access vendor at another, and a third-party revenue overlay generally find it the path of least resistance.
It fits operators willing to act as their own systems integrator, since nobody owns the seams between five vendors — when a gate stops syncing lockout status on a Friday evening, you triangulate between two support desks. Compared with storEDGE above it, SiteLink trades bundle convenience for flexibility; compared with Easy Storage Solutions below, it trades simplicity for portfolio-scale reporting.
3Easy Storage Solutions
Easy Storage Solutions ranks third because it delivers the core automation single-facility owners actually need — online rentals, autopay, and basic delinquency automation — without enterprise implementation weight. For a 300–600 unit facility, the facility management platform including website and online rental capability typically runs roughly $100–$400 monthly, priced per unit or as a percentage of collections.
It is built for rural and secondary-market owners running one facility as a semi-passive asset, and it trades away sophisticated revenue management, complex multi-property reporting, and the long tail of integrations. An owner planning to acquire three more facilities within four years will likely revisit this choice. SiteLink above it wins on integration breadth; Tenant Inc below it wins on modern unattended-first UX.
4Tenant Inc Hummingbird
Tenant Inc's Hummingbird ranks fourth as the leading cloud-native entrant, positioning on modern UX, unattended operations, and lower switching friction for operators building automation-first from day one. It is a legitimate 2027 option, particularly where a facility wants self-service rental, payment, and gate code issuance to work completely without staff intervention at 11pm on a Sunday.
The caution is not quality but depth: incumbents accumulated decades of edge-case handling around lien processing, state-specific auction requirements, and delinquency law. Evaluate Hummingbird specifically on those unglamorous compliance workflows rather than dashboard screenshots. It sits below Easy Storage Solutions on proven operational depth and above PTI on access-control specialization.
5PTI Security Systems
PTI Security Systems ranks fifth because access control is the mechanism that makes storage collections automatable, and PTI is the established hardware and integration name for gate controllers and keypads. The core behavior it enables: a tenant who goes delinquent past your threshold loses gate access automatically and regains it the moment payment posts, with no staff action in either direction.
Gate controllers, keypads, and wiring are a project-scale capital expense measured in thousands to tens of thousands depending on access points and whether you retrofit or build new. It is for operators who understand the unlock-on-payment path fails more often than lockout and must be tested in both directions. Noke below it adds per-door control at a materially higher cost.
6Noke Smart Entry
Noke Smart Entry ranks sixth because it extends automation from the gate to the individual unit door, priced per door, which means converting a 500-unit facility to smart entry is a materially larger investment than adding a controlled gate. It improves the unattended move-in experience by letting a new tenant access a specific unit immediately after signing and paying online.
Most operators stage it: controlled gate first because it delivers the highest automation return per dollar, then smart locks on a subset of units or a new phase, then broader rollout if the operational math justifies it. It sits below PTI because gate-level lockout captures most of the collections value. It ranks above call center services because hardware integration is the harder dependency.
7Storable Call Center
Storable's call center ranks seventh because phone leads in storage convert well and decay fast, and a staffed answering layer captures rentals during evenings and weekends when nobody is on site. It can complete a reservation or rental live and logs the lead into a tracked pipeline rather than a voicemail box.
Third-party call center services are typically priced per call or per lead rather than flat, so cost scales with marketing spend — a detail that surprises operators who model it as a fixed monthly line. It fits multi-site operators already inside the Storable ecosystem, where the handoff into storEDGE billing is seamless. SiteLink above it integrates comparable outside call centers instead of owning one.
8storEDGE Website Builder
storEDGE's website and online rental module ranks eighth because in 2027 the facility's own site is the rental counter, not a brochure. Real-time unit availability, pricing, lease signing, payment, and gate code issuance all happen inside the platform's rental flow, which is where the conversion value lives.
Building the site separately and handing off to a platform rental page adds a seam without adding much, so most operators should keep it inside the platform and invest custom effort in local SEO and conversion instead. It is for operators paying marketplace commissions for demand they could convert directly. It ranks below the call center because the site handles self-service demand while the phone captures the rest.
9SiteLink myHub
SiteLink's myHub tenant portal ranks ninth because autopay enrollment at move-in is the leading indicator of collections health, and the portal is where existing tenants manage payment methods, view balances, and update details without calling the office. Making autopay the default path rather than an afterthought is a small UX decision with a large collections consequence.
The portal also supports the ECRI notification path, giving tenants a clean, documented channel to receive and respond to rate change notices, which matters because systematic increases applied to long-tenured customers are the largest controllable revenue lever in the asset class. It sits below the website builder because acquisition matters more than self-service retention. It ranks above revenue management overlays because it feeds them.
10Storable Revenue Management
Storable's revenue management tooling ranks tenth because existing customer rate increases are the single largest controllable revenue lever in self storage, and the platform's ability to run those programs on a schedule with sensible eligibility rules and a clean tenant notification path is worth more than most feature comparisons capture. A 500-unit facility at a $110 average rate collects roughly $55,000 monthly at full occupancy.
It is for operators who will actually run scheduled batches rather than deferring rate management to 'after we're stable,' which in practice means never, leaving the tenant base drifting below market with no alarm. It sits last because it depends on clean tenure data from the system of record above it. Third-party overlays are usually more sophisticated but add an integration seam.
How we ranked these
We ranked platforms on five weighted criteria: core facility management depth (unit/tenant/rate modeling, 25%), access control integration and automated lockout behavior (20%), online rental and autopay completeness (20%), revenue management and ECRI capability (20%), and integration breadth with third-party vendors (15%). Scores came from vendor documentation, published pricing, and operator-reported implementation experience across single and multi-site portfolios.
We deliberately ignored dashboard aesthetics, mobile app polish, and marketing claims about AI features, because none of those correlate with operational outcomes in this asset class. We also excluded per-seat pricing comparisons, since storage software prices by unit count or collections percentage, making seat math misleading. Vendor longevity was not scored directly, but compliance workflow depth around lien and auction law was treated as a proxy.
What to look for
What actually matters is which failure mode you can live with: bundle lock-in or integration ownership. storEDGE owns every handoff but prices as a system, so leaving means replacing payments, insurance, and website together. SiteLink connects to everything but leaves you triangulating between support desks when a gate stops syncing lockout status on a Friday night. Pick the pain you would rather manage.
The mistake most buyers make is demoing move-ins. Move-ins are the easy part and every platform performs them well. The pain lives in exception workflows: running a rate increase batch, processing a lien sequence, reconciling payments to accounting. Write down your three most painful monthly tasks and force the vendor to demo each one specifically.
Also test the unlock-on-payment path, not just lockout, because a paying tenant stuck at a gate at 9pm generates the worst reviews.
Related questions
What is the minimum software stack for a single self storage facility?
A facility management system handling units, tenants, billing, and rate management, plus online rentals, autopay with automated delinquency, and gate access control integrated to payment status. Easy Storage Solutions or a comparable lightweight platform covers this for a 300-600 unit site. Budget roughly $100-$400 monthly before payment processing, which typically runs two to three percent of collections.
Why does self storage software automate collections better than residential property software?
Storage can deny gate access immediately upon delinquency, subject to state lien law. A residential landlord cannot lock a tenant out of an apartment; the remedy is a legal eviction measured in months. That structural difference is why storage platforms automate lockout and unlock-on-payment while residential software cannot. It is the single most important thing to understand about why this software looks the way it does.
How much does access control hardware cost compared to the software subscription?
Access control is the capital item, not the subscription. Gate controllers, keypads, and wiring are project-scale expenses measured in thousands to tens of thousands depending on access points and whether you are retrofitting. Smart locks like Noke price per door, so converting 500 units is materially larger than adding one controlled gate. Stage it: gate first, then smart locks on a subset.
What is an ECRI and why does it matter more than move-in UX?
ECRI stands for existing customer rate increase. A tenant who moved in at $95 and stayed twenty-two months is usually paying below what a new tenant would pay for the identical unit. Systematic ECRI programs capture that gap and are the largest controllable revenue lever in self storage. Platforms that run those programs natively, with eligibility rules and clean notification paths, are worth more than better move-in screens.
Should I choose storEDGE or SiteLink for a multi-site portfolio?
Choose storEDGE if you want one vendor owning every handoff from online rental through billing, insurance, and gate access. Choose SiteLink if you want to run different access vendors, call centers, or revenue management tools across properties. SiteLink is the integration hub and the path of least resistance for mixed-vendor stacks, but you become the systems integrator and own the seams between vendors.
What breaks when you turn on automated lockouts too early?
If payment data is not yet trustworthy, automated lockouts will lock out paying customers. That burns credibility with your tenant base in a way that takes months to repair. Sequence matters: migrate units and tenants cleanly, enable autopay, test the online rental flow end to end, then connect access control. Only after both lockout and unlock-on-payment paths test correctly should you enable the delinquency ladder.
How do newer cloud-native platforms compare to incumbents in 2027?
Platforms like Tenant Inc's Hummingbird are legitimate options, particularly for automation-first operators, and they compete on modern UX and lower switching friction. The caution is not quality; it is depth of edge-case handling around lien processing, state-specific auction requirements, and delinquency law that incumbents accumulated over decades. Evaluate newer platforms specifically on those unglamorous compliance workflows, not dashboard screenshots.
What is the most expensive mistake operators make with storage software?
Never running rate increases. Nothing breaks, occupancy looks fine, and the tenant base slowly drifts well below market. There is no alarm for it. The eventual catch-up increase is large enough to trigger real move-outs instead of the gradual, absorbable adjustments a scheduled program produces. The defense is a program with eligibility rules that runs whether or not anyone remembers to think about it.
FAQ
What is the complete software stack for a self storage facility in 2027?
A facility management system such as storEDGE, SiteLink, or Easy Storage Solutions handling units, tenants, billing, and rate management. Around it: online rentals, autopay with automated delinquency, gate access control from PTI or Noke that locks out non-payers automatically, and a call center or CRM layer capturing phone leads. The stack is defined by integration depth between these parts, not by any single product.
How long does implementation take and what is the right sequence?
Days 1-30 migrate units and tenants into the system of record and get online rentals live. Days 31-60 connect access control and configure the delinquency ladder, testing both lockout and unlock-on-payment. Days 61-90 turn on rate management, stand up reporting, and connect accounting. Rushing the migration corrupts tenure dates, which silently disables rate increase eligibility for a year.
Why do tenure dates matter so much during migration?
Rate increase eligibility is driven by how long a tenant has been in place. A botched migration that resets everyone's move-in date to the migration date silently disables your most valuable revenue program for a year, and nobody notices because nothing visibly breaks. Scrutinize tenure dates specifically during data migration, alongside current rates, autopay enrollment status, and protection plan elections.
Is a third-party call center worth the cost for a small portfolio?
Call centers are typically priced per call or per lead rather than flat, so cost scales with marketing spend. That surprises operators who model it as fixed. For a single facility with a staffed office, the math rarely works. For two to ten facilities running remote or unattended, a shared call center starts mattering more than per-site software cost, because missed calls are missed rentals.
How should I model payment processing costs?
Payment processing is priced as interchange plus a markup, the way card processing always is. On a facility collecting $45,000 monthly in rent, processing at two to three percent is a real line item worth negotiating rather than accepting as fixed. It sits on top of the software subscription and is frequently the second-largest recurring software-adjacent cost after the platform itself.
What should I test in a vendor demo that vendors will not volunteer?
Ask them to run a rate increase batch, process a lien sequence, and reconcile payments to an accounting system, live, in the demo. Vendors demo move-ins beautifully because move-ins are the easy part. The pain lives in exception workflows. Also test the unlock-on-payment path specifically, because it fails more often than lockout and generates far angrier phone calls from paying customers.
Does self storage software overlap with portable storage or moving company software?
Barely. Moving is a dispatch and logistics business built around a job calendar, crews, trucks, and routing. A facility management platform models units and tenants. Operators running both a facility and a moving operation typically need two systems, because forcing one to do the other's work is a common and expensive mistake. The customer overlaps; the software model does not.
How does self storage software compare to 24-hour gym software?
They are closer than they look. Same recurring billing, same access control tied to payment status via badge or app entry, same unattended-hours model, same delinquency dynamics. The operational playbook for unstaffed gyms, verified identity at entry, remote monitoring, automated suspension on failed payment, is essentially what unattended self storage runs. Operators moving between categories find the patterns immediately familiar.
What is the difference between physical and economic occupancy?
Physical occupancy counts units rented. Economic occupancy measures revenue actually collected against what the facility could collect at market rates. Physical occupancy flatters every facility because it ignores below-market legacy tenants and delinquency. Configure reporting so you see economic occupancy, rate per square foot, and delinquency aging together. A facility at 92% physical occupancy can still be materially underperforming on revenue.
When should rate management be turned on relative to other systems?
Days 61-90, after billing behavior has stabilized. Deferring it to after we are stable in practice means never, and the facility runs two years with a below-market tenant base. The eventual catch-up increase is large enough to trigger real move-outs instead of the gradual, absorbable adjustments a scheduled program produces. Turn it on with defined eligibility rules, increase magnitude, and notification lead time.
Sources
- https://www.storable.com/solutions/storedge/
- https://www.sitelink.com/
- https://www.easystorage.com/
- https://www.ptisecurity.com/
- https://noke.com/
- https://www.tenantinc.com/
- https://www.selfstorage.org/
- https://www.insideselfstorage.com/
- https://www.sparefoot.com/
- https://www.ibm.com/think/topics/api
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-tech-stacksTop 10 Best Tech Stack Tools for MSP and IT Services Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for AI Observability Platform Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Independent Bakeries in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Home Inspection Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Septic and Portable Sanitation Services in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Online Travel Agencies (OTAs) in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Plumbing Contractors in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Independent Food Trucks in 2027
 tkTop 10 Best Tech Stack Tools for Concrete and Paving Contractors in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for API Security Vendors in 2027