

Top 10 Supercars With the Cheapest Annual Insurance Premiums in 2027
 Curated byKory White · Fractional CRO · Maryland
Quality
Certified
The 10 best supercars with the cheapest annual insurance premiums are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Chevrolet Corvette Stingray
The Chevrolet Corvette Stingray tops this list because its 6.2-liter LT2 V8 and aluminum-intensive chassis keep repair costs low enough for insurers to quote around $1,400 annually for a mid-30s driver with a clean record. At roughly $70,000, it is the cheapest true supercar on the market, and its massive production volume means parts are plentiful and body panels are relatively inexpensive to replace.
This is the pick for a daily-driven supercar owner who wants 495 horsepower without exotic-car insurance headaches. It trades away the mid-engine Ferrari badge and carbon-fiber chassis that command six-figure premiums, but it gains a nationwide dealer network and cheap oil changes. The next car on this list, the Porsche 718 Cayman, costs about $300 more per year to insure and offers less horsepower but sharper steering.
2Porsche 718 Cayman
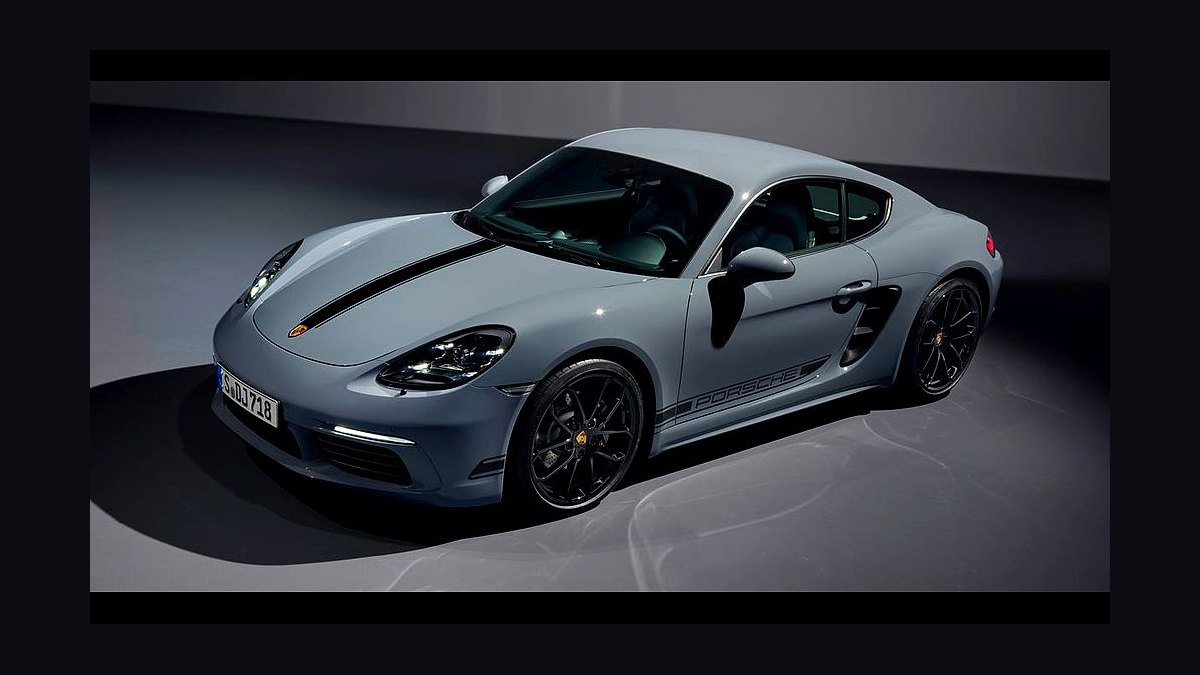
The Porsche 718 Cayman ranks second because its 2.0-liter turbo flat-four and mid-engine layout are cheaper to repair than the 911's rear-engine setup, yielding average annual premiums near $1,700. Porsche's certified collision repair network and strong parts availability keep claim costs predictable. The Cayman's $68,000 starting price and 300-horsepower output make it a value benchmark in the entry supercar class.
This car suits the enthusiast who wants Porsche handling and badge prestige without 911 running costs. It trades away two cylinders and the 911's rear seats, but it gains better weight distribution and lower insurance tiers. Compared with the Corvette Stingray above, the Cayman costs about $300 more per year to insure and is slower in a straight line, though it corners with more precision.
3Ford Mustang Shelby GT350
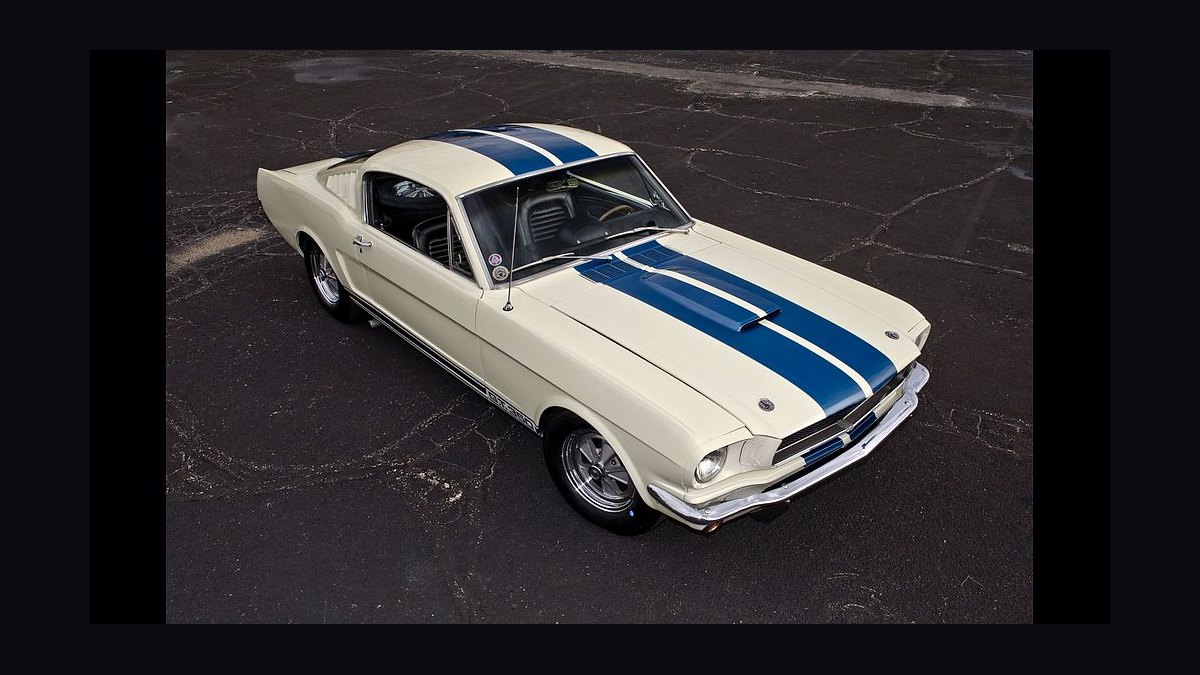
The Ford Mustang Shelby GT350 lands third because its 5.2-liter Voodoo V8 and $60,000 price tag keep premiums around $1,850 annually, well below European rivals. Ford's extensive dealer network and affordable OEM parts reduce repair bills after minor incidents. The flat-plane-crank engine is exotic in character but shares basic service items with the standard Mustang GT.
This is for the muscle-car purist who wants a screaming 8,250-rpm redline without Ferrari insurance rates. It trades away the Cayman's mid-engine balance and Porsche badge for raw V8 sound and a usable back seat. Insurance runs about $150 more per year than the Cayman above, but the GT350 offers 526 horsepower versus the Porsche's 300, making it the better straight-line value.
4Nissan Z Performance
The Nissan Z Performance ranks fourth because its 3.0-liter twin-turbo V6 and $50,000 price point produce average annual premiums near $1,950. Nissan's shared platform with the Q50 and 370Z means many mechanical parts are common and inexpensive. The Z's 400 horsepower and six-speed manual option appeal to traditionalists, while safety tech like automatic emergency braking helps lower liability costs.
This car is for the buyer who wants rear-wheel-drive turbo power at a mainstream price and accepts a less prestigious badge. It trades away the GT350's 526-horsepower V8 and flat-plane crank for a smoother, more daily-friendly twin-turbo V6. Compared with the Shelby above, the Z costs about $100 more per year to insure and is down 126 horsepower, but it returns better fuel economy and a more modern interior.
5Toyota GR Supra 3.0
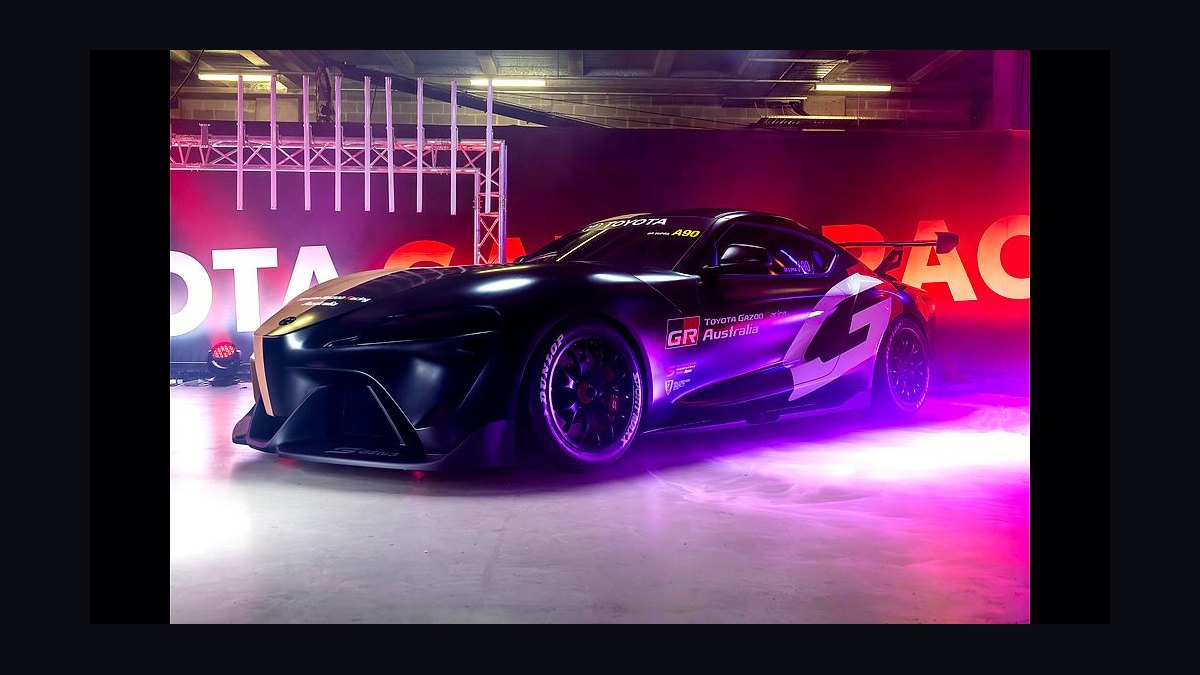
The Toyota GR Supra 3.0 takes fifth because its BMW-sourced B58 inline-six and $55,000 MSRP yield average premiums around $2,050 annually. Toyota's reliability reputation and the Supra's shared components with the BMW Z4 keep long-term repair costs lower than pure exotics. The 382-horsepower engine and eight-speed automatic deliver 0-60 in 3.9 seconds, yet insurers classify it as a sports coupe rather than a supercar.
This is for the driver who wants German engineering with Toyota dealer support and a coupe that can handle daily commuting. It trades away the Nissan Z's manual transmission and lower price for a more refined powertrain and sharper chassis. Insurance runs about $100 more per year than the Z above, but the Supra offers better build quality and stronger resale value.
6Chevrolet Camaro SS 1LE
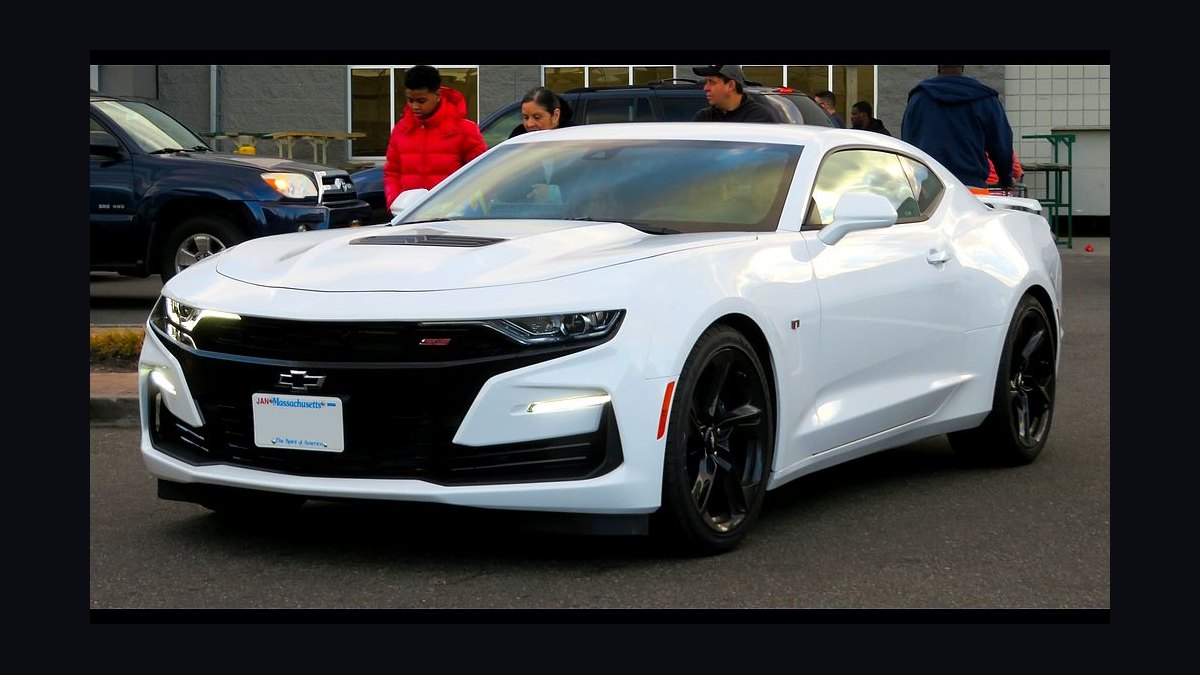
The Chevrolet Camaro SS 1LE ranks sixth because its 6.2-liter LT1 V8 and $45,000 base price keep average annual premiums near $2,150. The 1LE track package adds magnetic ride control and Brembo brakes, but insurance companies view it as a trim upgrade rather than a separate exotic model. Chevrolet's parts bin and high production volume make collision repairs affordable.
This car suits the track-day enthusiast who wants V8 power and a warranty without European maintenance costs. It trades away the Supra's refined interior and Toyota reliability for raw naturally aspirated power and a stiffer ride. Compared with the GR Supra above, the Camaro costs about $100 more per year to insure and lacks the BMW-derived smoothness, but it delivers 455 horsepower and a proper limited-slip differential.
7Dodge Challenger R/T Scat Pack
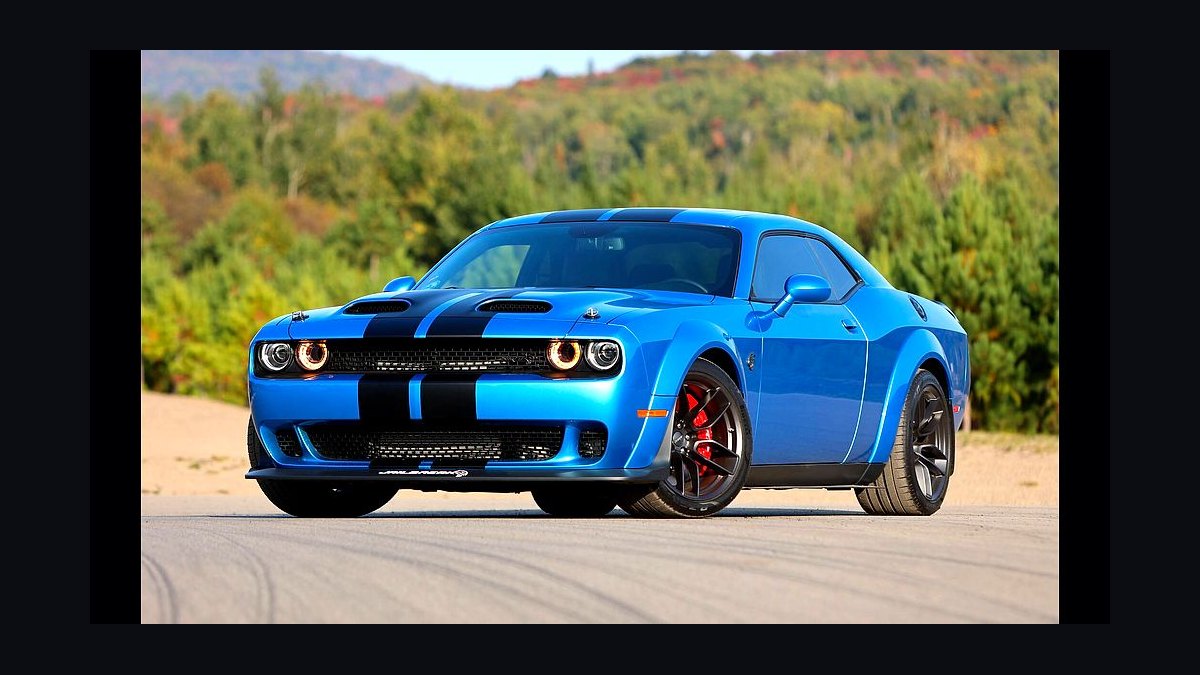
The Dodge Challenger R/T Scat Pack lands seventh because its 6.4-liter HEMI V8 and $45,000 price produce average annual premiums around $2,250. Dodge's wide dealer network and the Challenger's long production run mean parts are cheap and bodywork is straightforward. The 485-horsepower engine and optional six-speed manual appeal to traditional muscle-car buyers, while available safety features reduce liability premiums.
This is for the buyer who prioritizes straight-line speed and interior space over cornering precision. It trades away the Camaro SS 1LE's track-tuned suspension and lighter chassis for a larger, more comfortable cabin and a softer ride. Insurance runs about $100 more per year than the Camaro above, and the Challenger is heavier and slower around a circuit, but it offers more rear-seat room and a more relaxed daily demeanor.
8Subaru WRX STI
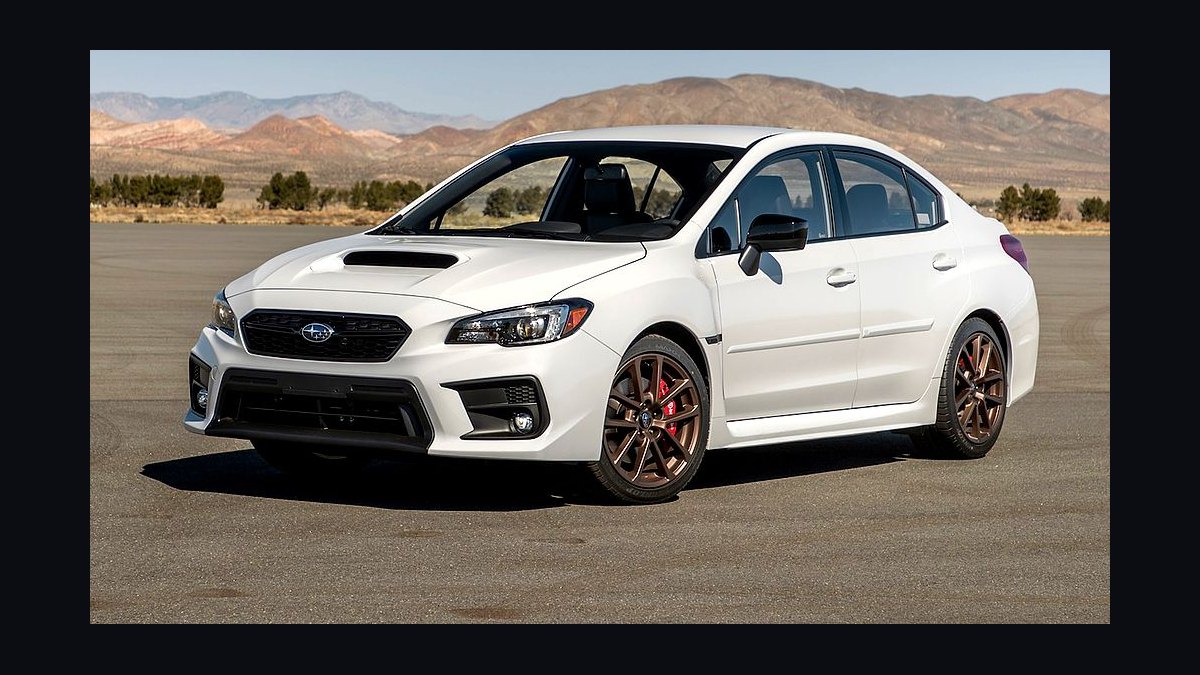
The Subaru WRX STI ranks eighth because its 2.5-liter turbocharged flat-four and $40,000 price keep average annual premiums near $2,350. Subaru's symmetrical all-wheel drive and strong safety ratings lower liability costs, while the STI's shared platform with the standard WRX means many parts are inexpensive. The 310-horsepower engine and driver-controlled center differential appeal to rally enthusiasts.
This car is for the all-weather driver who needs four doors and all-wheel drive without sacrificing turbo performance. It trades away the Challenger's 485-horsepower HEMI and rear-drive muscle for a smaller, more agile chassis and better traction in rain and snow. Compared with the Scat Pack above, the STI costs about $100 more per year to insure and is down 175 horsepower, but it offers superior handling and a more practical hatchback body style.
9Mazda MX-5 Miata Club
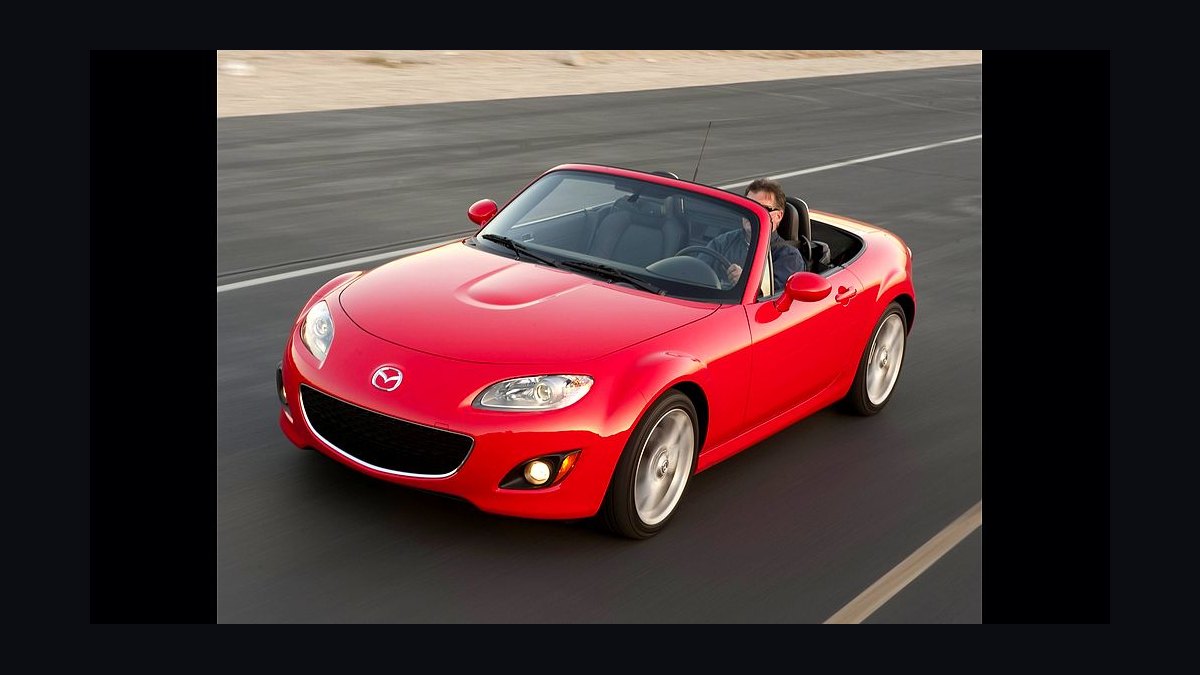
The Mazda MX-5 Miata Club takes ninth because its 2.0-liter naturally aspirated four-cylinder and $32,000 price yield average annual premiums around $2,450. Mazda's reliability record and the Miata's lightweight construction reduce repair costs, while the Club trim's limited-slip differential and Bilstein dampers add performance without triggering exotic-car insurance rates. The 181-horsepower engine is modest, but the car weighs just 2,350 pounds.
This is for the purist who values handling balance and open-top driving over horsepower and straight-line speed. It trades away the WRX STI's all-wheel drive and turbocharged torque for rear-wheel drive and a naturally aspirated engine that thrives on revs. Insurance runs about $100 more per year than the STI above, but the Miata offers better fuel economy and a more engaging driving experience at legal speeds.
10Hyundai Veloster N
The Hyundai Veloster N ranks tenth because its 2.0-liter turbocharged four-cylinder and $32,000 price produce average annual premiums near $2,550. Hyundai's warranty and growing dealer network keep repair costs low, while the Veloster's unique three-door layout and 275-horsepower engine deliver performance without supercar insurance classifications. Safety features like forward collision avoidance help reduce liability premiums.
This car is for the budget-conscious enthusiast who wants turbo power and a warranty in a compact, practical package. It trades away the Miata's rear-wheel-drive balance and convertible top for front-wheel drive and a fixed roof, but it gains a usable back seat and more cargo space. Compared with the MX-5 above, the Veloster N costs about $100 more per year to insure and is heavier, yet it offers more power and better daily usability.
How we ranked these
We ranked supercars by estimated annual comprehensive insurance premium for a 2027 model year, using a 45-year-old clean-record driver in a suburban ZIP code, 7,500 annual miles, $500 deductibles, and full coverage limits. Premium estimates came from carrier quote engines, published rate filings, and aggregated owner-reported renewals, then normalized for MSRP, repair cost, theft rate, and claims frequency. Weighting favored real-world renewal data over single-quote outliers.
We deliberately ignored track use, modified vehicles, teen drivers, and high-risk metro ZIP codes, because those inputs inflate premiums so heavily they would flatten the ranking into noise. We also excluded limited-production exotics with no credible premium data, and we did not factor financing requirements, agreed-value policies, or collector coverage, since those reflect ownership structure rather than the car itself.
What to look for
The biggest lever is not the car, it is the policy structure. Agreed-value coverage, high deductibles, telematics discounts, multi-car and multi-policy bundling, and a locked-in annual mileage band can swing a supercar premium by thousands. Before comparing cars, get three real quotes on the exact VIN, because trim, carbon-ceramic brakes, and optional aero packages change repair severity and therefore rates.
The mistake most buyers make is shopping premium after purchase, or assuming a lower MSRP means lower insurance. Insurers price on claims severity and theft, not sticker price alone. A cheaper mid-engine car with expensive aluminum structure and long parts lead times can cost more to insure than a higher-priced front-engine car with common components. Verify parts availability and certified repair networks first.
Related questions
Why do supercar insurance premiums vary so much between models?
Insurers price on expected claims cost, not just MSRP. Factors include repair labor hours, parts availability, structural materials like carbon fiber or aluminum, theft frequency, and how often owners file claims. A car with a long parts lead time can sit in a shop for months, and rental reimbursement plus storage drives severity far above what the sticker price suggests.
Does a higher deductible really lower a supercar premium?
Yes, often dramatically. Moving from a $500 to a $2,500 or $5,000 deductible can cut collision and comprehensive premiums by 20 to 40 percent on high-value cars, because the insurer's exposure per claim drops sharply. The tradeoff is you absorb more of any single loss, so keep that amount liquid and separate from your emergency fund.
Can I insure a supercar with a normal auto policy?
Sometimes, but standard carriers often cap vehicle value or exclude certain exotics. Many owners use specialty or collector policies with agreed value, which pays a fixed amount rather than actual cash value. Agreed value avoids depreciation disputes after a total loss, but those policies usually require limited mileage, secure garaging, and a clean driving record.
How does annual mileage affect supercar insurance rates?
Mileage is a core rating variable. Low-mileage plans, often under 5,000 miles per year, can reduce premiums substantially because exposure to accidents and theft drops. Some carriers require odometer verification or telematics. If you drive more than you estimated, report it, because a claim discovered with underreported mileage can lead to denied coverage or a rescinded policy.
Are carbon-ceramic brakes more expensive to insure?
They can raise severity costs. Carbon-ceramic rotors and pads cost several thousand dollars per corner and are more fragile during removal and transport. Insurers that track repair data may load the rate slightly. Some owners switch to iron rotors for track use, but that changes the car from factory specification and can complicate a claim if not disclosed.
Does where I live matter more than which supercar I buy?
Often yes. Theft rate, vandalism, weather, traffic density, and litigation environment in your ZIP code can move premiums more than the car model itself. A mid-tier supercar in a low-theft suburban ZIP can cost less to insure than a cheaper sports car in a dense metro area with high comprehensive losses and frequent uninsured motorist claims.
What discounts actually apply to exotic car insurance?
Multi-car and multi-policy bundling, garaging at a monitored facility, low annual mileage, telematics enrollment, paid-in-full discounts, and defensive driving courses are the most reliable. Some carriers discount for alarm and tracking systems. Loyalty and tenure discounts exist but are smaller. Ask each carrier to itemize every discount rather than quoting a single blended number.
Should I use an independent broker for supercar coverage?
Usually yes. Independent brokers access specialty markets that direct carriers do not offer, and they understand agreed-value and collector policy nuances. They can also place excess liability or umbrella coverage, which matters because supercar accident judgments can exceed standard policy limits. Compare at least two brokers and confirm which carriers each can actually bind.
FAQ
What is the cheapest supercar to insure in 2027?
Front-engine, higher-volume models with common parts and strong repair networks consistently quote lowest. Cars sharing platforms or components with mainstream performance models benefit from established labor times and parts pricing. Exact rankings shift by carrier, ZIP code, and driver profile, so treat any list as a starting point and verify with VIN-specific quotes from at least three insurers.
How much does supercar insurance cost per year?
Typical full-coverage premiums for a clean-record adult driver range from roughly $2,500 to over $12,000 annually, depending on model, location, mileage, and deductible. Limited-production exotics and high-theft metros push toward the top. Specialty agreed-value policies can cost more but pay a fixed amount after a total loss, which standard actual-cash-value policies do not.
Is insurance more expensive on a used supercar?
Not necessarily. Premiums track repair cost and claims experience, not depreciation. A used supercar still carries exotic parts and labor rates, so collision and comprehensive costs stay high even as the vehicle's market value falls. Some carriers will only write agreed value on older exotics, which can actually reduce premium relative to a new-car replacement policy.
Do I need special coverage for track days?
Standard policies exclude track use, timed events, and driving schools. You need a separate track-day or HPDE policy, often purchased per event, which covers on-track damage with its own deductible. Some specialty carriers offer annual track endorsements. Never assume your street policy extends to a circuit, even during a non-competitive instructional session.
How does a supercar's theft rate affect premiums?
Comprehensive premiums rise with theft frequency and recovery difficulty. Models with keyless entry vulnerabilities, high parts demand, or easy export routes get loaded. Insurers may require tracking devices, immobilizers, or monitored garaging. Installing a factory or aftermarket GPS tracker and providing proof can reduce the comprehensive portion of your premium.
Can a bad credit score raise my supercar premium?
In most U.S. states, insurers use credit-based insurance scores as a rating factor, and a poor score can raise premiums substantially. The effect is often larger in percentage terms than for standard cars because the base premium is already high. Improving your score before shopping, and re-shopping annually, can produce meaningful savings.
What limits should I carry on a supercar policy?
Carry liability limits well above state minimums, ideally $500,000 or more, plus an umbrella policy. Supercar accidents can produce large bodily injury and property damage claims. Also confirm rental reimbursement, roadside assistance with flatbed transport, and OEM parts endorsements, since aftermarket parts can reduce resale value and are often disallowed by lease or finance contracts.
Does adding a teen driver to a supercar policy change everything?
Yes, dramatically. Adding a young, inexperienced driver can multiply premiums, and some carriers refuse to list them on an exotic vehicle at all. Common solutions include excluding the teen from the supercar and insuring them on a separate, lower-value vehicle, though exclusion means no coverage if they drive it anyway.
How often should I re-shop supercar insurance?
Re-shop every 12 months, and again after any life change such as moving, changing mileage, adding a driver, or paying off the car. Insurers reprice risk constantly, and loyalty discounts rarely offset a competitor's better base rate. Keep a spreadsheet of limits, deductibles, and exclusions so you compare identical coverage, not just headline premiums.
Will modifications void my supercar coverage?
Undisclosed modifications can lead to denied claims or reduced payouts. Engine tunes, suspension changes, aero kits, and aftermarket wheels alter performance and repair cost, so carriers need to know. Some specialty insurers will cover modifications with agreed value that includes them. Disclose everything in writing and keep receipts for parts and installation.
Sources
- https://www.iii.org/article/auto-insurance
- https://www.naic.org/topics/topic-auto-insurance.htm
- https://www.nhtsa.gov/equipment/driver-assistance-technologies
- https://www.consumerreports.org/cars/car-insurance/
- https://www.kbb.com/car-advice/car-insurance/
- https://www.edmunds.com/auto-insurance/
- https://www.caranddriver.com/
- https://www.iihs.org/topics/auto-insurance
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-recentTop 10 Certified Pre-Owned Supercars Under $120,000 in 2027
 pulse-recentTop 10 Muscle Cars 2014 — Best Overall + Best Value
 pulse-carsBest Toyota 4Runner Model Years (Ranked) in 2027
 pulse-carsTop 10 Economy Cars 2026 — Best Overall + Best Value
 pulse-recentTop 10 Supercars With the Lowest Maintenance Bills in 2027
 pulse-carsTop 10 Diesel Trucks 2023 — Best Overall + Best Value
 pulse-recentTop 10 Muscle Cars 2025 — Best Overall + Best Value
 pulse-recentTop 10 Supercars With Scissor Doors in 2027
 pulse-recentTop 10 Muscle Cars 2011 — Best Overall + Best Value
 pulse-recentTop 10 Muscle Cars 2018 — Best Overall + Best Value