

Is leasing a supercar for three years cheaper than financing one in 2027?
 Curated byKory White · Fractional CRO · Maryland
Quality
Certified
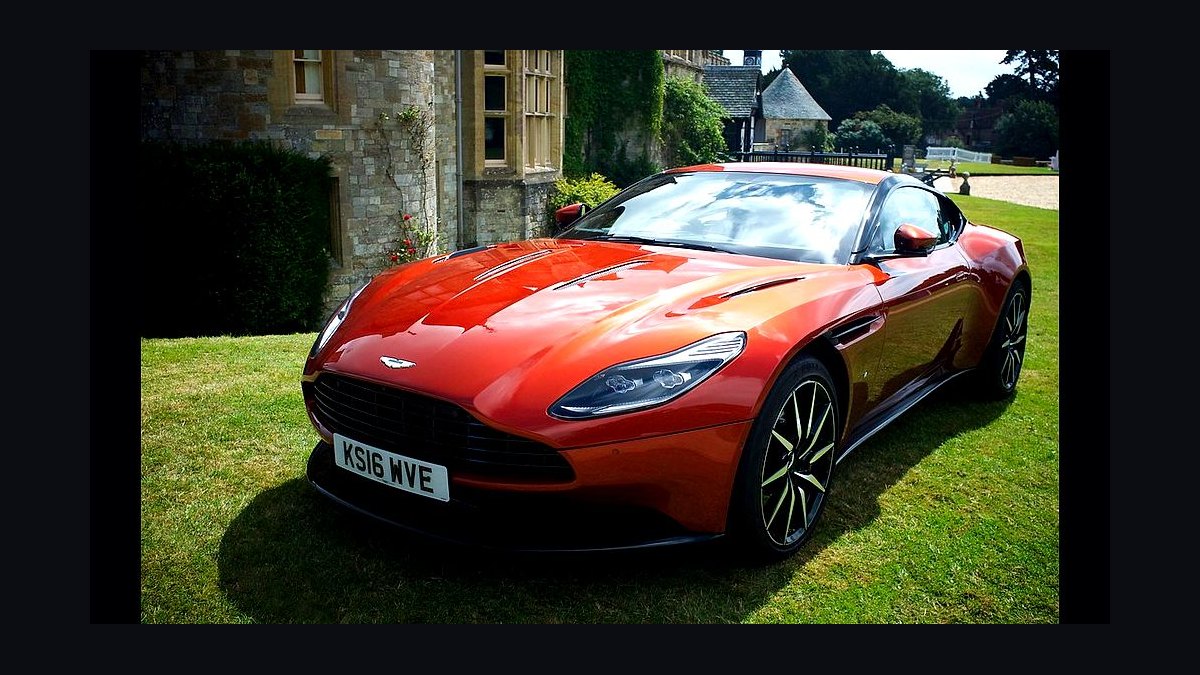
In most 2027 scenarios, leasing a supercar for three years is cheaper on monthly cash flow than financing, often by 20–40%, because you pay only depreciation plus rent charge rather than the full vehicle price plus interest. But financing can be cheaper in total cost if the car holds value, you keep it past term, or lease mileage caps trigger penalties.
What it is and why it matters
The question of whether leasing a supercar for three years is cheaper than financing one in 2027 comes down to a single structural fact: a lease and a loan are two different financial products that happen to put you in the same car. A lease buys the right to use a vehicle for a defined term and mileage allowance, then hands it back. A loan buys the vehicle itself, financed over a term, with the asset yours at the end once the balance is cleared. Because the two products price different things — depreciation and rent charge in one case, principal and interest in the other — the monthly payment comparison almost always favors leasing, while the total-cost comparison depends heavily on what the car is worth when the term ends.
For a supercar specifically, this distinction is amplified. Supercars occupy a strange corner of the market: many of them depreciate steeply in the first two years and then flatten out, and a handful of limited-production models actually appreciate. That depreciation curve is the single biggest input into a lease payment, because a lease is essentially a bet on residual value. If the lessor's residual assumption is conservative, the monthly payment is high. If it is aggressive, the payment is low and the lessor carries the risk that the car is worth less than predicted at turn-in. In 2027, residual assumptions for supercars have been shaped by several years of unusual used-market behavior, so the gap between a manufacturer-subsidized lease and an open-market lease can be enormous on the same car.
Why does this matter to a buyer or a fleet manager? Because the headline question — is leasing cheaper than financing — is the wrong frame if you only look at the monthly number. A lease can be $2,000 a month cheaper and still cost you more in total if you would have kept the car for six years and it held value. Conversely, financing can look cheaper per month on a long loan term while quietly costing you far more in interest and exposing you to a brutal depreciation hit if you sell in year three. The right answer requires modeling both paths across the same three-year window with the same assumptions about miles, insurance, maintenance, and exit value.
There is also a tax and business-use dimension that changes the math entirely depending on who you are. A business that can deduct lease payments as an operating expense may find leasing dramatically more attractive than depreciating a financed asset, particularly where local rules cap the depreciable amount for luxury vehicles. An individual buyer with no business use gets no such benefit and should evaluate the two purely on cash flow and total cost. This is why two people asking the identical question can get opposite correct answers.
Finally, 2027 is not a neutral year to ask this. Interest rates, manufacturer incentive programs, and residual-setting behavior all move together, and supercar brands in particular use lease subvention as a demand lever when inventory builds. A lease that was a bad deal in a tight market can become a good one when a brand needs to move metal, and a loan that was cheap when rates were low can become expensive when they are not. The comparison is therefore never static — it has to be run against the specific program available on the specific car in the specific month you are buying.
The step-by-step process
To answer this properly for a specific car, you run a structured comparison rather than eyeballing two payment quotes. The process below is the one a careful buyer or fleet analyst would follow, and it works for any supercar where both a lease and a finance program exist.
Step 1 — Establish the capitalized cost and the negotiated price. For a lease, the starting point is the capitalized cost, which is the negotiated price plus any fees minus cap cost reduction (down payment or trade equity). For a loan, it is the amount financed, which is the price plus taxes and fees minus down payment. These two numbers should be built from the same negotiated selling price, otherwise you are comparing a discounted lease against a sticker-price loan and the result is meaningless. Get the selling price in writing before you discuss either product.
Step 2 — Collect the lease-specific inputs. You need the money factor (the lease's interest rate, usually expressed as a small decimal that you multiply by 2,400 to approximate APR), the residual value as a percentage of MSRP for the exact term and mileage allowance, the acquisition fee, the disposition fee due at turn-in, and the mileage cap with its per-mile overage charge. On a supercar, the mileage cap is frequently 5,000 to 7,500 miles per year rather than the 10,000 to 12,000 typical of mainstream cars, and overage charges can run well above a dollar per mile. That single detail can swing the comparison.
Step 3 — Collect the loan-specific inputs. You need the APR, the term in months, the down payment, and the sales tax treatment in your jurisdiction. Some states tax the full purchase price of a leased car upfront, others tax each monthly payment — this alone can move the answer by thousands of dollars over three years.
Step 4 — Compute the lease payment. The standard formula is: depreciation portion equals (cap cost minus residual) divided by term months; rent charge equals (cap cost plus residual) multiplied by the money factor. Add those two, then add monthly tax where applicable. Add the acquisition fee amortized over the term if you want a true all-in monthly figure.
Step 5 — Compute the loan payment. Use a standard amortization formula on the amount financed at the APR over the term. Then, critically, compute the loan balance remaining at month 36, because that is your exit cost if you sell at the same three-year mark as the lease.
Step 6 — Model the three-year total cost of each path. For the lease: sum of 36 payments plus down payment plus acquisition fee plus disposition fee plus any expected overage plus the cost of any required excess wear. For the loan: sum of 36 payments plus down payment, minus the sale proceeds at month 36 (projected market value), plus any negative equity if the sale price is below the loan balance. This is the number that actually answers the question.
Step 7 — Run sensitivity on residual value. Because the loan path's total cost depends on what the car is worth at month 36, test at least three exit values: a pessimistic case (steep depreciation), a base case, and an optimistic case (the car holds or appreciates). The lease answer is fixed; the loan answer moves. The point at which the two cross is your break-even residual.
Step 8 — Add the non-payment costs that differ. Insurance can differ between lease and loan because lessors often require specific coverage limits. Maintenance and consumables — tires, brakes, fluids on a high-performance car — are usually the driver's responsibility in both cases but wear items at turn-in can trigger lease charges. Registration and personal property tax may be assessed differently.
Step 9 — Check for program subvention. Manufacturer lease programs sometimes carry a subsidized money factor or an inflated residual, which lowers the lease payment below what open-market math would produce. When that happens, leasing frequently wins outright. Ask the dealer for the current program sheet rather than assuming.
Step 10 — Decide based on your actual holding period. If you are certain you will exit at 36 months, the lease-versus-loan comparison is clean. If there is any chance you keep the car longer, the lease path forces a new decision at turn-in while the loan path simply continues with no transaction cost. That optionality has real value and belongs in the decision even though it does not appear in a spreadsheet.
Costs, timelines, and typical ranges
The numbers below are the ranges a careful buyer should expect to work with in 2027 for a supercar in the roughly $250,000 to $500,000 MSRP band. They are directional planning figures, not quotes, and every one of them should be replaced with the actual program terms on the specific car.
Down payment. Leases on supercars often require a substantial cap cost reduction — commonly 10% to 20% of MSRP, sometimes more on limited-production models. Loans typically ask for 10% to 20% down as well, though well-qualified buyers with established relationships can sometimes do less. On a $350,000 car, a 15% down payment is roughly $52,500 either way.
Monthly payment, lease. A three-year lease on a $350,000 supercar with a 55% residual and a money factor equivalent to about 6% APR, with 15% down, commonly lands somewhere in the $3,500 to $5,500 per month range before tax. If the manufacturer is subventing the program, it can drop meaningfully below that. If the car has a weak residual assumption, it can exceed it.
Monthly payment, loan. Financing $297,500 at 7% APR over 60 months produces a payment near $5,890. Over 72 months it drops to roughly $5,070. Over 36 months it rises to about $9,180. The loan payment is therefore usually higher than the lease payment on a comparable car, often by 30% to 60%, which is exactly why the monthly-payment comparison almost always favors leasing.
Residual value at month 36. This is the hinge. Mainstream luxury cars often sit near 50% to 55% of MSRP after three years. Supercars are more dispersed: volume-production models can land in the 45% to 60% range, while limited-run or enthusiast-favorite models have been known to hold 70% or more, and in some cases exceed their original MSRP. A lease with a 55% contractual residual on a car that actually retains 70% is a gift to the lessor — you paid for depreciation that never happened. That is the classic case where financing turns out cheaper in total cost.
Interest cost over three years. On the loan above, roughly $60,000 to $75,000 of the first 36 payments goes to interest depending on term and rate. On the lease, the rent charge over the same period is typically $35,000 to $55,000 at comparable rates, because the rent charge is calculated on the average of cap cost and residual rather than the full declining balance. That structural difference is a large part of why the lease payment is lower.
Fees. Acquisition fee on a supercar lease commonly runs $700 to $1,500. Disposition fee at turn-in commonly runs $300 to $500, sometimes waived if you lease another vehicle from the same brand. Doc fees, registration, and title vary by state and can add $500 to $2,000.
Mileage overage. At a 5,000-mile annual cap over three years, you have 15,000 miles total. A buyer who actually drives 8,000 miles a year will be 9,000 miles over, and at $1.00 to $2.00 per mile that is $9,000 to $18,000 due at turn-in. This single line item can erase the entire monthly savings of a lease. Anyone whose real driving exceeds the cap should price the overage into the comparison from the start, or negotiate a higher cap upfront, which raises the payment.
Wear and tear. Supercars are low-slung, wide, and prone to curb rash on expensive wheels, and tires on high-performance models can cost $2,000 to $4,000 per set and may not last the term. Lease turn-in standards allow for normal wear but charge for anything beyond it. Budget $2,000 to $6,000 of potential end-of-term charges unless you are confident the car will come back clean.
Insurance. Expect $4,000 to $12,000 per year depending on driver, location, and model. Lessors frequently require higher liability limits and lower deductibles than a lender does, which can add several hundred dollars a year to the lease path.
Timeline. Ordering a built-to-spec supercar can take six to eighteen months depending on brand and model. A lease or loan starts when you take delivery, not when you order, so the comparison should be run against the program available at delivery. Programs change monthly, and a quote from the order date may be stale by the time the car arrives.
Where teams get it wrong
Comparing monthly payments only. The most common error is declaring a lease cheaper because the monthly is lower. A lease payment is lower because you are not buying the asset — you are renting its depreciation. The correct comparison is three-year total cost including exit, and on that basis the answer flips depending on residual. Teams that report only the monthly number are giving their stakeholders an incomplete answer.
Using a different selling price on each side. Dealers will sometimes quote a lease on a discounted cap cost and a loan on sticker, or vice versa. If the two paths do not start from the same negotiated price, the comparison is invalid. Always anchor both to one written selling price.
Ignoring the mileage cap. A supercar lease with a 5,000-mile annual allowance is not comparable to a loan with unlimited miles unless you model the overage. Buyers routinely underestimate their annual mileage and get hit with a four- or five-figure bill at turn-in that they never included in the original math.
Assuming the residual is the market value. The contractual residual in a lease is the lessor's forecast, not a promise about the market. If the car is worth more than the residual at turn-in, the lessor keeps that equity — you do not. If it is worth less, the lessor absorbs the loss (unless you are on a closed-end lease with a market-value adjustment, which is rare on supercars). This asymmetry is the core economic difference between the two products and is frequently misunderstood.
Forgetting tax treatment. In states that tax the full purchase price of a leased vehicle upfront, the lease can carry a large one-time tax hit that a loan does not. In states that tax monthly payments, the lease gets a modest advantage. Not checking this before deciding is a common and expensive oversight.
Overlooking the opportunity cost of the down payment. A $50,000 cap cost reduction on a lease is money you will never see again. On a loan, that same $50,000 builds equity. Comparing the two without accounting for what the down payment could have earned elsewhere overstates the lease's advantage.
Treating the lease-end decision as free. At month 36, a lessee must either return the car, buy it out at the residual, or lease something else. Each has a transaction cost. A financed buyer simply keeps driving. If there is any real chance of keeping the car, the lease path imposes a decision and a cost that the loan path does not.
Assuming manufacturer subvention will still be there. A subsidized lease program can disappear between order and delivery. Building a plan around a money factor that no longer exists at delivery is a planning failure.
Ignoring insurance and consumables asymmetry. Lessors often mandate specific coverage. Tires and brakes on a supercar are consumed faster than on a normal car, and lease turn-in standards are strict. These costs land differently on each path and are frequently left out.
Decision framework: when to choose what
The framework below turns the comparison into a decision. It is deliberately built around the variables that actually move the answer: holding period, mileage, residual outlook, tax treatment, and whether the manufacturer is subventing.
Choose leasing when: you are confident you will exit at or near 36 months; your real annual mileage is at or below the cap; the manufacturer is offering a subsidized money factor or an inflated residual; you can deduct the payments as a business expense; you value a fixed, predictable monthly cost and do not want to carry residual risk; and the car is a volume-production model with a well-understood depreciation curve.
Choose financing when: there is a meaningful chance you keep the car past three years; you drive more miles than any reasonable lease cap allows; you believe the car will hold value better than the contractual residual implies (limited-run models, enthusiast favorites, allocation-restricted cars); your state taxes leases punitively upfront; you want to build equity and have an asset at the end; or you simply want to avoid turn-in charges and mileage anxiety.
The break-even test. Compute the lease's three-year total. Compute the loan's three-year total at your base-case exit value. Then find the exit value at which the two are equal. If you believe the car will be worth more than that break-even figure, financing is cheaper in total cost. If you believe it will be worth less, leasing is cheaper. Everything else is detail.
The hybrid case. Some buyers finance a car with a strong residual outlook and a short holding horizon, then sell at month 36 — capturing the equity that a lease would have surrendered to the lessor. This only works if the car actually holds value and the transaction costs of selling are manageable. It is the strategy that most often produces the "financing was cheaper" outcome.
The business-use case. If the car is used in a business, run the comparison after tax, not before. The ability to expense lease payments can dominate the entire analysis, and depreciation caps on luxury vehicles can make financing less attractive than it appears. This is the one situation where the answer can be decided by tax treatment alone.
Related questions
Does a supercar lease always have a lower monthly payment than a loan?
Almost always, yes, because you are paying depreciation plus rent charge rather than the full price plus interest. On a $350,000 car the gap is commonly 30% to 60%. But a lower payment does not mean lower total cost over three years.
What residual value makes financing cheaper than leasing?
It depends on the contractual residual in the lease. If the car's actual market value at month 36 exceeds the lease's residual assumption by enough to cover the loan's extra interest, financing wins. On strong-residual models that gap is often 10 to 15 percentage points.
Can I negotiate the money factor or residual on a supercar lease?
The residual is set by the lessor and is generally not negotiable. The money factor sometimes is, particularly if you have strong credit or the dealer is motivated. Cap cost reduction and the selling price are the levers you actually control.
What happens if I exceed the mileage cap on a supercar lease?
You pay a per-mile overage charge at turn-in, commonly $1.00 to $2.00 per mile on supercars. Going 9,000 miles over can cost $9,000 to $18,000, which frequently exceeds the entire monthly savings of the lease.
Is a lease or a loan better for a business using a supercar?
It depends on local tax rules. If lease payments are fully deductible as an operating expense and depreciation on a purchased luxury vehicle is capped, leasing often wins after tax. Run the comparison after tax, not before.
FAQ
Is leasing a supercar for three years cheaper than financing one in 2027? On monthly cash flow, yes in most cases — often 30% to 60% lower because you pay depreciation plus rent charge instead of the full price plus interest. On three-year total cost, it depends on residual value. If the car holds value above the lease's contractual residual, financing is cheaper in total.
What affects this comparison the most? Residual value at month 36 is the single biggest variable, because it determines what the financed car is worth when you exit. Mileage cap and overage charges are second, followed by interest rates, tax treatment, and whether the manufacturer is subventing the lease program.
How much does mileage overage typically cost on a supercar lease? Commonly $1.00 to $2.00 per mile, with caps frequently set at 5,000 to 7,500 miles per year rather than the 10,000 to 12,000 typical of mainstream cars. A driver averaging 8,000 miles a year on a 5,000-mile cap will owe thousands at turn-in.
Do supercars depreciate faster or slower than normal cars? It varies widely. Volume-production supercars often land near 45% to 60% of MSRP after three years, similar to luxury sedans. Limited-run and enthusiast-favorite models can hold 70% or more, and a few have appreciated. That dispersion is why the answer is not uniform.
Can a subsidized lease program make leasing cheaper even in total cost? Yes. When a manufacturer inflates the residual or discounts the money factor, the lease payment can fall below what open-market math would produce, and the three-year total can beat financing even on a car that holds value. Always check the current program sheet.
What is the break-even test for lease versus finance? Compute the three-year total cost of each path, then find the month-36 market value at which they are equal. If you expect the car to be worth more than that figure, financing is cheaper. If less, leasing is cheaper. Everything else is secondary.
Sources
- https://www.consumerreports.org/cars/buying-a-car/lease-vs-buy-a-car-a1046697334/
- https://www.edmunds.com/car-leasing/lease-vs-buy.html
- https://www.nerdwallet.com/article/loans/auto-loans/lease-vs-buy-car
- https://www.investopedia.com/terms/l/lease.asp
- https://www.irs.gov/publications/p463
- https://www.federalreserve.gov/releases/g19/current/
- https://www.kbb.com/car-advice/leasing-vs-buying/
- https://www.nada.org/
Related on PULSE
- How residual value assumptions are set on exotic-car leases
- Mileage caps and overage charges on high-performance vehicle leases
- Business-use tax treatment: expensing a supercar lease versus depreciation
- Closed-end versus open-end leases for exotic vehicles
- What happens at lease turn-in on a low-volume supercar
- Financing a supercar: term length, rates, and negative equity risk
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-carsBest Cars for Long-Distance Commuting in 2027 (Ranked)
 pulse-carsTop 10 Mid-Size Pickup Trucks 2023 — Best Overall + Best Value
 pulse-carsBest Used Electric Cars Under $50,000 in 2027 (Ranked)
 pulse-carsBest Audi e-tron Model Years (Ranked) in 2027
 pulse-carsWhat are the most reliable used subcompact SUVs under $20,000 in 2027 for long commutes in cold climates?
 pulse-carsBest BMW 7 Series Model Years (Ranked) in 2027
 pulse-carsBest Used 3-Row SUVs Under $30,000 in 2027 (Ranked)
 pulse-carsTop 10 Luxury Hybrid SUVs in 2027
 pulse-carsTop 10 Performance Electric Cars in 2027
 pulse-carsBest Used 3-Row SUVs Under $20,000 in 2027 (Ranked)