


What are the key cost per departure KPIs for regional airlines in 2027?
Quality
Certified
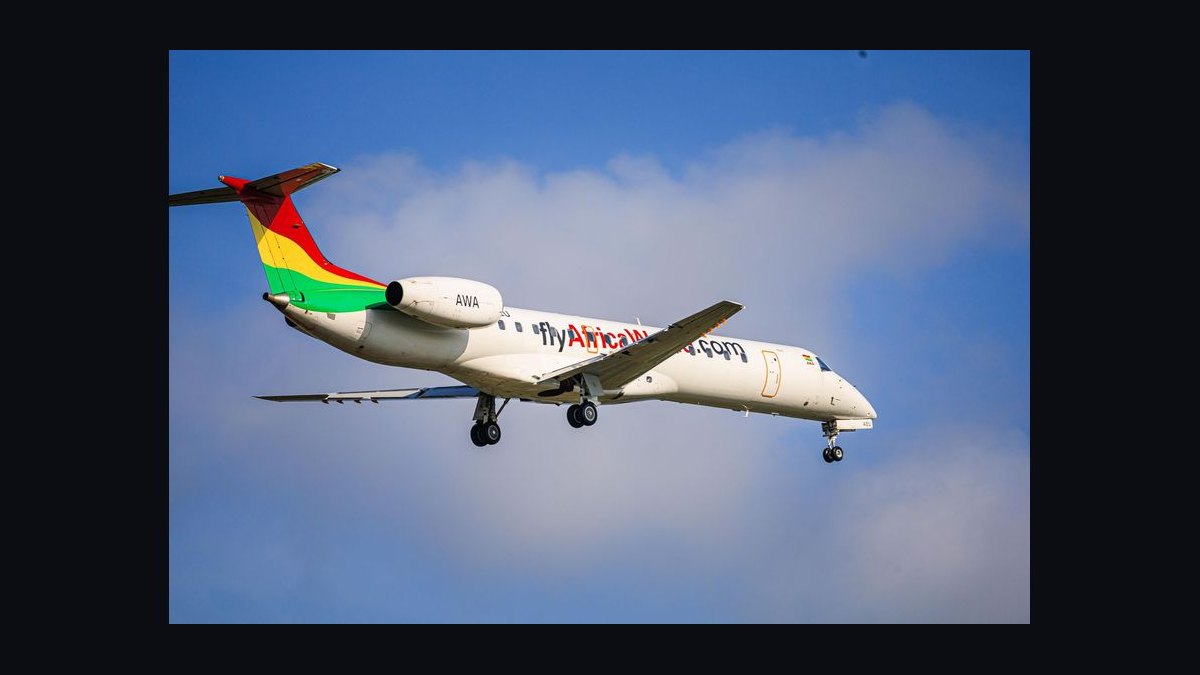
The key cost per departure KPIs for regional airlines in 2027 are crew cost per departure, maintenance cost per departure, station and ground handling cost per departure, fuel cost per departure, and ownership cost per departure. Two derived metrics complete the set: total controllable cost per departure, which strips out fuel and pass-throughs, and margin per departure, which pairs the metric against contract revenue.
What cost per departure is and why it matters for regional airlines
Cost per departure is a defined cost pool for a defined period divided by the revenue departures flown in that same period. It sounds trivial. It is not, because the definition of both numerator and denominator is where all the analytical value — and all the error — lives. For a regional airline, the departure is the unit of work the business actually sells, and that is why the metric carries more management weight than cost per available seat mile.
The structural reason regional carriers lean on the departure denominator is that CASM punishes them twice. Divide a fixed cost by more miles and CASM falls; divide it by more seats and CASM falls again. Regional aircraft — 50-seat jets, 70- to 76-seat jets, and 30- to 78-seat turboprops — have neither the seats nor the stage length to make CASM look competitive against a mainline narrowbody flying 1,100-mile legs. A regional CASM can run two to three times a mainline CASM while the underlying operation is perfectly well run. Comparing the two numbers tells you almost nothing about operating efficiency, which is exactly why regional finance teams built a different metric.
Departures are also a literal billing unit. Under a capacity purchase agreement — the contract structure governing the large majority of U.S. regional flying, where a mainline partner such as American, Delta, or United buys the regional's capacity and takes the revenue risk — the partner typically pays a blend of rates: a fixed monthly amount per aircraft, a rate per block hour, a rate per departure or cycle, and pass-through reimbursement for categories like fuel, landing fees, and sometimes insurance and aircraft rent. When a departure is a line item on an invoice, cost per departure is not an analytical convenience. It sits directly against a revenue line.
The third reason is that a very large share of a regional airline's cost is triggered by the act of departing rather than by the act of flying far. Pushback, ground handling, a turn crew, a fresh set of takeoff and landing cycles on engines and landing gear, a landing fee, a gate or common-use charge, a departure-driven slice of dispatch and crew scheduling load — all incurred once per flight regardless of whether the leg is 180 miles or 600. On a mainline long-haul, those departure-triggered costs spread over eight or ten hours of flying. On a regional operation averaging roughly one hour of block time per leg and six to eight legs per aircraft per day, they spread over almost nothing. That is the source of the metric's diagnostic power.
Heading into 2027, the metric matters more than it did five years earlier because the cost mix shifted violently toward departure-driven categories. Pilot compensation at U.S. regionals rose sharply through the 2022–2024 period as carriers competed for a constrained supply of qualified first officers, and those elevated rates were baked into multi-year contracts. Maintenance costs rose with parts inflation and engine shop-visit pricing. Fuel is the one large category that scales more with distance than with departures, and it is often a pass-through under CPAs — which moves it out of the regional's own cost-per-departure calculation entirely and into the partner's. Strip fuel out and what remains is overwhelmingly a departure-driven cost base. That is precisely the condition under which cost per departure becomes the dominant management metric.
One clarification on anchors: cost per departure and cost per block hour are cousins, not substitutes. Block hour cost captures the flying-intensive categories — fuel burn, hourly maintenance reserves, crew pay above guarantee. Departure cost captures the turn-intensive categories. A well-run regional finance function reports both side by side and watches the ratio between them. When departure cost relative to block hour cost climbs, the network is getting shorter-haul and turn-heavy; when it falls, the network is stretching. Neither is inherently good, but a change in the ratio should always trigger a question.
The step-by-step process for building the metric set
Building a defensible framework is a sequence, not a single calculation, and most errors happen in the first two steps rather than in the arithmetic.
Step one: fix the departure definition. Decide in writing what counts as a departure. The usual choice is revenue departures completed — a scheduled revenue flight that actually pushed back and flew a leg. Then decide explicitly how you treat cancellations, diversions, ferry flights, maintenance repositioning legs, and charter. A canceled flight generates no departure but has already generated crew cost, dispatch cost, and often a station cost. A diversion generates one departure in the schedule but two landings and possibly an extra departure to reposition. If you do not settle these edge cases up front, your denominator drifts by two to four percent month to month for reasons nobody can explain, and every variance analysis downstream becomes noise. Publish the definition and freeze it for the fiscal year.
Step two: define the cost pools and the exclusions. The standard regional pools are pilot and flight attendant costs (wages, benefits, per diem, training amortization, hotel and transportation for crews away from base), maintenance (line labor, heavy check amortization, engine and APU reserves or power-by-the-hour payments, component pool fees, rotables), aircraft ownership (lease payments or depreciation plus interest, plus hull insurance), fuel, station and ground handling (ramp, gate, deicing, into-plane fueling fees, landing fees, terminal rent), and overhead or G&A (dispatch, crew scheduling, system operations control, finance, IT, safety and compliance). Then decide what to exclude — typically special items, aircraft transition costs, and any pass-through category the partner reimburses at cost. Publish the exclusion list next to the definition so nobody has to guess.
Step three: choose the allocation basis for each pool. Some pools allocate cleanly to departures; some do not. Landing fees allocate per landing. Ground handling allocates per turn. Fuel does not — it allocates to block hours or to distance, and forcing it into a per-departure number without normalizing for stage length produces a metric that swings whenever the schedule changes shape. The practical answer is to report fuel per departure alongside average stage length so a reader can see whether a change came from price, burn, or route mix. Maintenance needs a split: line maintenance is genuinely departure-driven, while heavy checks and engine shop visits are cycle-and-hour driven and should be converted for reporting rather than allocated directly.
Step four: build the fleet-type and base cuts. A single company-wide cost per departure number is nearly useless for management. The useful cuts are by fleet type — a 50-seat CRJ200 operation and a 76-seat E175 operation have structurally different economics — by crew base, by station, and by CPA contract. Fleet type matters most because ownership cost per departure and maintenance cost per departure differ by large multiples across aircraft generations and support-agreement structures.
Step five: reconcile to the general ledger. Every pool must tie back to a reported line item. If the sum of your per-departure pools times departures does not equal total operating expense minus exclusions, you have an allocation leak, and someone will find it during a CPA rate negotiation at exactly the wrong moment. Build the reconciliation as a standing tab, not a one-time exercise.
Step six: set the reporting cadence and variance thresholds. Monthly reporting with a rolling twelve-month trend is standard. Set a variance threshold — commonly five percent against plan on any single pool — that automatically triggers a written explanation and an assigned owner. A threshold with no owner is decoration.
Step seven: publish the KPI set. The five primary pools are crew cost per departure, maintenance cost per departure, station and ground handling cost per departure, fuel cost per departure, and ownership cost per departure. Two derived metrics belong alongside them: total controllable cost per departure, which excludes fuel and pass-throughs and is the number management is actually accountable for, and margin per departure, which is contract revenue per departure minus total cost per departure. Expect a full build-out to take roughly one quarter: a few weeks to settle definitions and exclusions, a few weeks to build allocation logic and reconcile to the ledger, and one full month of parallel running before you trust the output enough to put it in front of a CPA partner.
Costs, timelines, and typical ranges for each KPI
Crew cost per departure. This is now the largest controllable pool at most U.S. regionals and it deserves the most instrumentation. The drivers are pay rates, crew utilization (block hours flown per crew member per month against the guarantee), duty rig and trip rig provisions in the collective bargaining agreement, deadheading, hotel and per diem, reserve coverage ratios, and training throughput. The mechanical relationship to departures is this: crews are paid largely by block hour with monthly minimum guarantees, so on a short-stage network each departure carries a larger slice of guaranteed pay. If average stage length drops from 60 minutes of block time to 50 minutes and nothing else changes, crew cost per departure rises even though crew cost per block hour is flat. Always read the two together. The diagnostic questions are: what percentage of pilots are paid at guarantee rather than for productive block, what is the reserve-to-lineholder ratio, and how much is spent on deadhead and hotel per departure. Reserve coverage and training pipeline costs are the two lines that most often surprise a regional CFO, because they scale with attrition, not with flying.
Maintenance cost per departure. Split this into three sub-lines because they behave differently. Line maintenance is genuinely departure-driven — every turn involves a walkaround, and MEL deferrals and minor defects surface at a rate roughly proportional to cycles. Heavy maintenance and engine overhaul are cycle-and-hour driven, and on a regional operation cycles accumulate fast: an aircraft flying six to eight legs a day accumulates cycles at several times the rate of a long-haul aircraft with the same annual utilization in hours. That is why landing-gear overhauls, brake and tire wear, and hot-section inspections dominate regional maintenance economics. Component and rotable pool fees are usually contracted per flight hour or per aircraft month and should be allocated accordingly, then converted for reporting. The single largest driver of variance is fleet age. An older 50-seat fleet late in its life carries heavy check and engine shop visit costs that a newer 76-seat fleet under a manufacturer support agreement simply does not. Comparing maintenance cost per departure across two operators without normalizing for fleet age and support-agreement structure is close to meaningless.
Station and ground handling cost per departure. This is the purest departure-driven pool and the easiest to benchmark internally. It includes ramp labor, gate and terminal rent, landing fees, common-use charges, deicing, into-plane fees, and any contracted handling. The dominant driver is station structure: a station where the regional handles itself with its own staff has a high fixed cost that falls per departure as frequency rises, while a station handled under contract by a third party or by the mainline partner has a mostly variable cost per turn. That distinction produces the sharpest actionable insight in the whole metric set — self-handled stations with low frequency are almost always the worst cost-per-departure outliers in a network, and the fix is either more frequency, a switch to contract handling, or exit. Landing fees vary widely by airport and are typically weight-based, so a heavier 76-seat aircraft pays more per landing than a 50-seat aircraft at the same field. Deicing is seasonal and can distort a winter month badly; report it as a separate line or the January number will look like a management failure rather than weather.
Fuel cost per departure. Driven by price per gallon, burn rate by aircraft type, stage length, taxi time, and altitude and routing. Under most CPAs fuel is a pass-through, so it does not affect the regional's own margin, but it very much affects the partner's view of whether a route is viable — and it is often the deciding factor in whether a small-market departure survives. Report it, but always report it with average stage length attached, and never include it in the controllable-cost number used to judge management performance.
Ownership cost per departure. Lease or debt service plus depreciation and hull insurance, divided by departures. The driver is utilization: the cost is essentially fixed per aircraft per month, so every additional departure lowers it. This is the metric that makes the case for schedule density. An aircraft flying seven legs a day carries meaningfully lower ownership cost per departure than the same aircraft flying five, and that gap is often the difference between a profitable and unprofitable line of flying. It is also the metric most distorted by aircraft on the ground — spares, aircraft awaiting maintenance, and aircraft parked for crew shortage all keep generating ownership cost while generating zero departures.
On timelines and typical ranges. Be careful with published benchmarks. Regional cost structures vary so much by fleet type, contract structure, and geography that a single industry-wide dollar figure is more likely to mislead than inform, and pass-through treatment means two carriers can report wildly different totals for identical operations. The defensible approach is to build your own baseline from your own ledger, then benchmark against U.S. Department of Transportation Form 41 filings, which regional carriers submit and which allow a like-for-like construction of cost per departure from public data. Normalize for seats and average stage length before drawing any conclusion. Expect the definitions-and-exclusions phase to take two to three weeks, the allocation build and ledger reconciliation another three to four weeks, and one full month of parallel running before the output is trustworthy.
Where regional finance teams get this wrong
The most common failure is a moving denominator. Teams change how they count cancellations or ferry legs mid-year, and every trend line breaks. Freeze the definition, and if it must change, restate history.
The second failure is comparing cost per departure across dissimilar fleets without normalizing. A 50-seat CRJ200 and a 76-seat E175 differ in ownership cost, crew pay scale, fuel burn, landing fee weight class, and maintenance program. Their departure costs will differ by a wide margin, and the larger aircraft will frequently show a higher cost per departure while showing a much lower cost per seat. If your objective is unit economics, look at cost per seat departure — cost per departure divided by seats — alongside the raw figure. Judging a 76-seat operation as "expensive" on raw cost per departure alone has driven real fleet decisions in the wrong direction.
The third failure is treating pass-through costs as controllable. Under a CPA, fuel, landing fees, and sometimes insurance and aircraft rent are reimbursed at cost by the mainline partner. Including them in the number you use to measure management performance means your headline metric swings with jet fuel prices that nobody in the building controls. Maintain two numbers: total cost per departure and controllable cost per departure. Report both, but manage to the second.
The fourth failure is ignoring the cancellation asymmetry. A canceled flight removes a departure from the denominator while leaving most of the cost in the numerator — crew were on duty, the station was staffed, the aircraft was owned. A month with a two percent completion factor shortfall will show a cost per departure increase that has nothing to do with cost discipline. Always publish completion factor next to the metric, and consider reporting a scheduled-departure version alongside the completed-departure version so the two effects can be separated.
The fifth failure is allocating overhead by a formula nobody believes. If corporate G&A is spread evenly across all departures, then a station with a handful of daily flights and a hub with dozens carry the same overhead burden per flight, which is not remotely true. Use a driver-based allocation — headcount, transactions, aircraft assigned — or hold overhead in a separate unallocated line rather than smearing it. A smeared allocation makes station-level decisions actively wrong.
The sixth failure is seasonality blindness. Deicing, summer crew overtime, and holiday-period reserve utilization all cluster. Always compare a month to the same month a year earlier, not to the prior month, and keep a rolling twelve-month figure as the headline number.
The seventh failure is confusing a rate change with a mix change. Cost per departure rose four percent — was that because a rate went up, or because the network shifted toward longer stages, larger gauge, or lower-frequency stations? Run a mix-versus-rate bridge every month. Without it, you will chase price when the problem is network shape, or restructure the network when the problem is a contract rate.
The eighth failure is building the metric without a revenue counterpart. Cost per departure in isolation invites cost-cutting that destroys contract margin. Pair it with contract revenue per departure and margin per departure. A route with a high cost per departure and a higher revenue per departure is a good route.
Decision framework: when to choose what
When cost per departure moves outside the variance threshold, the diagnostic order matters. Work from denominator to mix to rate, because fixing a rate problem when you have a denominator problem wastes a quarter.
First, check the denominator. Did completion factor fall? Did aircraft utilization drop because of spares, maintenance, or crew availability? A denominator problem shows up simultaneously across every pool — crew, station, maintenance, and ownership all rise together in the same direction and roughly the same proportion. That signature is unmistakable and it points to operations, not to cost.
Second, check the mix. Did average stage length change? Did fleet mix shift toward larger gauge? Did the frequency profile at self-handled stations change? A mix problem shows up in some pools and not others — fuel and crew move with stage length, station cost moves with frequency, ownership moves with utilization.
Third, and only third, check rates. A rate problem isolates to one pool: a new labor agreement moves crew and nothing else; an engine shop visit pricing increase moves maintenance and nothing else; a landing fee increase at a specific airport moves station cost at that airport.
The framework also answers the recurring strategic question: when is a departure worth keeping. Compare contract revenue per departure against total cost per departure at the route level, then ask whether the marginal cost of that departure — the cost that genuinely disappears if the flight goes away — is covered. Ownership cost does not disappear when you cancel a leg; the aircraft is still leased. Crew guarantee largely does not disappear. Station cost at a self-handled station does not disappear unless you exit the station entirely. What disappears is fuel, landing fees, variable handling, and marginal maintenance. If contract revenue per departure exceeds that genuinely avoidable cost, the departure is contributing even when it looks unprofitable on a fully allocated basis. That distinction between fully allocated and avoidable cost per departure is the single most valuable output of the whole framework, and it is the analysis most often skipped.
Related questions
How is cost per departure different from CASM?
CASM divides cost by available seat miles, so it falls automatically with longer stages and larger aircraft. Cost per departure divides by flight legs, isolating turn-driven costs. Regional airlines prefer the departure denominator because their short stages and small gauge make CASM comparisons against mainline carriers structurally unfair.
Should fuel be included in cost per departure?
Report it as a separate line, but exclude it from the controllable-cost figure used to judge management. Under most capacity purchase agreements fuel is reimbursed at cost by the mainline partner, so including it makes the headline metric swing with commodity prices nobody in the building controls.
What data source lets me benchmark against other regionals?
U.S. carriers file operating and financial data with the Department of Transportation under Form 41 and report traffic through the Bureau of Transportation Statistics. Those filings let you construct departures and cost pools on a comparable basis, though pass-through treatment still varies by carrier and contract.
Why does a canceled flight raise cost per departure?
A cancellation removes a departure from the denominator while most of the numerator remains — crew were on duty and paid, station staff were present, the aircraft was still owned and leased. Always publish completion factor alongside the metric so cost discipline and operational reliability are not conflated.
Which pool usually drives regional cost per departure increases?
Crew is typically the largest controllable pool at U.S. regionals, driven by pay rates, guarantee provisions, reserve coverage, and training pipeline costs tied to attrition. Maintenance is second and rises sharply with fleet age and cycle accumulation on high-frequency short-stage flying.
FAQ
What exactly counts as a departure in the denominator?
Most operators use completed revenue departures — a scheduled revenue flight that actually pushed back and flew. The critical part is documenting how you handle cancellations, diversions, ferry and maintenance repositioning legs, and charter flying. Whatever you choose, freeze it for the fiscal year and restate history if you ever change it, because an unstable denominator quietly corrupts every trend line and variance explanation downstream.
How many cost per departure KPIs should a regional airline actually track?
Five primary pools plus two derived figures is the right size. The pools are crew, maintenance, station and ground handling, fuel, and aircraft ownership. The derived figures are total controllable cost per departure — everything except fuel and other pass-throughs — and margin per departure, which is contract revenue per departure minus total cost per departure. More than that and the set stops being a dashboard and becomes a report nobody reads.
Can I compare my cost per departure to another regional airline's published figure?
Only with heavy normalization, and often not usefully at all. Fleet type, aircraft age, contract structure, pass-through treatment, self-handled versus contracted stations, and geography all move the number by large amounts. Build the comparison yourself from Form 41 filings using identical pool definitions rather than trusting a headline figure, and always normalize for seats and average stage length before drawing any conclusion.
Why does cost per departure rise when average stage length falls?
Because crew pay is largely block-hour based with monthly guarantees, and fixed ownership cost is spread across whatever flying the aircraft does. Shorter legs mean more departures per block hour, so departure-triggered costs — turns, landings, handling, dispatch — repeat more often per unit of flying. Crew cost per block hour can be flat while crew cost per departure climbs, which is why the two metrics must always be read together.
How does a capacity purchase agreement change the metric?
Substantially. Under a CPA, the mainline partner pays a blend of fixed monthly aircraft rates, block hour rates, and departure or cycle rates, and reimburses certain costs directly. That makes departures a literal billing unit and puts cost per departure directly against a contract revenue line. It also means several large cost categories are pass-through, so the controllable-cost figure is the one that determines the regional's actual margin.
What is the fastest way to find cost per departure outliers in a network?
Sort stations by cost per departure and overlay daily frequency and handling arrangement. Self-handled stations with low frequency surface immediately as the worst outliers, because a fixed station cost divided by a handful of daily turns produces an extreme figure. The remedies are limited and clear: add frequency, convert to contract or partner handling, or exit the station.
Sources
- https://www.bts.gov/topics/airlines-and-airports-0
- https://www.transtats.bts.gov/Fields.asp?gnoyr_VQ=FIL
- https://www.gao.gov/products/gao-23-105620
- https://www.faa.gov/data_research/aviation_data_statistics
- https://www.iata.org/en/publications/economics/
- https://www.transportation.gov/policy/aviation-policy/small-community-rural-air-service/essential-air-service
- https://www.sec.gov/edgar/searchedgar/companysearch
- https://www.icao.int/sustainability/Pages/eap-fp-economic-analysis.aspx
Related on PULSE
- How capacity purchase agreements shape regional airline economics
- Block hour cost vs. cost per departure: which unit metric to manage to
- Aircraft utilization KPIs and why ownership cost per departure moves
- Completion factor and its distorting effect on unit cost metrics
- Station handling models: self-handled vs. contracted cost structures
- Building a fleet-type cost comparison that survives scrutiny
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-industry-kpisTop 10 Restaurant Same-Store Sales Growth and Revenue Metrics in 2027
 pulse-industry-kpisTop 10 Healthcare Revenue Cycle Management Benchmarks in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Kitchen Hood & Exhaust Cleaning Services in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Medical Device Sales in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Heavy Truck Dealership in 2027
 pulse-industry-kpisTop 10 Airline Revenue per Available Seat Mile and Load Factor Metrics in 2027
 pulse-industry-kpisTop 10 E-commerce Marketplace Revenue KPIs in 2027
 pulse-industry-kpisTop 10 KPIs for Pressure Washing Companies in 2027
 pulse-industry-kpisSaaS: Net Revenue Retention as the True North Star for Expansion MRR in 2027
 pulse-industry-kpisTop 10 Sales KPIs for AI Sales Coaching / Conversation Intelligence in 2027