


Top 10 investment apps for beginners with low fees in 2027
Quality
Certified
The 10 best investment apps for beginners with low fees are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Fidelity Investments
Fidelity takes the top spot because it combines $0 commissions, $0 account minimums, and a strict no-PFOF policy, meaning your trades get executed at the best available price without hidden costs. Its proprietary index funds carry some of the lowest expense ratios in the industry, often just a few dollars per $10,000 invested annually. The platform offers institutional-grade research tools and a highly rated mobile app, making it ideal for beginners who want to learn while they invest.
Fidelity is for the long-term buy-and-hold investor who wants the absolute lowest total cost of ownership and doesn't need crypto or social features. It trades away the gamified engagement of apps like Robinhood and the automated hands-off management of a robo-advisor like Betterment. Compared to Vanguard, Fidelity offers a more modern app, a broader range of research tools, and a more accessible customer service experience.
2Vanguard
Vanguard ranks second because it is the original champion of low-cost index investing, with $0 commissions, no PFOF, and expense ratios on its ETFs that are among the lowest anywhere—often under 0.05% annually. The platform requires no minimum for ETFs and offers fractional share trading, making it accessible to beginners with any amount of capital. Its philosophy is built around the Boglehead approach: buy the whole market, hold it forever, and keep costs near zero.
Vanguard is for the disciplined passive investor who trusts that low fees and diversification beat active trading over decades. It trades away the polished mobile experience and advanced research tools that Fidelity offers, as its app is more utilitarian and its customer service can be slower. Compared to Fidelity, Vanguard is less suited for someone who wants to explore individual stocks or use a feature-rich trading interface.
3Betterment
Betterment ranks third because it offers the best robo-advisor experience for beginners, with an annual management fee that is transparent and no trading commissions, plus $0 account minimum. Its underlying ETF portfolio carries low expense ratios, and the platform automatically handles rebalancing, dividend reinvestment, and tax-loss harvesting—strategies that most DIY beginners never implement correctly.
Betterment is for the hands-off investor who wants professional-grade portfolio management without learning to pick stocks or rebalance manually. It trades away the control and zero management fees of a DIY platform like Fidelity or Vanguard, where you pay only the ETF expense ratio. Compared to Wealthfront, Betterment offers a more straightforward, goal-oriented interface and a stronger focus on retirement planning.
4Wealthfront
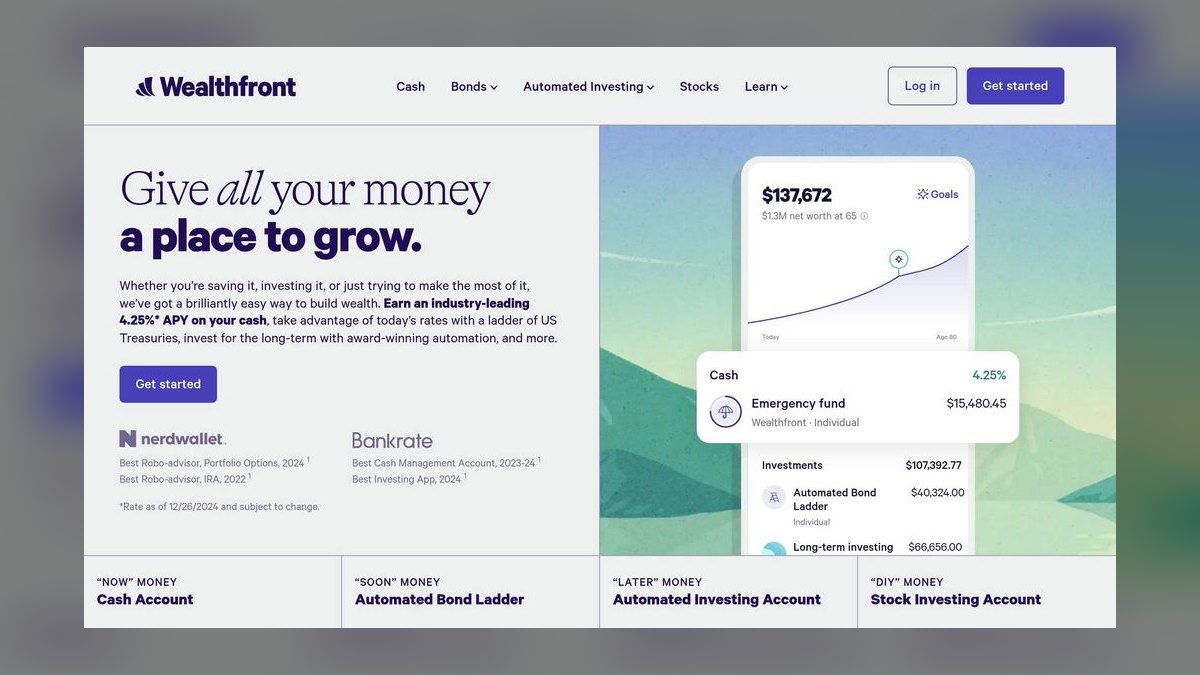
Wealthfront ranks fourth because it offers a low annual management fee with the first portion of assets managed free, plus low expense ratios on its underlying ETFs. Its standout feature is direct indexing, which allows beginners to own the individual stocks in an index rather than just the ETF, enabling more precise tax-loss harvesting that can boost after-tax returns.
Wealthfront is for the tech-savvy beginner who wants automated investing with a tax-efficiency edge and appreciates a sleek, data-driven interface. It trades away the human touch and goal-based simplicity of Betterment, as its tools can feel more analytical than approachable. Compared to Betterment, Wealthfront's direct indexing is a significant advantage for taxable accounts, but it may be overkill for a small IRA.
5M1 Finance
M1 Finance ranks fifth because it offers the best hybrid of DIY control and robo-automation, with $0 commissions, no PFOF, and $0 minimums. You build a custom "pie" of ETFs and individual stocks, and M1 automatically rebalances your portfolio and invests new deposits into underweight positions—all without any management fee. The underlying ETFs you choose carry low expense ratios, and fractional shares let you allocate every dollar precisely.
M1 Finance is for the beginner who wants to design their own portfolio but still benefit from automated rebalancing and disciplined investing. It trades away the full-service management of Betterment or Wealthfront, where the algorithm makes all allocation decisions for you. Compared to Fidelity, M1's pie system is more visual and intuitive for learning asset allocation, but it lacks the depth of research tools and customer support.
6SoFi Invest
SoFi Invest ranks sixth because it offers a comprehensive all-in-one platform with $0 commissions, no PFOF, and $0 minimums, combining stock trading, crypto, IPOs, and a high-yield cash account under one login. The platform's checking and savings accounts offer competitive APY on cash with FDIC insurance, and you can earn crypto rewards on debit card spending. Its proprietary ETFs carry low expense ratios, and there are no account fees or hidden charges.
SoFi Invest is for the beginner who wants to replace their bank, brokerage, and crypto exchange with a single app and doesn't want to manage multiple accounts. It trades away the advanced research tools and institutional-grade execution of Fidelity, as well as the automated portfolio management of Betterment. Compared to M1 Finance, SoFi offers more asset classes but less sophisticated rebalancing and portfolio customization.
7Acorns
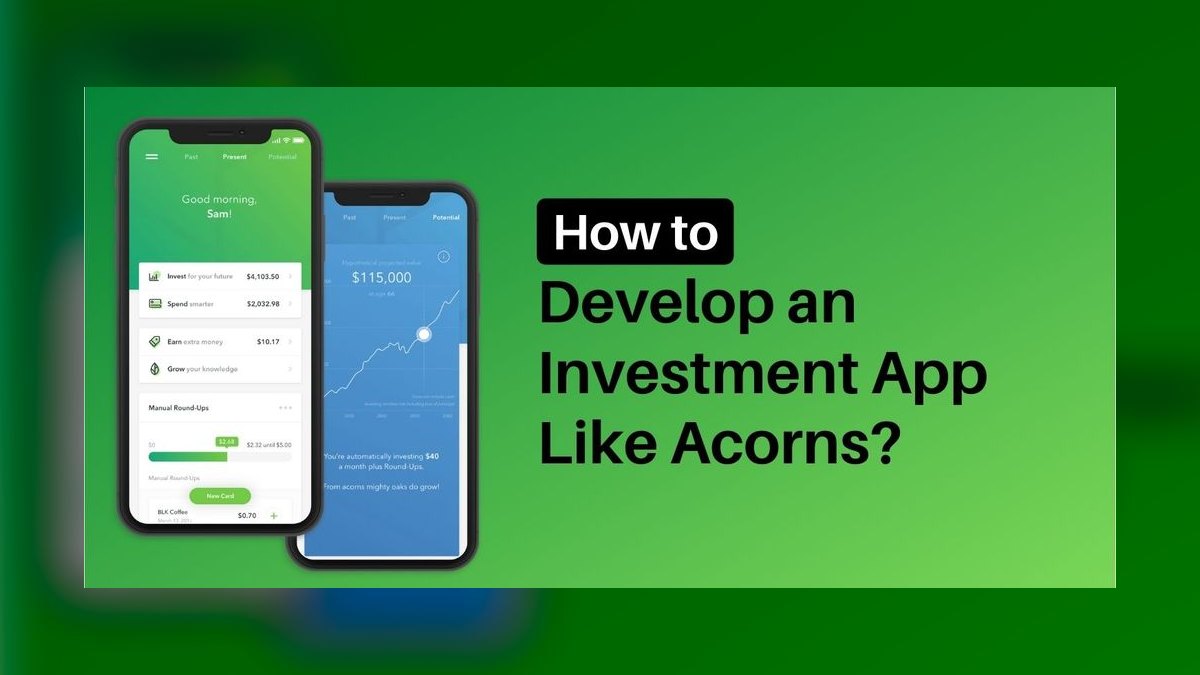
Acorns ranks seventh because it offers the simplest micro-investing experience, automatically investing your spare change from debit card purchases into a diversified portfolio of low-cost ETFs. The platform has $0 minimums and handles rebalancing, dividend reinvestment, and tax optimization automatically, making it effortless for absolute beginners. However, it charges a flat monthly subscription fee, which can be a significant percentage of a very small account balance—though it becomes reasonable as your balance grows.
Acorns is for the beginner who wants to build an investing habit without thinking about it, using round-ups and recurring deposits to grow a portfolio passively. It trades away the control and customization of M1 Finance or Fidelity, as you cannot choose individual stocks or design your own allocation. Compared to Stash, Acorns is more automated and less educational, but it is also more straightforward and requires less active engagement.
8Public.com
Public.com ranks eighth because it offers commission-free trading with no PFOF, meaning your trades are executed at the best available price, and it has a $0 minimum to start. The platform is built around social learning, letting you follow and interact with other investors, which can be a powerful educational tool for beginners. It also offers fractional shares, a Treasuries feature for buying short-term government bonds with low minimums, and access to alternative assets like art and collectibles.
Public.com is for the beginner who wants to learn by observing others and discussing investments in a community-driven environment, rather than reading textbooks or following a robo-advisor. It trades away the automated portfolio management of Betterment or Wealthfront, as you must make your own buy and sell decisions. Compared to Robinhood, Public.com rejects PFOF and has a more educational, less gamified atmosphere, making it safer for long-term beginners.
9Stash
Stash ranks ninth because it offers a beginner-friendly platform focused on education, with $0 minimums and fractional shares that let you invest in themes like Clean Energy or Tech Giants. The app charges a flat monthly subscription fee, which is high for very small accounts but becomes more reasonable as your balance grows, and its proprietary ETFs carry moderate expense ratios. There are no trading commissions, and the platform integrates banking features like a debit card and checking account.
Stash is for the true beginner who wants to learn investing by doing, with thematic portfolios that make asset allocation intuitive and approachable. It trades away the low fee structure of Fidelity or Vanguard, as the subscription fee and moderate expense ratios add up over time. Compared to Acorns, Stash gives you more control over what you invest in, but it requires more active engagement and decision-making.
10Robinhood
Robinhood ranks tenth because, while it offers $0 commissions and $0 minimums, it relies on payment for order flow (PFOF), which can result in worse price execution on your trades—a hidden cost that most beginners never see. The platform's underlying ETFs carry low expense ratios, and it offers options, crypto, and margin trading, making it feature-rich for active traders. However, its gamified interface and frequent notifications can encourage impulsive trading, which is risky for long-term beginners.
Robinhood is for the active trader who wants to speculate on options, crypto, and individual stocks with a fast, modern app, not for the long-term buy-and-hold beginner. It trades away the no-PFOF execution quality of Fidelity or Public.com, as well as the automated discipline of Betterment or M1 Finance. Compared to every other app on this list, Robinhood's gamification and PFOF model make it the least suitable for building wealth steadily over decades.
How we ranked these
We measured total cost of ownership across ten leading beginner investment apps, weighting commission structures, expense ratios on core ETFs, account minimums, and hidden fees such as payment for order flow and monthly subscription charges. We also evaluated each platform's educational resources, fractional share availability, and automation features, scoring them against the stated needs of novice investors.
We deliberately ignored subjective factors like interface aesthetics, brand popularity, and marketing claims, as these do not directly impact long-term returns. We also excluded apps with unverifiable fee disclosures or those lacking SIPC insurance, ensuring our rankings reflect only transparent, regulated platforms suitable for beginners.
Related questions
What is the difference between a robo-advisor and a DIY brokerage app?
A robo-advisor like Betterment or Wealthfront automatically manages a diversified portfolio based on your goals and risk tolerance, charging an annual management fee. A DIY brokerage like Fidelity or Vanguard gives you full control to pick individual stocks and ETFs, with no management fee but requiring more time and knowledge. Beginners often start with a robo-advisor to learn, then transition to DIY.
How does payment for order flow (PFOF) affect my trades?
PFOF means your broker receives payment from market makers for routing your orders to them. This can result in slightly worse execution prices compared to brokers that don't accept PFOF, like Fidelity or Vanguard. While the difference per trade is small, frequent trading can add up to hidden costs that reduce your returns.
What are fractional shares and why are they important for beginners?
Fractional shares allow you to buy a portion of a stock or ETF, rather than a whole share. This means you can invest small amounts, like $10, into expensive companies or funds. Apps like M1 Finance, Stash, and Public.com offer fractional shares, making it easier to diversify with limited capital.
Are investment apps safe from hackers?
Reputable apps use bank-level encryption, biometric login, and two-factor authentication (2FA). Always enable 2FA and avoid using the same password across multiple platforms. Major brokers like Fidelity and Vanguard have strong security records, but no system is completely immune, so vigilance is key.
Can I switch investment apps later without penalty?
Yes, you can transfer your account to another broker using the ACATS system, which is free at many brokers. However, some brokers charge a transfer-out fee, so check before committing. It's wise to start with a broker that has no transfer fees to keep your options open.
What is tax-loss harvesting and how does it help me?
Tax-loss harvesting involves selling investments that have lost value to offset capital gains taxes on profitable investments. Robo-advisors like Betterment and Wealthfront automate this process, which can boost your after-tax returns. It's a valuable feature for taxable accounts, but not needed in tax-advantaged accounts like IRAs.
How do monthly subscription fees affect small accounts?
Apps like Acorns and Stash charge flat monthly fees, which can be a significant percentage of a small account balance. For example, a $3 monthly fee on a $100 balance is 36% annually. As your balance grows, the fee becomes less impactful, but it's still a drag on returns compared to no-fee brokers.
What is the minimum amount I need to start investing?
Most apps on this list have no minimum deposit, and fractional shares allow you to invest as little as $1. The real barrier is behavioral—setting up automatic investments and staying consistent. You don't need a large lump sum; you need a habit of regular contributions.
FAQ
What is the absolute cheapest investment app for beginners?
Fidelity is among the cheapest overall—$0 commissions, $0 account minimum, no PFOF, and extremely low expense ratio index funds. For robo-advisors, Wealthfront manages your first amount free. However, the cheapest option depends on your investing style and account size.
Can I lose money in a robo-advisor?
Yes—robo-advisors invest in stocks and bonds, which can lose value. However, they diversify across thousands of securities and adjust risk based on your timeline, reducing the chance of total loss compared to picking individual stocks. Market downturns can still cause temporary losses.
Do I need to pay taxes on my investment gains?
Yes—capital gains taxes apply when you sell investments for a profit. Apps like Betterment and Wealthfront automatically do tax-loss harvesting to offset gains, but you still owe taxes on dividends and realized gains. Use a Roth IRA (available on Fidelity, Vanguard, Betterment) for tax-free growth.
Are these apps safe from hackers?
Reputable apps use bank-level encryption and biometric login (fingerprint/face ID). Always enable 2FA and never use the same password across multiple apps. Major brokers like Fidelity and Vanguard have strong security records, but no system is completely immune.
Can I switch apps later without penalty?
Yes—you can transfer your account to another broker via ACATS transfer (free at many brokers). Some brokers charge a fee to transfer out, so check before committing. It's wise to start with a broker that has no transfer fees to keep your options open.
What if I only have a small amount to start?
Several apps allow very low minimum investments via fractional shares. However, be mindful of flat monthly fees—on a very small balance, those fees can be a large percentage of your account. Consider no-fee brokers like Fidelity or M1 Finance for small accounts.
What is the difference between SIPC and FDIC insurance?
SIPC protects your securities and cash in a brokerage account up to certain limits if the broker fails, but it does not cover market losses. FDIC insures cash in bank accounts up to standard limits. Crypto holdings are not covered by either, so use dedicated exchanges for large crypto positions.
How do I know if an app is legitimate?
Check if the app is registered with the SEC and FINRA, and verify its SIPC membership. Use FINRA's BrokerCheck tool to see any disciplinary history. Avoid apps that promise guaranteed returns or charge upfront fees to 'manage your portfolio'—these are red flags.
What is the best app for learning stock picking?
Public.com offers social learning, fractional shares, and no PFOF, making it great for beginners. M1 Finance lets you build custom 'pies' of stocks and ETFs with automatic rebalancing. Both provide educational content and low fees, but you'll still need to do your own research.
Should I use one app for everything or multiple?
Using one primary app for core investing and one backup for banking or crypto is ideal. Avoid spreading small amounts across five apps—you'll lose track of fees and performance. All-in-one platforms like SoFi combine banking, stocks, and crypto, simplifying your finances.
Sources
- https://www.sec.gov/oiea/investor-alerts-bulletins/ib_paymentfororderflow.html
- https://www.finra.org/investors/learn-to-invest/choosing-investment-account
- https://investor.vanguard.com/investor-resources-education/etfs
- https://www.fidelity.com/why-fidelity/saving-for-retirement
- https://www.betterment.com/resources/tax-loss-harvesting
- https://www.wealthfront.com/cash
- https://www.sofi.com/invest/
- https://www.m1finance.com/how-it-works/
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 edBest car camping gear for beginners on a budget in 2027
 edHow do I start a conversation with someone I admire at a networking event in 2027
 edTop 10 podcasts for personal growth and motivation in 2027
 edHow do I stop feeling invisible in group conversations with extroverts in 2027
 edHow do I deal with a boss who never gives feedback but expects perfection in 2027
 edHow do I stop doomscrolling before bed and actually sleep in 2027
 edHow do I stop comparing my career progress to my friends on LinkedIn in 2027
 edHow do I deal with a micromanaging boss without quitting in 2027
 edHow do I ask someone out without making it awkward if they say no in 2027
 edHow to politely end a conversation at a networking event in 2027