


Should I open or buy a Bruster's Real Ice Cream franchise in 2027?
Quality
Certified
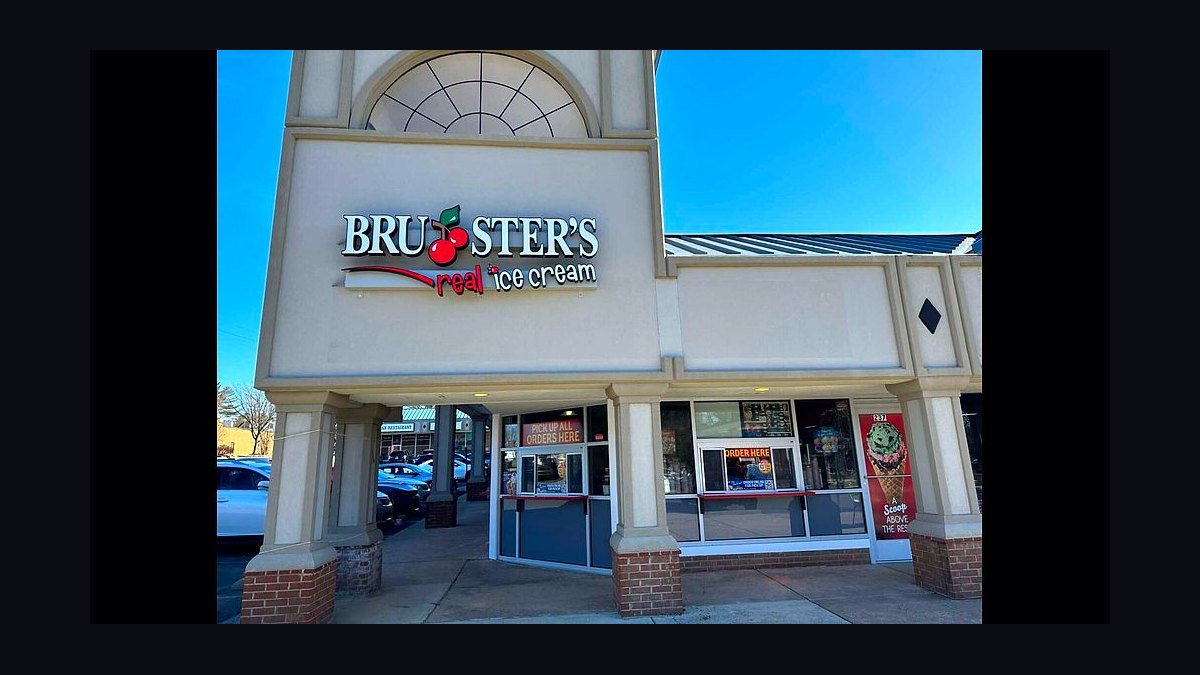
Open or buy a Bruster's Real Ice Cream franchise in 2027 only if you control $500,000+ in unencumbered liquid capital, can secure a freestanding pad site in a daytime-heavy Sunbelt or Mid-Atlantic suburb, and can personally absorb a five-to-six-month seasonal cash squeeze. The 2026 FDD lists a $409,000–$2,644,060 total investment, a 5% royalty, and $673,438 system-wide AUV — numbers that reward disciplined, present operators and punish undercapitalized or absentee ones.
What it is and why it matters
Bruster's Real Ice Cream is a scoop-shop concept founded in Bridgewater, Pennsylvania in 1989 by Bruce Reed, built around batch-frozen, made-fresh-on-premises product rather than a shipped-in commissary mix. The 2026 FDD shows 205 franchised units and 1 company unit spread across roughly 22 U.S. states plus Guyana, India, and Korea — a mid-sized system, large enough to have a real supply chain and training infrastructure, small enough that any single franchisee's results still swing heavily on local execution rather than national brand pull. That mid-size positioning is itself a signal: a buyer isn't inheriting the marketing muscle of a billion-dollar QSR chain, but is also not betting on an unproven concept with no Item 19 history to underwrite against.
Why this matters for a 2027 buy-or-build decision: Bruster's occupies a specific shelf position — above Dairy Queen's commodity soft-serve, below boutique gelaterias charging $8+ a scoop — and that position is durable but not elastic. It works when the surrounding trade area has enough daytime and evening foot traffic to fund a six-month operating season that has to cover twelve months of debt service, lease, and labor. The "open" decision is really a bet on a specific site's demographics plus a specific operator's willingness to work 50-60 hours a week on-site through peak months, not a bet on the brand name alone. A franchisee opening in a cold-climate market without a strong captive summer population — think a beach town, a boardwalk, or a dense family suburb with youth sports leagues — is fighting the model's underlying seasonality rather than riding it.
Treat the evaluation the way a RevOps function would treat a new revenue channel: AUV is a top-line forecast, the 5% royalty plus 3% marketing fee is a fixed take-rate layered on top of your gross like a channel partner fee, and your labor/COGS lines are the controllable levers. Franchisors publish Item 19 numbers precisely so a buyer can run that model before signing — skipping the modeling step is the single most common reason an otherwise capable operator underperforms the system average. A buyer who builds a simple revenue-and-cost funnel — gross sales in, COGS and labor out, royalty and marketing off the top, rent and opex below that — before ever touring a site is already ahead of most first-time franchisees, who tour sites first and model economics second, if at all.
The adjacent lens worth borrowing from B2B sales operations is pipeline-stage discipline: just as a RevOps leader won't let a deal skip qualification and jump straight to contract, a prospective franchisee shouldn't let site enthusiasm skip past unit economics. The site that "feels right" because of a great corner lot still has to clear the same AUV-against-debt-service test as every other candidate, and the FDD's own historical data is the qualification stage most buyers rush past.
The step-by-step process
A disciplined path from "interested" to "open" runs roughly 90 days once you commit to serious diligence, and skipping steps is where most bad decisions get locked in:
- Self-qualify capital and credit — confirm $500,000+ liquid, a 740+ credit profile, and a preliminary conversation with an SBA 7(a) lender that has actually underwritten food-service franchises before (Live Oak Bank and Huntington National Bank both publish franchise-specific criteria).
- Request the FDD directly from the franchisor. Receipt starts the FTC-mandated 14-day cooling-off period before you can sign anything.
- Call 15-20 existing franchisees from the FDD's Item 20 exhibit list — not just the three the franchisor suggests. Ask what their Year-1 AUV was against the system average, what surprised them, and whether they'd sign again.
- Select a site with a retail broker experienced in food-service pads — traffic counts, daytime population, and visibility from the road matter more than rent per square foot.
- Attend Discovery Day at franchisor headquarters: commissary tour, leadership meetings, product tasting, and ideally a ride-along at an existing regional unit.
- Build a five-year P&L at three AUV scenarios (bottom-quartile, system average, top-quartile) and run debt-service coverage at your proposed loan terms before falling in love with any one number.
- Engage a franchise attorney to negotiate territory protection, transfer rights, renewal terms, and post-term non-compete language — this is not a step to skip to save a few thousand dollars.
- Lock lender commitment, sign, and kick off construction, targeting an opening date early enough in spring to capture the full first season rather than losing six to eight peak weeks to a late build.
The step most buyers underweight is the franchisee call list. A franchisor's suggested references are, unsurprisingly, its happiest operators; the real diligence signal comes from reaching units in a different region, a different build vintage, and ideally a unit that's changed hands. Ask directly about off-season staffing, whether the commissary's batch-freezer training was sufficient, and what their actual COGS percentage ran versus the FDD's modeled range — that last number alone separates an optimistic pro forma from a lived one.
Costs, timelines, and typical ranges
The cost stack behind the FDD's $409,000–$2,644,060 total investment range breaks down into a handful of major lines, and where you land in that range depends almost entirely on whether you're building ground-up, converting existing space, or buying a resale:
| Line item | Typical range | Driver |
|---|---|---|
| Initial franchise fee | $30,000–$40,000 | Single unit; multi-unit deals run lower per store |
| Building construction (ground-up) | $0–$1,400,000 | Only applies to freestanding new builds |
| Leasehold improvements | $130,000–$400,000 | Walk-in freezer, batch room, counter build-out |
| Equipment | $170,000–$320,000 | Batch freezers are the core capital expense |
| Signage, POS, opening inventory | $40,000–$85,000 | Drive-thru boards, point-of-sale system, starting supplies |
| Working capital reserve | $24,000–$60,000 | Must cover off-season payroll in the slowest months |
Ongoing costs run a 5% royalty on gross sales plus a 3% national marketing fee — an 8% combined take-rate off the top before you touch cost of goods or labor. System-wide AUV sits at $673,438, with top-quartile stores clearing roughly $950,000 and bottom-quartile stores closer to $420,000. Against that revenue, cost of goods typically runs 28-32% (dairy-cream pricing is the volatile input), labor runs 24-28%, and rent/occupancy another 8-12%, leaving an EBITDA margin in the 12-15% band for a typical operator and up to 18% for strong ones. That translates to roughly $80,000-$101,000 in estimated owner earnings before taxes and debt service.
Payback timelines vary sharply by acquisition path: a ground-up freestanding build with drive-thru typically pays back in 4-7 years, while converting existing retail space or buying a resale of an already-profitable unit can pay back in 2-4 years because you skip the construction cost and the ramp-up period entirely. Breakeven in Year 1 is a realistic target for an absentee-managed freestanding build in a strong market, but that assumes the site performs near system average from day one — a slow first season can push breakeven into Year 2 regardless of the underlying model.
It's worth sizing Bruster's against adjacent capital-intensity tiers so the $500K-plus minimum reads in context. A mobile ice cream truck franchise like Kona Ice runs $157,000-$201,000 with no real estate and a flat monthly royalty rather than a percentage — a fundamentally different risk profile that trades upside for a much lower floor. A kiosk-format competitor like Jeremiah's Italian Ice sits at $400,000-$700,000. On the other end, a drive-thru-only format like Andy's Frozen Custard runs $1.0M-$2.3M against a higher ~$1.4M+ AUV. Bruster's sits in the middle of that spectrum, which is exactly why the site-and-operator fit matters more here than at either extreme — the format is flexible enough (freestanding, in-line, non-traditional) that a mediocre site can still clear the franchise fee but never approach system-average AUV.
Financing timelines deserve their own line item, separate from the cost stack. An SBA 7(a) loan on a food-service franchise typically takes 60-90 days from application to funding once the lender has a completed FDD, a personal financial statement, and a site under contract or letter of intent — longer if the lender requires a completed appraisal on ground-up construction. Buyers who assume financing will close in two weeks routinely blow their spring opening window waiting on paperwork that was entirely predictable.
Where teams get it wrong
The failure modes in this category are predictable and repeat across franchisees who skip the same diligence steps:
- Building ground-up in a short season. A freestanding build north of the Mason-Dixon line has to service debt on a build that may have cost $1.8M-$2.2M through a five-month dead season. Operators have closed for winter and never reopened because the math only worked at full-season volume.
- Undercapitalizing working capital. An owner who finances the full construction budget but leaves only $50,000 in reserve has no buffer against a single bad month — a rained-out July can drop cash to zero fast in a seasonal business.
- Going absentee without a strong general manager. Teen-and-college-age crews need active supervision; without it, portioning inconsistency and waste push COGS above 35%, erasing most of the margin.
- Picking the wrong site type. An end-cap in a power center without road visibility underperforms a freestanding pad with a drive-thru, because ice cream is overwhelmingly an impulse purchase that depends on being seen, not sought out.
- Freezing menu pricing through a cost spike. Dairy cream commodity costs moved sharply in both 2022 and 2025; operators who refused to raise scoop pricing in step compressed their own margin instead of passing the cost through.
- Treating local marketing as optional. The 3% national marketing fee funds brand-level awareness, not local foot traffic; franchisees who skip school-fundraiser nights, little-league sponsorships, and a basic local social presence leave the single highest-ROI acquisition channel for a scoop shop untouched.
The RevOps parallel is direct: every one of these is a forecasting or incentive-alignment failure, not a brand failure. A franchisee who treats royalty, COGS, and labor as a controllable cost stack — reviewed monthly against the FDD's own Item 19 benchmarks — catches a margin slide in week three instead of discovering it at tax time. One without that discipline is flying on vibes until the bank statement forces a reckoning. The same instinct that drives a sales operations team to build a weekly pipeline-coverage dashboard should drive a franchisee to build a weekly labor-percentage-against-sales dashboard; the cadence, not the industry, is what catches the problem early.
A less-discussed failure mode worth naming: underestimating the commissary and supply-chain dependency. Because batch-freezing happens on-premises from franchisor-specified mix and flavorings, a franchisee who doesn't build a redundant ordering relationship with the approved distributor risks stockouts during peak weekends — the exact moment a stockout costs the most in lost impulse sales.
Decision framework: when to choose what
The operator profile that wins with Bruster's looks consistent: $500K+ liquid net worth, a Sunbelt or Mid-Atlantic destination-retail site with 300+ scoop-weather days a year, a freestanding pad with drive-thru and 40+ parking spots, and an owner willing to work the counter 50-60 hours a week through peak season. Multi-unit operators with three or more stores unlock general-manager leverage and commissary-ordering efficiencies that a single-unit absentee owner can't reach — the fixed overhead of a strong GM and a trained assistant manager amortizes much better across three units than one.
If that profile doesn't fit your capital, geography, or risk tolerance, the adjacent franchise categories worth comparing before you commit are worth a side-by-side look: Andy's Frozen Custard runs a higher AUV (~$1.4M+) on a drive-thru-only format with a steeper $1.0M-$2.3M build; Jeremiah's Italian Ice offers a lower $400,000-$700,000 entry with kiosk and storefront formats; Rita's Italian Ice sits in a similar $200,000-$650,000 range with a mature Mid-Atlantic footprint; Kona Ice's mobile-truck model runs $157,000-$201,000 with a flat monthly royalty instead of a percentage; and buying an existing, profitable Bruster's unit on the resale market typically trades at 2.5-3.5x seller's discretionary earnings — often the fastest path to positive cash flow because you skip the ramp-up entirely.
A buyer weighing the open-versus-buy question should also weigh it against entirely different capital deployments with comparable risk: a single-tenant net-lease retail property, a laundromat, or a car wash franchise all compete for the same $500K-$1M liquidity and all carry their own seasonality and labor profiles. Ice cream's advantage over most of those alternatives is a genuinely high gross margin on product (dairy mix costs a fraction of menu price) and low SKU complexity; its disadvantage is the hard seasonality ceiling that a car wash or laundromat doesn't share to the same degree.
Related questions
What's the minimum net worth to qualify, versus the minimum liquid capital? Lenders typically want $1.5M+ total net worth alongside the $500,000 liquid minimum, since liquid cash covers the fee and build while total net worth supports loan underwriting and personal guarantees.
Does Bruster's offer financing directly? The franchisor does not typically lend directly; franchisees arrange third-party financing, most often SBA 7(a) loans through lenders with existing franchise underwriting programs.
How does a resale differ from a new build financially? A resale buys an already-ramped, profitable unit at a seller's discretionary earnings multiple, skipping construction risk and the slow first-season ramp that new builds absorb.
Can one owner run a Bruster's part-time? Only with a strong, well-compensated general manager in place; a true absentee model adds roughly $70,000/year in management salary and typically trims margin by several points.
How seasonal is the revenue really? Most units generate 70-80% of annual revenue in the five warm-weather months, which is why working capital reserves and off-season fixed-cost management matter more here than in a year-round QSR concept.
FAQ
What is the total investment range for a Bruster's franchise in 2027? The 2026 FDD lists a total initial investment between $409,000 and $2,644,060, depending on whether you build freestanding, convert existing space, or buy a resale.
How much liquid capital do I need to qualify? At least $500,000 in unencumbered liquid capital, enough to cover the franchise fee, build-out, and a working capital cushion without relying entirely on borrowed funds in year one.
What are the ongoing royalty and marketing fees? A 5% royalty on gross sales and a 3% marketing fee, an 8% combined take-rate that's standard for the category.
What is the average unit volume for Bruster's franchises? System-wide AUV was $673,438 in the most recent FDD, with top performers exceeding $950,000 and newer or seasonal stores running closer to $420,000.
How long does it take to break even and pay back the investment? Breakeven in Year 1 is realistic for a well-run freestanding build; payback runs 4-7 years for ground-up construction and 2-4 years for conversions or resales.
What are typical owner earnings for a franchisee? At a 12-15% EBITDA margin, franchisees have reported roughly $80,000-$101,000 in annual owner earnings before taxes and debt service, with results varying by location and management quality.
Sources
- FDD Exchange — Bruster's Real Ice Cream FDD archive (fddexchange.com)
- Sharpsheets — Bruster's Real Ice Cream Franchise FDD, Profits & Costs (sharpsheets.io)
- FranchisePayback — Bruster's Real Ice Cream FDD, Costs & Fees (franchisepayback.com)
- VettedBiz — Bruster's Franchise Insights: FDD, Costs & Fees (vettedbiz.com)
- IBISWorld — Ice Cream Stores in the US Industry Report (ibisworld.com)
- International Franchise Association — Franchise Economic Outlook (franchise.org)
- Restaurant Business Magazine — Frozen Dessert Category Coverage (restaurantbusinessonline.com)
- Franchise Times — Top 400 Rankings (franchisetimes.com)
- U.S. Small Business Administration — Franchise Directory (sba.gov)
- U.S. Bureau of Labor Statistics — Business Employment Dynamics (bls.gov)
Related on PULSE
- Should I open or buy a Sub Zero Nitrogen Ice Cream franchise in 2027?
- Should I open or buy a MaggieMoo's Ice Cream franchise in 2027?
- Should I open or buy a Carvel ice cream franchise in 2027?
- How Many Employees Should I Schedule Each Shift at My Ice Cream Shop?
- How Do I Budget an Ice Cream or Gelato Shop Buildout?
- How do you start an artisanal ice cream shop business in 2027?
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-qHow do you coach a veteran rep who's coasting in 2026?
 pulse-qShould I open a real estate photography business in 2027?
 pulse-qHow Do I Get Out of a Commercial Lease Early Without Paying a Fortune in 2026?
 pulse-qHow Do I Negotiate a Lease and Buildout for a Private or Charter School in 2026?
 pulse-qHow Many Tellers Should I Schedule Each Day at My Bank Branch in 2026?
 pulse-qHow do you follow up on coaching so it actually changes behavior in 2026?
 pulse-qHow Do I Budget a Med Spa Buildout in 2026?
 pulse-qShould I open or buy a Mr. Handyman franchise in 2027?
 pulse-qHow do you coach a rep who keeps missing quota in 2026?
 pulse-qHow do you coach a rep who over-relies on one big deal in 2026?