
Top 10 Sales KPIs for Managed Detection & Response (MDR) Security Services in 2027
 Curated byKory White · Fractional CRO · Maryland
 PULSEKNOWLEDGE LIBRARY
Quality
Certified
The 10 best sales kpis for managed detection & response (mdr) security services are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1. MDR ARR per Endpoint
ARR per Endpoint ranks first because it is the single denominator that reconciles MDR's dual cost stacks — software licenses and 24x7 analyst hours — against one invoice. Best-in-class providers realize $48-144 per endpoint per year, roughly $4-12 monthly, with CrowdStrike Falcon Complete at the top of that band because it bundles its own EDR substrate.
This KPI is for CROs and pricing owners who must defend gross margin in the 55-70% range that MDR structurally supports, versus 75-85% for pure SaaS. It trades away simplicity: per-endpoint pricing gets messy once cloud workloads and identity telemetry enter the envelope. Tracked monthly, a sub-$3 ARR per endpoint signals a customer demanding premium service at commodity pricing, which is the earliest warning that the unit economics are inverting.
2. MDR Mean Time to Detect
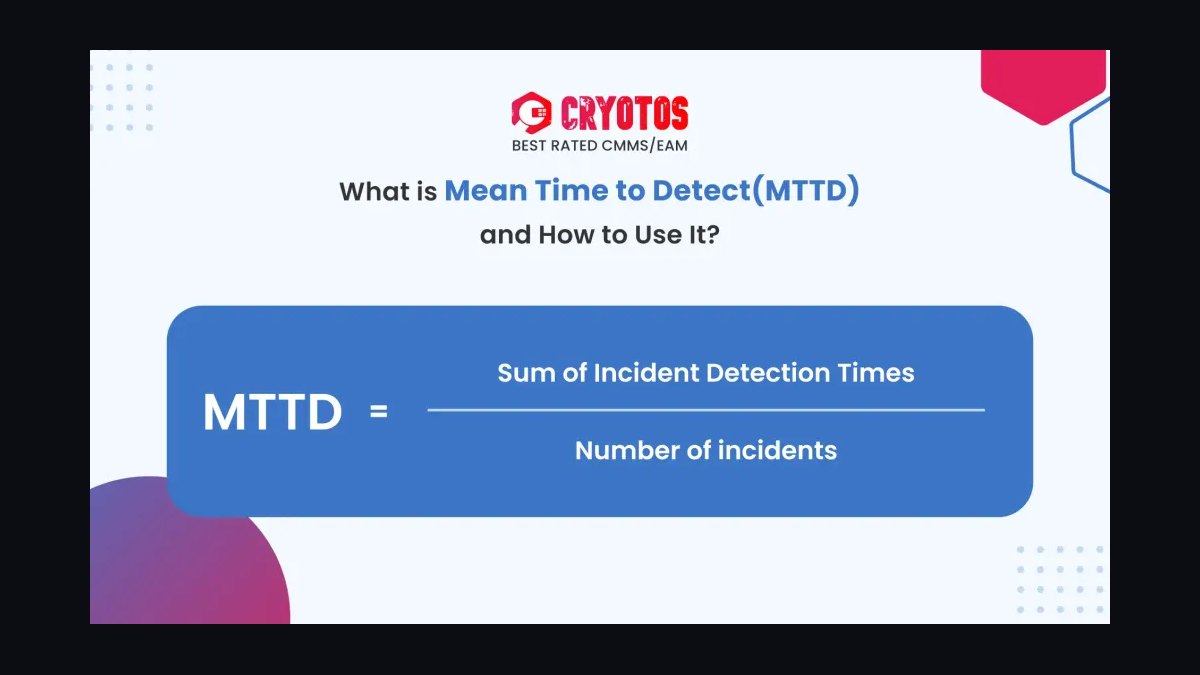
Mean Time to Detect ranks second because detection latency is the actual product MDR sells, not a feature of it. Industry SLAs typically commit to 15 minutes, while top-quartile providers including Falcon Complete, ReliaQuest, and eSentire operate under 5 minutes for high-fidelity detections. MTTD exceeding 30 minutes correlates with roughly 3x higher churn risk, since customers benchmark against publicly reported breach dwell times.
This metric is for SOC operations leaders and customer-success teams who need a leading indicator measured in minutes rather than a lagging one measured at renewal. It trades away comfort: aggressive MTTD targets force investment in tuning and automation that pure headcount cannot deliver. Compared with MTTR directly below it, MTTD is the earlier signal — detection failures surface before containment failures, and they surface in the customer queue, not the board deck.
3. MDR Mean Time to Respond
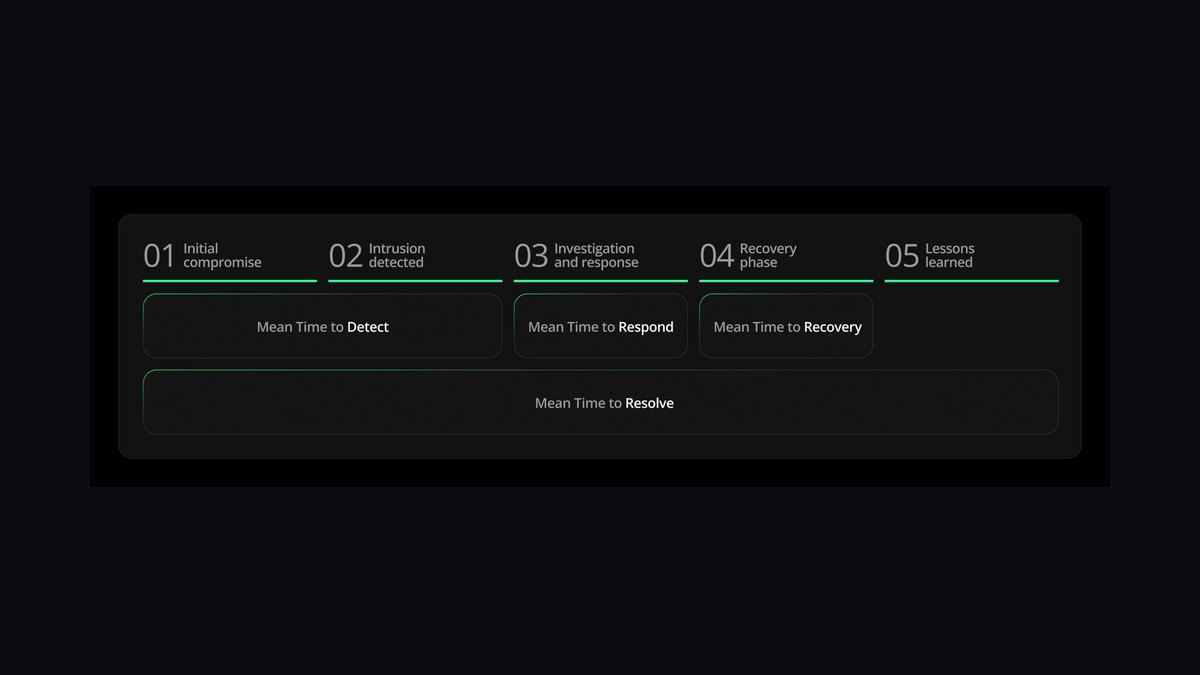
Mean Time to Respond ranks third because containment speed is the best single leading indicator of renewal, showing up in customer-success notes 60-90 days before cancellation. Median SLAs commit to 60 minutes from confirmed detection to containment action, while Mandiant Managed Defense and CrowdStrike publish medians under 25 minutes for critical-severity events. Top-quartile providers deliver under 30 minutes across the critical tier.
This KPI is for service-delivery leaders and renewal owners who need to know whether trust is compounding or eroding. It trades away headroom: pushing MTTR below 30 minutes requires SOAR automation and auto-containment authority that many customers resist granting initially. Against MTTD above it, MTTR is the later but more decisive number — a deteriorating MTTR predicts a lost renewal even when detection latency stays inside SLA.
4. MDR Net Revenue Retention
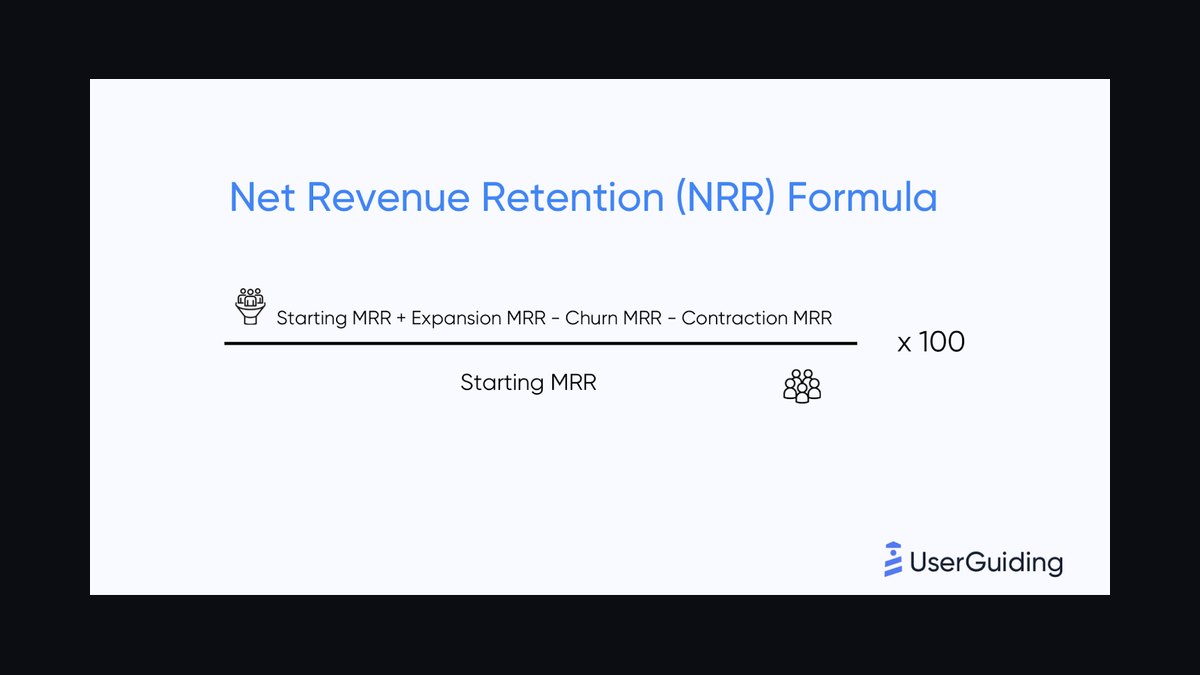
Net Revenue Retention ranks fourth because it captures whether the MDR book compounds through expansion or merely survives through retention. Best-in-class providers run 92-95% gross retention and 115-130% net retention; CrowdStrike Falcon Complete publicly reports 124% NRR, while Arctic Wolf and ReliaQuest land in the 110-118% range. Weaker channel-only providers run 95-105% NRR with 85-90% GRR.
This KPI is for CFOs, boards, and CROs evaluating whether the land-and-grow motion actually functions after signature. It trades away short-term optics: expansion requires post-sale investment in tuning and customer health that new-logo quotas do not reward.
5. MDR ACV by Segment
Annual Contract Value by Segment ranks fifth because it confirms sales is winning the segment the company priced and staffed for. Mid-market deals of 200-2,000 employees run $35-150K ACV, enterprise of 2,000-10,000 employees runs $200-800K, and large enterprise often exceeds $2M. Sophos MDR's mid-market median reportedly sits near $45K, while Mandiant Managed Defense's enterprise median is north of $400K.
This KPI is for revenue-operations leaders and segment owners who need to detect packaging commoditization early. It trades away blended simplicity: segment-level tracking requires clean CRM attribution and disciplined deal-desk rules. Compared with Win Rate vs. SIEM-Only directly below it, ACV shows the price achieved while win rate shows the competitive context — mid-market reps closing $20K deals are evidence packaging is being commoditized, not evidence of a pricing problem.
6. MDR Win Rate vs SIEM-Only
Win Rate against SIEM-Only and DIY SOC ranks sixth because it measures competitive viability against the alternative customers actually consider. Healthy MDR providers run 65-80% win rates in these bake-offs; market leaders including Falcon Complete and Arctic Wolf push past 80% on inbound opportunities. Falling win rates against Microsoft Sentinel plus Defender XDR, the free-with-E5 alternative, are a packaging warning rather than a sales warning.
This KPI is for competitive-intelligence and product-marketing teams who must distinguish execution problems from positioning problems. It trades away clean attribution: DIY SOC deals are often lost to budget deferral rather than a named competitor, muddying the denominator. Compared with SOC Analyst Productivity below it, win rate is the external signal while productivity is the internal one — a provider can win the deal and still fail to deliver it profitably.
7. MDR SOC Analyst Productivity
SOC Analyst Productivity ranks seventh because the MDR margin model only works when analyst leverage stays above roughly seven accounts each. Tier 1 analysts at scaled providers cover 5-10 customer accounts and handle 15-30 alerts per hour after tuning; ReliaQuest publicly emphasizes GreyMatter automation specifically because that math must hold. Drop below five accounts per analyst and the unit economics invert; push past twelve and MTTR drifts measurably.
This KPI is for SOC managers and capacity planners who own the largest cost line in the P&L. It trades away service intimacy: higher account-per-analyst ratios mean less context per customer, which shows up in NPS before it shows up in churn. Compared with Time-to-Tuned below it, productivity is the steady-state measure while tuning latency is the onboarding measure — both feed the same margin equation from opposite ends of the customer lifecycle.
8. MDR Time-to-Tuned Onboarding
Time-to-Tuned, sometimes called onboarding net revenue time, ranks eighth because onboarding is where the sales motion either earns the renewal or burns it. Top-quartile providers reach a fully tuned alert pipeline with false-positive rate under 15% in 14-21 days; the segment median is 30 days. Each day beyond 30 increases first-year churn risk by roughly 1%, making this the most controllable early-lifecycle lever.
This KPI is for sales-engineering leaders and onboarding managers whose compensation should be tied to it. It trades away speed in the sales cycle: aggressive tuning timelines require pre-sales scoping discipline that slows signature on complex environments. Compared with Sales Quota Attainment below it, time-to-tuned is the operational handoff metric while quota attainment is the commercial one — a provider can hit quota and still lose the account to a 60-day onboarding.
9. MDR Sales Quota Attainment
Sales Quota Attainment by Motion ranks ninth because it separates new-logo execution from expansion execution, which fail for different reasons. Healthy organizations land 55-65% of reps at quota, with top-decile attainment exceeding 150%; new-logo AEs carry $1-3M ARR targets while expansion AEs carry $800K-$1.5M. CrowdStrike runs a dedicated Falcon Complete Specialist overlay because the motion is technical enough to need one.
This KPI is for CROs and sales-operations leaders who need to spot motion-specific breakdowns before they compound. It trades away blended reporting: splitting new-logo from expansion requires separate quota plans, territories, and compensation structures. Compared with Net Revenue Retention above it, quota attainment is the leading commercial indicator while NRR is the trailing cohort outcome — expansion attainment below 70% predicts an NRR collapse roughly two quarters out.
10. MDR Gross Revenue Retention
Gross Revenue Retention ranks tenth because it isolates churn and downgrade damage from the expansion that can mask it. Best-in-class MDR providers hold 92-95% GRR, while sub-scale providers under $100M ARR should target 88-92% because they cannot match leader brand strength. Anything under 85% GRR for two consecutive quarters is an existential signal that typically precedes acquisition or restructuring within 18 months.
This KPI is for boards and finance leaders who need the unvarnished retention number before expansion flatters it. It trades away the comforting headline: NRR of 115% can coexist with 85% GRR, meaning the installed base is bleeding while a few large expansions hide it. Compared with Net Revenue Retention above it, GRR is the floor and NRR is the ceiling — track both or the expansion number will eventually lie to you.
How we ranked these
We ranked the nine MDR sales KPIs by weighting three factors: revenue impact (40%), predictive power for retention (35%), and measurability in a standard CRM plus SOC tooling stack (25%). ARR per Endpoint, GRR/NRR, and MTTR scored highest because they move enterprise value fastest and are visible weekly. Win rate and quota attainment were weighted next, then onboarding latency and analyst productivity as leading operational indicators.
We deliberately excluded vanity metrics like raw pipeline value, logo counts, and total alerts processed, because they inflate without improving unit economics. We also ignored NPS as a standalone KPI since it lags churn by two quarters, and skipped MQL volume because MDR buying committees now include CFOs and auditors, making lead-stage metrics poor predictors of closed revenue.
What to look for
What matters most is whether the vendor's SLA is operationally real, not contractual. Ask for 90-day MTTD and MTTR medians by severity, not marketing benchmarks. Then verify analyst leverage: accounts per Tier 1 and alerts per hour post-tuning. A provider at four accounts per analyst cannot sustain premium pricing, and you will feel it in renewal negotiations within 18 months.
The mistake most buyers make is choosing on EDR brand or per-endpoint price alone. MDR margin lives in tuning quality and onboarding speed, so a cheaper per-endpoint rate with a 45-day time-to-tuned destroys first-year value. Buyers also over-index on detection counts and under-index on containment authority. Ask who can isolate a host at 3 a.m. without a customer approval loop.
Related questions
How is ARR per endpoint calculated for MDR services?
Divide total recurring subscription revenue by the count of protected endpoints, servers, and cloud workloads under contract, then annualize. Best-in-class MDR providers realize $48-$144 per endpoint per year. Track it monthly by cohort and segment, because a blended number hides the sub-$3 accounts that demand premium service at commodity pricing and quietly destroy gross margin.
Why does MTTR predict MDR renewals better than MTTD?
MTTD proves the platform works; MTTR proves the provider can act. Customers tolerate a slightly slower detection if containment is fast and decisive. When MTTR drifts past 60 minutes, customer-success notes show trust erosion 60-90 days before cancellation. Track MTTR medians and 95th percentiles by severity weekly, not quarterly.
What GRR and NRR should an MDR provider target?
Best-in-class MDR runs 92-95% gross revenue retention and 115-130% net revenue retention. CrowdStrike Falcon Complete publicly reports 124% NRR. Sub-scale providers under $100M ARR should still target 88-92% GRR and 105%+ NRR. Anything below 85% GRR for two consecutive quarters signals a business-model problem, not a sales-execution problem.
How many accounts should one Tier 1 SOC analyst cover?
Scaled MDR providers run 5-10 customer accounts per Tier 1 analyst, handling 15-30 alerts per hour after tuning. Below five accounts per analyst, unit economics invert and pricing cannot stay market-comparable. Above twelve, MTTR drifts and customers feel the deterioration. The path up is SOAR automation and ML-driven triage, typically an 18-24 month investment cycle.
What is a healthy time-to-tuned for MDR onboarding?
Top-quartile providers reach a fully tuned alert pipeline with false-positive rate under 15% in 14-21 days. The segment median is 30 days. Each day beyond 30 increases first-year churn risk by roughly 1%. Tie sales-engineer compensation to onboarding latency, because onboarding is where the sales motion either earns the renewal or burns it before the first QBR.
How should MDR providers price cloud-heavy versus endpoint-heavy customers?
Endpoint-heavy environments price cleanly per endpoint at $4-$12 per month. Cloud-heavy environments with Kubernetes, ephemeral workloads, and identity-first architecture break that model and migrate toward hybrid pricing: per workload, per identity, and per ingest gigabyte. Providers that have not rebuilt their order form for cloud-heavy accounts lose 5-10 margin points absorbing unlimited telemetry.
What discount ceiling is defensible on new-logo MDR deals?
Twenty percent off list is defensible for committed multi-year deals with usage floors. Beyond 25%, the problem is packaging or competitive positioning, not deal-specific concession. Mid-market deals discounted over 30% on average produce ACVs that fail to recover customer-acquisition cost within 18 months, which is where LTV/CAC math stops working at MDR gross margins.
Which expansion motion drives the most MDR net revenue retention?
Workload coverage expansion, adding cloud, identity, or OT/IoT onto an existing endpoint contract, is highest leverage because the analyst already knows the environment and marginal gross margin exceeds 75%. Tier upgrades to threat hunting or incident-response retainers rank second. Seat expansion is the easiest to forecast but the lowest-leverage of the three.
FAQ
How does MDR pricing scale for cloud-heavy versus endpoint-heavy customers?
Endpoint-heavy environments price cleanly per endpoint at $4-$12 monthly. Cloud-heavy environments with Kubernetes clusters, ephemeral workloads, and identity-first architecture break the per-endpoint model and migrate toward hybrid per-workload, per-identity, and per-ingest-GB pricing. Providers that have not rebuilt their order form for cloud-heavy customers lose 5-10 margin points absorbing the ingest cost on platforms like Microsoft Sentinel.
What MTTR target makes sense for mid-market customers without 24x7 internal coverage?
Sixty minutes for critical-severity events is the published industry SLA and most mid-market buyers accept it on paper. Operationally, 30 minutes is the threshold where customers trust the provider enough to skip building a night shift. Beyond 60 minutes, customers conclude they need an internal SOC anyway, and churn risk rises sharply within two renewal cycles.
How do I benchmark SOC analyst productivity against public MDR leaders?
Falcon Complete, ReliaQuest, and Arctic Wolf operate at 7-10 customer accounts per Tier 1 analyst at scale, with 20-30 alerts per hour post-tuning. Below five accounts per analyst, unit economics cannot support market-comparable pricing. The path up is automation investment in SOAR playbooks, auto-containment, and ML-driven triage, typically 18-24 months of capital expenditure to move from four to eight accounts per analyst.
What is the right discount ceiling for new-logo MDR deals?
The defensible ceiling is 20% off list for committed multi-year deals with usage floors. Anything beyond 25% signals a packaging or competitive-positioning problem rather than a deal-specific concession. Mid-market deals discounted more than 30% on average produce ACVs that fail to recover customer-acquisition cost in 18 months, the threshold where LTV/CAC math stops working at MDR gross margins.
How should I think about expansion in MDR: seats, workloads, or tier upgrades?
All three matter, but workload coverage expansion, adding cloud, identity, or OT/IoT onto an existing endpoint contract, is highest leverage because the analyst already knows the environment and marginal margin exceeds 75%. Tier upgrades to threat hunting or IR retainers rank second. Seat expansion is the easiest to forecast but the lowest-leverage of the three.
What churn benchmark is defensible for a sub-scale MDR provider?
Sub-scale providers under $100M ARR should target 88-92% GRR, a few points below market leaders because they cannot match brand-strength retention. NRR should still target 105%+ on the strength of expansion, which depends on land-and-grow discipline more than scale. Anything under 85% GRR for two consecutive quarters is an existential signal.
Why is win rate against Microsoft Sentinel and Defender XDR a packaging warning?
Microsoft bundles Sentinel and Defender XDR with E5 licenses, so buyers perceive the alternative as free. Falling win rates against that bundle usually mean your packaging does not clearly justify the incremental spend. The fix is ROI proof: saved analyst FTEs, insurance premium reductions, and mean time to contain, not feature comparisons against a platform the customer already owns.
How often should an MDR provider review pricing?
Run a formal pricing review quarterly, testing plus or minus 10% list movement against win-rate impact by segment. Annual repricing is too slow given how fast Microsoft, CrowdStrike, and Arctic Wolf shift packaging. The quarterly review should also audit discount distribution, package mix shift, and telemetry envelope overage rates, because those three variables drive gross margin more than headline list price.
What is the biggest operational failure mode in MDR sales?
Selling enterprise SLAs at mid-market prices. Sales teams that win mid-market deals by promising 15-minute MTTD and 30-minute MTTR with named-analyst dedication cannot deliver against unit economics. The result is three quarters of NPS decline followed by mass churn. Productize the SLA tier and stop negotiating it deal-by-deal, even when it costs you a quarter-end close.
How should onboarding latency be tied to sales compensation?
Tie sales-engineer variable compensation directly to time-to-tuned, measured as days from signature to false-positive rate under 15%. Each day beyond 30 increases first-year churn risk by roughly 1%, so onboarding latency is a revenue metric disguised as an operations metric. Paying SEs on closed-won alone rewards fast signatures that create slow, churn-prone customers.
Sources
- https://www.gartner.com/en/documents/4026899
- https://www.forrester.com/report/the-forrester-wave-managed-detection-and-response-q1-2026/RES180123
- https://www.idc.com/getdoc.jsp?containerId=US52076425
- https://ir.crowdstrike.com/financials/quarterly-results/default.aspx
- https://investors.sentinelone.com/financials/quarterly-results/default.aspx
- https://news.sophos.com/en-us/2024/10/21/sophos-completes-acquisition-of-secureworks/
- https://www.servicenow.com/company/media/press-room/servicenow-acquires-expel.html
- https://cloud.google.com/blog/topics/threat-intelligence/m-trends-2026
- https://www.reliaquest.com/greymatter/
- https://www.arcticwolf.com/resources/
Related on PULSE
- [More sales kpis for managed detection & response (mdr) security services rankings and buying guides](/knowledge)
- [PULSE Tools and calculators](/tools)
- [Everything on PULSE RevOps](/)
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
 pulse-industry-kpisTop 10 Sales KPIs for Telehealth Platform Services in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Elevator and Escalator Service in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Dental Practice Sales in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Laboratory Diagnostics in 2027
 pulse-industry-kpisTop 10 KPIs for Tire Shops in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Modular and Prefab Construction in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Acoustical Ceiling & Wall Panel Contracting in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Medical Device Sales in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Document Shredding and Records Management in 2027
 pulse-industry-kpisTop 10 Sales KPIs for equine breeding in 2027