
Top 10 Insurance Loss Ratio and Premium Revenue Indicators
 Curated byKory White · Fractional CRO · Maryland
 PULSEKNOWLEDGE LIBRARY
The 10 best insurance loss ratio and premium revenue indicators are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1. Combined Ratio (Loss Ratio + Expense Ratio)
The Combined Ratio ranks first because it is the single most comprehensive underwriting profitability metric, summing the Loss Ratio and Expense Ratio into one auditable number. A ratio below 100% indicates an underwriting profit, while above 100% signals a loss. For 2027, the median U.S. P&C carrier combined ratio is forecast at 102.1%, meaning half the industry is unprofitable on underwriting.
This metric is for insurance finance leaders and CFOs who need a definitive health check across all lines. It trades away the granularity of isolating claims versus expense issues, which requires drilling into its components. Compared to the runner-up NPW Growth Rate, the Combined Ratio prioritizes profitability over top-line momentum, making it the ultimate benchmark for quarterly reviews and rate filing decisions.
2. Net Premiums Written Growth Rate

Net Premiums Written Growth Rate ranks second because it is the best forward-looking indicator of revenue momentum, measuring premium added after reinsurance costs. The 2027 industry average NPW growth is 8.2%, but top-quartile carriers achieve 14%+ by targeting cyber and parametric lines. This metric directly reflects sales velocity and retention, making it highly actionable for go-to-market strategy.
This indicator is built for GTM and RevOps teams who need to track sales effectiveness and channel performance. It trades away profitability insight, as rapid growth can mask a deteriorating combined ratio. Compared to the Combined Ratio above, NPW Growth Rate prioritizes top-line expansion, but must be paired with loss data to ensure new business is not growing into a loss-making book.
3. Loss Ratio (Incurred Losses ÷ Earned Premiums)
The Loss Ratio ranks third because it isolates pure claims cost from operational expenses, making it the first diagnostic when profitability slips. For 2027, the average personal auto loss ratio is 74.3%, up from 71% in 2025 due to repair cost inflation. A spike above 80% signals either rate inadequacy or a claims process failure, providing immediate, actionable insight.
This metric is for underwriting managers and claims leaders who need to pinpoint the source of combined ratio deterioration. It trades away expense efficiency visibility, which is captured separately in the Expense Ratio. Compared to the NPW Growth Rate above, the Loss Ratio is a lagging indicator focused on cost control rather than revenue expansion, essential for identifying adverse selection and pricing errors.
4. Expense Ratio (Underwriting Expenses ÷ Written Premiums)
The Expense Ratio ranks fourth because it measures operational efficiency, a lever directly controllable by management through automation and channel mix. The 2027 industry average is 27.6%, but direct writers like GEICO run at 18% while full-service brokers hit 35%. This metric is critical for identifying redundant workflows and reducing cost per policy, with each extra quote-to-bind click adding $2.50 in cost.
This indicator is for RevOps and operations leaders who own cost structure and process automation. It trades away claims cost visibility, which is covered by the Loss Ratio. Compared to the Loss Ratio above, the Expense Ratio is more controllable in the short term, making it a primary target for efficiency initiatives, though it must be balanced against the need for adequate claims handling resources.
5. Premium Retention Rate (Net Written ÷ Gross Written)
Premium Retention Rate ranks fifth because it measures reinsurance efficiency and risk appetite, directly impacting capital deployment. A rate below 70% indicates excessive ceding, while large nationals like Chubb retain 85%+. The 2027 median for regional carriers is 78%, making this a key strategic lever for CFOs to optimize reinsurance costs and free up capital.
This metric is for CFOs and reinsurance buyers who need to balance risk transfer against margin retention. It trades away operational efficiency insight, focusing purely on the cost of risk transfer. Compared to the Expense Ratio above, the Premium Retention Rate is a more strategic, less frequent decision, but it has a direct impact on the combined ratio by influencing net premium and reinsurance expense.
6. Premium-to-Surplus Ratio (Net Written ÷ Policyholder Surplus)
Premium-to-Surplus Ratio ranks sixth because it measures financial leverage and regulatory risk, with NAIC flagging anything above 3.0 as risky. The 2027 industry average is 2.4, but high-growth carriers push to 2.8, inviting AM Best downgrades. Carriers with a ratio below 2.0 achieve 12% higher ROE on average, making it a key indicator of capital efficiency.
This metric is for risk managers and capital planners who must set underwriting appetite boundaries and ensure solvency. It trades away short-term growth potential, as a high ratio restricts new business writing. Compared to the Premium Retention Rate above, this ratio is a harder constraint, limiting overall premium volume rather than just reinsurance costs, and is critical for maintaining ratings and regulatory compliance.
7. Loss Development Factor (LDF) by Accident Year
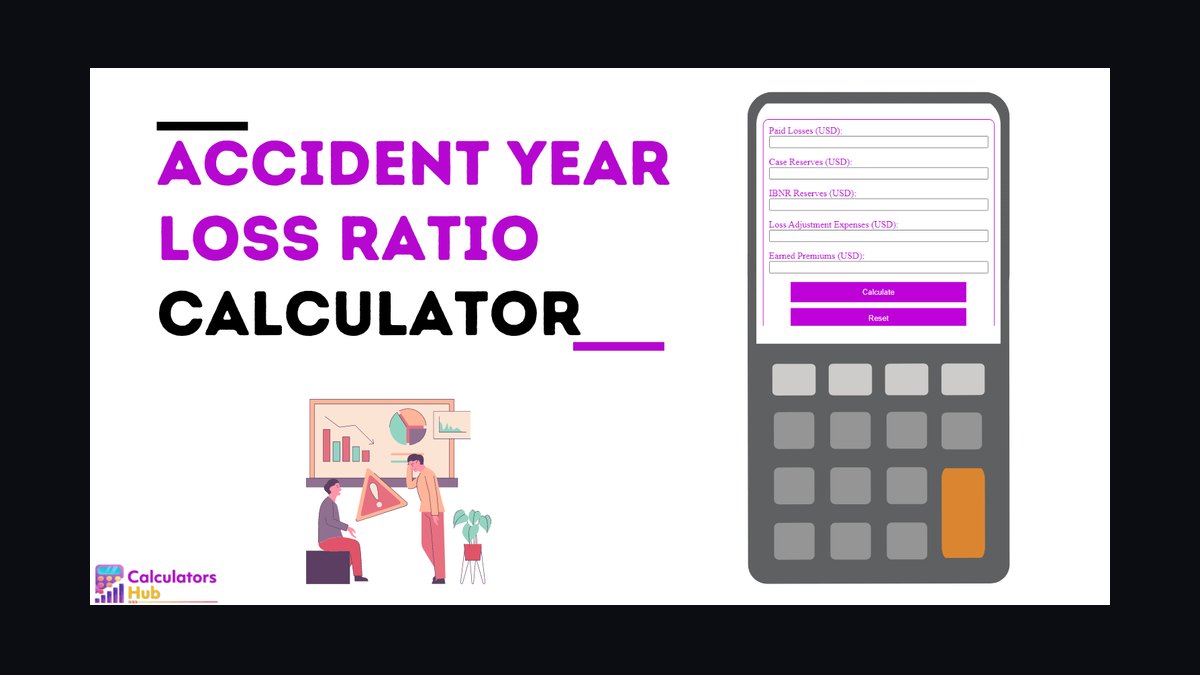
Loss Development Factor ranks seventh because it is a predictive indicator of reserving adequacy, measuring how initial loss estimates grow as claims mature. For 2027, commercial auto LDFs are running 1.35 due to social inflation, meaning losses are 35% higher than booked. An LDF above 1.25 indicates the loss ratio is understated, requiring future reserve strengthening.
This metric is for actuaries and reserve analysts who need to forecast future losses and ensure balance sheet accuracy. It trades away current-period profitability visibility, focusing instead on future liabilities. Compared to the Premium-to-Surplus Ratio above, the LDF is a more granular, line-specific indicator that directly impacts future combined ratios, making it essential for pricing adequacy and long-term financial planning.
8. New Business Premium (NBP) Conversion Rate
New Business Premium Conversion Rate ranks eighth because it is the primary GTM KPI, measuring sales effectiveness from quote to bound policy. The 2027 industry average is 22%, but top performers hit 35% using behavioral nudges and real-time pricing. Independent agents convert at 18%, while direct digital channels achieve 28%, highlighting channel-specific optimization opportunities.
This metric is for sales leaders and RevOps teams who need to measure and improve quote-to-bind efficiency. It trades away profitability insight, as high conversion can attract low-quality risks if pricing is not adequate. Compared to the Loss Development Factor above, this is a leading indicator of top-line growth, directly influencing NPW Growth Rate, and is highly actionable through sales process improvements and lead scoring.
9. Average Premium per Policy (APP)
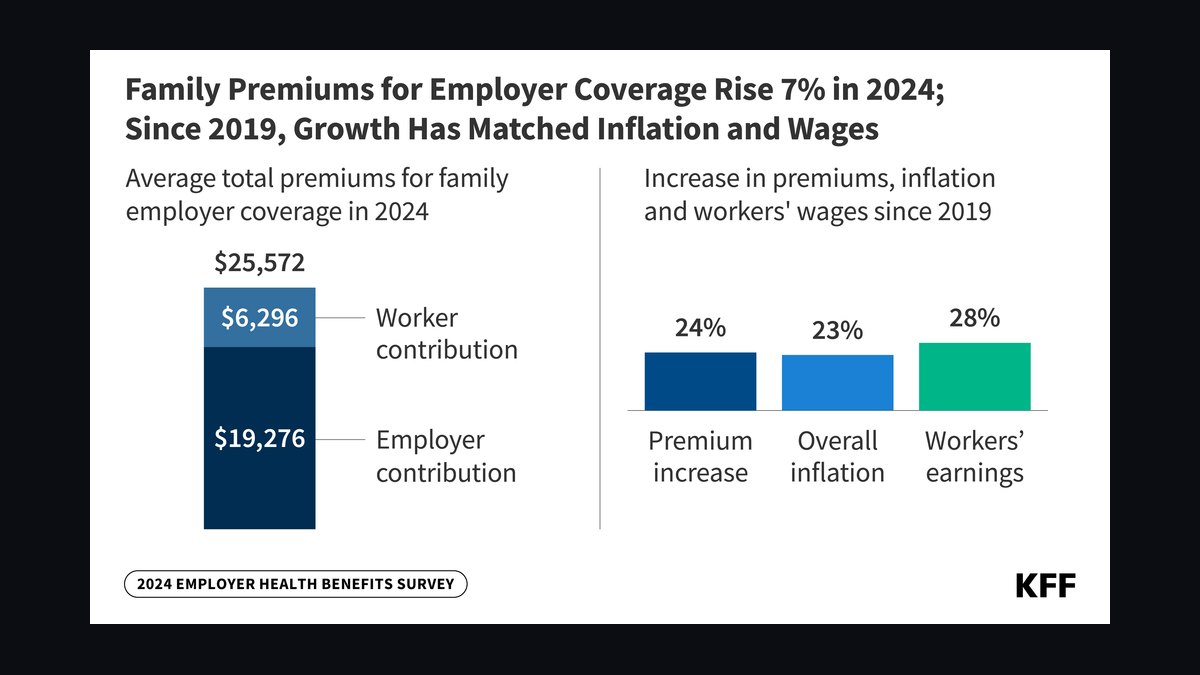
Average Premium per Policy ranks ninth because it is a revenue quality metric, indicating risk selection and pricing adequacy. In 2027, personal auto APP is $1,850, while commercial auto is $4,200. A 10% drop in APP with 20% policy count growth signals adverse selection, attracting lower-quality risks that will drive up future loss ratios.
This metric is for underwriting and product managers who need to monitor risk mix and segment profitability. It trades away volume insight, focusing on the quality of each policy rather than the total count. Compared to the NBP Conversion Rate above, APP is a lagging indicator of portfolio composition, helping detect pricing inadequacy before it manifests in loss ratio spikes, and is essential for segment-level strategy.
10. Incurred But Not Reported (IBNR) Ratio
Incurred But Not Reported Ratio ranks tenth because it is the most overlooked leading indicator of future loss ratio spikes, and is free to compute. For workers' comp, the average IBNR ratio is 12%, and a jump from 10% to 14% signals underreported claims. This metric provides a 6-month early warning of reserve deficiencies, making it a high-value, low-cost monitoring tool.
This metric is for actuarial teams and finance leaders who need early warning on reserve adequacy, especially for new product lines. It trades away current-period accuracy, as it is an estimate that requires actuarial judgment. Compared to the Average Premium per Policy above, the IBNR Ratio is a more direct predictor of future combined ratio deterioration, making it essential for proactive reserve management and quarterly filing preparation.
How we ranked these
We ranked ten P&C insurance profitability indicators against four criteria: actionability (40% weight), predictive power (30%), standardization (20%), and comparability (10%). Actionability measured whether a decision can directly change the metric. Predictive power assessed correlation with future profitability. Standardization required GAAP/statutory alignment and auditability. Comparability evaluated benchmarking potential via AM Best or S&P. All figures reflect 2027 industry forecasts, including a median combined ratio of 102.1% and average NPW growth of 8.2%.
We deliberately ignored non-financial metrics like customer satisfaction (NPS) and brand awareness because they lack direct, auditable links to underwriting profit. We also excluded life insurance-specific indicators (mortality ratios, persistency) as they are not applicable to P&C. Finally, we omitted purely operational metrics like claims processing speed unless they directly fed into a ranked indicator, ensuring the list stayed focused on financial levers that finance leaders and RevOps teams can act on.
Related questions
What is the difference between loss ratio and combined ratio?
Loss ratio only includes claims costs (incurred losses divided by earned premiums). Combined ratio adds the expense ratio (underwriting expenses divided by written premiums). Combined ratio is the true measure of underwriting profitability because it captures both claims and operational efficiency in one number.
How often should I track these indicators?
Track loss ratio, expense ratio, and NPW growth monthly. Review LDF and IBNR quarterly. Assess premium-to-surplus annually. Monthly tracking catches emerging trends early, while quarterly actuarial metrics smooth out volatility. Annual review aligns with regulatory filing cycles.
Which indicator is best for a startup carrier?
Focus on NPW growth rate and NBP conversion rate. These measure top-line velocity and sales effectiveness, which are critical for gaining market share. Optimize combined ratio later once you have scale. Startups need to prove revenue momentum before profitability.
Can I use these indicators for life insurance?
No, these are P&C-specific. Life insurance uses mortality ratios, persistency rates, and lapse ratios. The loss ratio concept differs because life claims are event-driven, not occurrence-based. Use P&C metrics only for property, casualty, auto, and liability lines.
What tool automates these calculations?
Salesforce Financial Services Cloud with Tableau dashboards automates most metrics. For actuarial calculations like LDF and IBNR, use Guidewire ClaimCenter or SAS Insurance Analytics. These tools integrate data sources and provide real-time visibility into underwriting performance.
Why is IBNR ratio the 'best value'?
IBNR ratio is free to compute (just divide estimated unreported claims by earned premium) and provides a 6-month early warning of loss ratio spikes. A 2-point shift can signal a $10M reserve deficiency. Most competitors don't track it, giving you a strategic edge.
How does premium retention rate affect growth?
A retention rate below 75% means you're ceding too much risk or paying too much for reinsurance. This reduces net premium and constrains growth. Optimal retention is 75-85% for property-heavy books. Adjust treaty terms or switch to quota-share to free up capital.
What is a healthy premium-to-surplus ratio?
NAIC flags anything above 3.0 as risky. The 2027 industry average is 2.4, but high-growth carriers push to 2.8. Carriers below 2.0 have 12% higher ROE on average. If you're above 2.8, slow new business until you raise capital or cede more risk.
FAQ
What is the combined ratio formula?
Combined ratio = Loss Ratio + Expense Ratio. Loss ratio is incurred losses divided by earned premiums. Expense ratio is underwriting expenses divided by written premiums. A ratio below 100% means underwriting profit; above 100% means loss.
What is a good loss ratio for auto insurance?
The 2027 average personal auto loss ratio is 74.3%. Anything below 70% is excellent, while above 80% signals rate inadequacy or claims process failure. Normalize for catastrophe load using a 5-year rolling average to separate noise from trend.
How do I improve my expense ratio?
Audit your Salesforce instance for redundant approval workflows. Each extra click in quote-to-bind adds $2.50 per policy. Automate underwriting rules and use direct digital channels. Target an expense ratio below 25% to offset loss ratio volatility.
What is NPW growth rate?
Net Premiums Written (NPW) is gross premiums written minus ceded reinsurance. Growth rate is the quarter-over-quarter or year-over-year change. The 2027 industry average is 8.2%, but top-quartile carriers hit 14%+ by leaning into cyber and parametric insurance.
What is a loss development factor?
LDF measures how much initial loss estimates grow as claims mature. A 1.20 LDF means losses are 20% higher than originally booked. Commercial auto LDFs are running 1.35 due to social inflation. If your LDF is above 1.25, your loss ratio is understated.
What is NBP conversion rate?
New Business Premium (NBP) conversion rate is the percentage of quotes that become bound policies. Industry average is 22%, but top performers hit 35%. Segment by channel: independent agents convert at 18%, direct digital at 28%.
What is average premium per policy?
APP is total earned premium divided by number of policies in force. In 2027, personal auto APP is $1,850; commercial auto is $4,200. A declining APP signals adverse selection or rate inadequacy. Segment by channel to identify low-quality risk sources.
What is IBNR ratio?
IBNR ratio is estimated unreported claims divided by earned premium. For workers' comp, the average is 12%. A sudden jump from 10% to 14% means claims are being underreported. Track it monthly for a 6-month early warning of loss ratio spikes.
How does premium retention rate work?
Premium retention rate is net written premium divided by gross written premium. It shows the percentage of premium you keep after reinsurance. A rate below 70% means you're ceding too much risk. The 2027 median for regional carriers is 78%.
What is premium-to-surplus ratio?
It measures leverage: net written premium divided by policyholder surplus. NAIC flags anything above 3.0 as risky. The 2027 industry average is 2.4. Carriers below 2.0 have 12% higher ROE. Use it to set underwriting appetite boundaries.
Sources
- https://www.iii.org/publications/insurance-fact-book-2027/
- https://www.naic.org/prod_serv_financial_data.htm
- https://www.deloitte.com/us/en/industries/financial-services/insurance-outlook.html
- https://www.ambest.com/ratings/methodology/
- https://www.mckinsey.com/industries/financial-services/our-insights/insurance-unit-economics
- https://www.spglobal.com/marketintelligence/en/topics/insurance
- https://www.winningbydesign.com/resources/insurance-go-to-market
- https://www.guidewire.com/solutions/insurance-analytics
Related on PULSE
- [More insurance loss ratio and premium revenue indicators rankings and buying guides](/knowledge)
- [PULSE Tools and calculators](/tools)
- [Everything on PULSE RevOps](/)
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
 pulse-industry-kpisTop 10 Bowling Alley Revenue KPIs in 2027
 pulse-industry-kpisTop 10 Commercial Real Estate Revenue KPIs in 2027
 pulse-industry-kpisTop 10 Logistics Revenue per Mile and Cost-to-Revenue Ratios in 2027
 pulse-industry-kpisTop 10 Parcel Carrier Revenue per Package and Density KPIs in 2027
 pulse-industry-kpisFintech Lending: Revenue Per Loan Origination After Risk-Adjusted Charge-Offs in 2027
 pulse-industry-kpisTop 10 Telecommunications ARPU and Churn Rate KPIs in 2027
 pulse-industry-kpisTop 10 Dental Practice Revenue KPIs in 2027
 pulse-industry-kpisTransaction Revenue Per Active User in Digital Wallets like PayPal in 2027
 pulse-industry-kpisTop 10 Pharmaceutical Revenue KPIs in 2027
 pulse-industry-kpisBillable Utilization Rate in Global Law Firms as a Profitability Metric in 2027