


Top 10 Best Tech Stack Tools for Property and Casualty Insurance Brokers in 2027
Quality
Certified
The 10 best tech stack tools for property and casualty insurance brokers are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Applied Epic Agency Management System
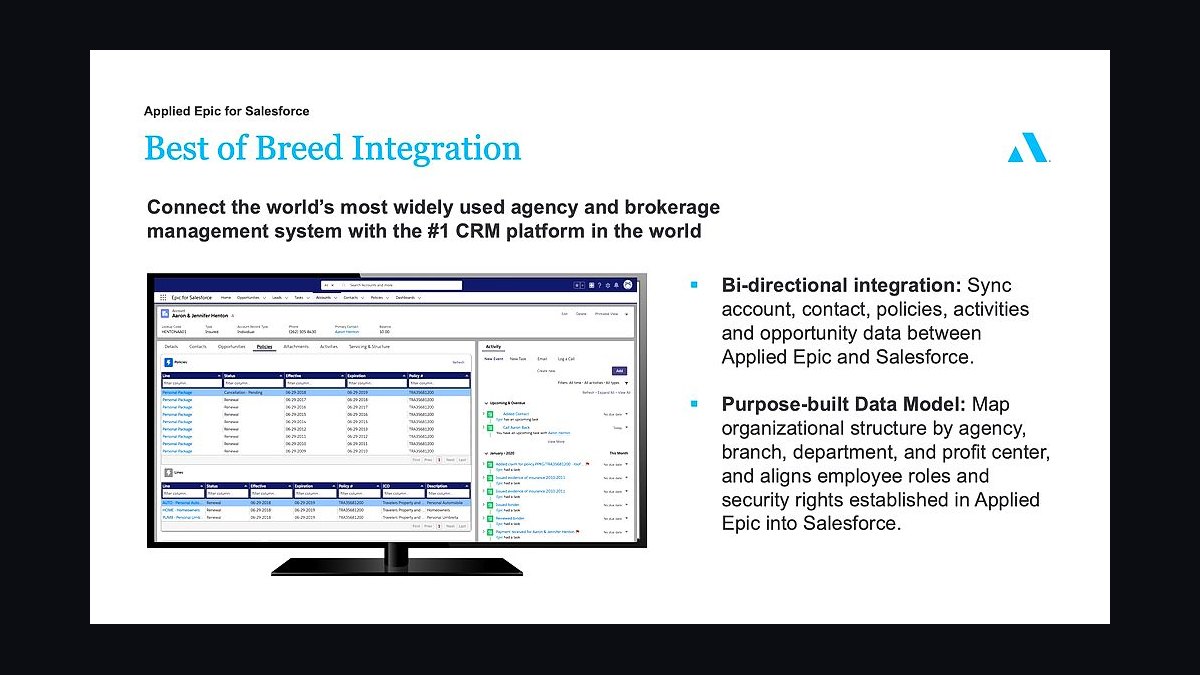
Applied Epic ranks first because it is the system of record every other tool must feed, holding policies, commissions, and carrier codes for mid-to-large brokerages. It supports 20-50 staff shops with built-in CRM modules and API connections, and implementation realistically runs six to nine months from contract to full adoption. Without it, raters and CRMs create conflicting client records.
It suits brokerages past roughly 15 staff that can absorb a long rollout and dedicated training time. Smaller agencies trade away depth for speed and cost, since Applied Epic's configuration overhead exceeds what a five-person shop can maintain. Compared to QQSolutions directly below, it offers far deeper commission and carrier modeling but demands real implementation discipline.
2QQSolutions Agency Management System
QQSolutions ranks second as the budget entry point for very small shops that do not yet need Applied Epic's depth. A one-to-five-person independent agency can run a functional stack including cloud AMS, rater, HubSpot, and DocuSign for a modest monthly spend, often under what one lost commercial account costs annually. It covers core policy and client records without enterprise configuration.
It is built for solo producers and tiny agencies writing mostly personal lines, trading away advanced commission splits, multi-line policy structures, and deep carrier integrations. Compared to Applied Epic above, it lacks the horsepower for 20-plus staff, but it goes live in weeks rather than months. Compared to EZLynx below, it manages policy records rather than rating.
3EZLynx Comparative Rater
EZLynx ranks third because the comparative rater is the clearest speed lever in the stack, eliminating manual entry into multiple carrier portals. It is the personal-lines standard, with API-based rating returning rates in seconds and pushing winning quotes into the AMS without re-keying. The realistic benchmark is a bindable personal-lines quote in under 10 minutes from first data entry.
It is built for personal-lines-heavy brokers writing auto and home, trading away commercial-lines depth that Indio handles better. Compared to QQSolutions above, it rates rather than stores policies, so it complements an AMS instead of replacing one. Compared to Indio below, it wins on carrier breadth for personal lines but loses on commercial application collection.
4Indio Commercial Lines Quoting Platform
Indio ranks fourth because commercial-lines quoting is where manual re-keying costs the most time, and Indio's digital application collection removes it. Commercial lines with Indio typically run 24-48 hours end to end because underwriting still reviews documents, even when technology eliminates duplicate data entry. It pushes the winning quote into the AMS automatically.
It is built for commercial-heavy brokers writing casualty and property accounts, trading away the personal-lines carrier breadth EZLynx offers. Compared to EZLynx above, it wins on application and document collection for complex risks but is slower for simple auto and home quotes. Compared to Salesforce Financial Services Cloud below, it quotes rather than manages relationships.
5Salesforce Financial Services Cloud
Salesforce Financial Services Cloud ranks fifth because it is the standard CRM layer for brokers past 50 staff, built with insurance-specific data objects like policy, coverage, and household rather than generic pipeline stages. It reads renewal dates from the AMS and triggers outreach 60-90 days out, supporting retention in the 88-92% range for personal lines.
It is built for large brokerages where cost and complexity pay off, trading away the simplicity a mid-market shop gets from HubSpot or an AMS's built-in CRM module. Compared to Indio above, it manages relationships rather than quoting. Compared to HubSpot below, it models insurance data natively but costs substantially more to license and configure.
6HubSpot CRM
HubSpot ranks sixth because mid-market brokerages of 20-50 staff often get more value from it than from Salesforce, at a fraction of the cost and configuration burden. It owns the relationship layer, tracking lead source, communication history, and cross-sell opportunities while reading renewal dates from the AMS. It pairs with EZLynx and DocuSign in a functional small-agency stack.
It is built for agencies that want marketing and CRM without enterprise overhead, trading away insurance-specific data objects like premium splits and carrier codes. Compared to Salesforce Financial Services Cloud above, it is cheaper and faster to deploy but less capable past roughly 50 staff. Compared to ImageRight below, it manages relationships rather than documents.
7ImageRight Document Management
ImageRight ranks seventh because document compliance is the highest-consequence failure mode, and it timestamps and versions every document automatically. It enforces retention schedules and immutable audit trails that general cloud storage lacks, so a broker can answer a regulator's request on a three-year-old claim in minutes rather than a week of searching email threads.
It is built for brokerages that need E&O defense and audit readiness, trading away the casual simplicity of Google Drive or Dropbox. Compared to HubSpot above, it stores documents rather than relationships. Compared to DocuSign below, it is the deeper repository for historical policy files, while DocuSign handles the signing moment itself.
8DocuSign E-Signature
DocuSign ranks eighth because it makes every signature auditable by default, timestamping and versioning documents whether or not anyone remembers to build a trail. It appears in functional stacks from one-person agencies through mid-market shops, pairing with ImageRight for the compliance leg of the outcome. Signed applications and disclosures land in a defensible record.
It is built for any broker needing compliant e-signature, trading away the deep historical document repository that ImageRight provides. Compared to ImageRight above, it captures the signing moment rather than storing the full policy file. Compared to Power BI below, it handles documents rather than analytics, and the two rarely overlap.
9Microsoft Power BI
Power BI ranks ninth because commission and retention reporting is the last layer added, typically in phase four of a twelve-month rollout. It builds dashboards from AMS data so brokers can see commission reconciliation and retention trends, supporting the 88-92% personal-lines retention benchmark. It connects through an iPaaS rather than manual exports.
It is built for brokerages that already have clean AMS data, trading away nothing on cost but requiring integration work before it delivers value. Compared to DocuSign above, it analyzes numbers rather than documents. Compared to Tableau below, it is the Microsoft-ecosystem default, while Tableau suits shops already standardized elsewhere.
10Tableau Analytics Platform
Tableau ranks tenth because it serves the same commission and retention reporting role as Power BI, and mid-market brokerages layer in one or the other, not both. It visualizes AMS data for commission reconciliation and retention tracking, connecting through an iPaaS like Zapier or MuleSoft so data stops requiring manual movement.
It is built for brokerages already standardized on non-Microsoft analytics tooling, trading away Power BI's native Microsoft integration. Compared to Power BI above, it is functionally comparable for this use case, so the choice usually comes down to existing ecosystem rather than capability. Neither delivers value until the AMS holds clean, authoritative data.
How we ranked these
We ranked tools on five weighted criteria: integration density with the Agency Management System (30%), quote-to-bind speed for personal and commercial lines (25%), compliance and audit-trail strength (20%), total cost of ownership across a three-year horizon (15%), and staff adoption difficulty (10%). Scores came from vendor documentation, published API capabilities, carrier-connection counts, and reported implementation timelines across agency sizes.
We deliberately ignored vendor market share, brand recognition, and analyst-quadrant placement, because none of those predict whether a specific brokerage's workflow improves. We also excluded pricing promotions and bundled discounts, since they distort long-run cost comparisons. Feature counts were ignored too: a tool with forty features nobody configures performs worse than one with eight that all write back into the AMS automatically.
What to look for
What matters most is whether each tool writes data back into the AMS without human re-entry. A rater that returns rates but cannot push the winning quote into the policy record saves minutes and costs hours. Ask vendors for a live integration demonstration using your actual carrier appointments, not a sandbox with fictional carriers.
The mistake most buyers make is choosing tools by feature checklist rather than by integration path. They compare rater carrier counts, CRM automation depth, and dashboard flexibility, then discover after go-live that nothing talks to anything. Insist on a written data-flow diagram before signing, and treat any vendor who cannot produce one as a disqualification, regardless of price.
Related questions
Does a one-person agency need a full comparative rater?
Yes, even a solo broker benefits. TurboRater or a budget EZLynx tier still eliminates manual carrier-portal entry, which is the single biggest time sink for an independent producer writing personal lines. The monthly cost is usually recovered by binding one additional policy per quarter that would otherwise have gone to a faster competitor.
Should the AMS or the CRM own renewal dates?
The AMS should hold the authoritative expiration date because it is tied to the bound policy and carrier records. The CRM should read that date and trigger outreach workflows, never store its own separate copy. Two competing renewal dates guarantee that one of them drifts, and the drifted one is always the one staff trust.
Is Salesforce overkill for a mid-market brokerage?
Often, yes. Salesforce Financial Services Cloud's cost and complexity typically only pay off past roughly fifty staff. A mid-market shop usually gets more value from HubSpot or the AMS's built-in CRM module, then migrates to Salesforce later if cross-sell analytics and household modeling become genuine operational needs rather than aspirational ones.
How often should a broker re-evaluate its rater?
Annually at minimum, because carriers add and drop API partnerships regularly. A rater that quoted eight carriers well last year may have lost several to portal changes this year, silently reducing your quote coverage. Review carrier connection lists each renewal season and test a live quote against your top five carriers before committing.
Can a broker skip the comparative rater and use carrier portals directly?
Technically yes, but it multiplies quote time several-fold and increases data-entry errors. Virtually every competitive insurance brokerage in 2027 has moved off manual portal quoting because the first accurate quote in a client's inbox usually wins the business, not the cheapest quote arriving three days later.
Is Google Drive acceptable for storing signed policy documents?
No. General cloud storage lacks the retention policies, version control, and immutable audit trails that insurance compliance and E&O defense require. A purpose-built system like ImageRight or DocuSign's compliance features exists specifically because regulators and litigators ask for proof of disclosure years after the fact, and shared drives cannot reliably produce it.
Does a small agency need MuleSoft-level integration tooling?
No. Zapier handles the integration needs of most small-to-mid agencies at a fraction of the cost. MuleSoft only becomes necessary once integration volume and complexity reach enterprise scale, typically when carrier APIs, legacy data warehouses, and third-party analytics feeds all need orchestration simultaneously across dozens of systems.
How does the stack change for a commercial casualty broker versus personal lines?
Commercial-heavy brokers should prioritize Indio for its digital application and document-collection strength, since commercial underwriting still requires document review. Personal-lines-heavy brokers get more value from EZLynx's breadth of carrier connections for auto and home, where bindable quotes in under ten minutes are the realistic benchmark.
FAQ
What is the single most important system in a P&C broker's stack?
The Agency Management System, because it is the durable system of record for policies, commissions, and carrier relationships. Every other tool should feed data into it rather than compete with it. When the AMS is treated as secondary, commission reconciliation and regulatory reporting both break, often silently, until an audit reveals the mismatch.
Can a broker skip the comparative rater and just use carrier portals directly?
Technically yes, but it multiplies quote time several-fold and increases data-entry errors. Virtually every competitive insurance brokerage in 2027 has moved off manual portal quoting because the first accurate quote in a client's inbox usually wins the business, not the cheapest quote arriving three days later.
Is Google Drive acceptable for storing signed policy documents?
No. General cloud storage lacks the retention policies, version control, and audit trails that insurance compliance and E&O defense require. A purpose-built system like ImageRight or DocuSign is necessary because regulators and litigators ask for proof of disclosure years after the fact, and shared drives cannot reliably produce it.
Does a small agency need MuleSoft-level integration tooling?
No. Zapier handles the integration needs of most small-to-mid agencies at a fraction of the cost. MuleSoft only becomes necessary once integration volume and complexity reach enterprise scale, typically when carrier APIs, legacy data warehouses, and third-party analytics feeds all need orchestration simultaneously across dozens of systems.
How does the stack change for a broker writing mostly commercial casualty lines?
Commercial-heavy brokers should prioritize Indio for its digital application and document-collection strength, since commercial underwriting still requires document review. Personal-lines-heavy brokers get more value from EZLynx's breadth of carrier connections for auto and home, where bindable quotes in under ten minutes are the realistic benchmark.
What is the biggest mistake brokers make when building this stack?
Buying every tool at once instead of sequencing the rollout. Agencies that try to implement AMS, rater, CRM, and document management simultaneously see far lower staff adoption than those who phase it in over a year. A tool without an automated data path into the AMS becomes a silo, and silos are where retention and compliance risks originate.
How long does a full stack implementation realistically take?
A mid-market brokerage of twenty to fifty staff should expect six to nine months from contract signature to full staff adoption. Agencies that compress this into weeks tend to see poor data migration quality and staff reverting to old habits, which erases the entire return on the software investment.
What retention improvement should an agency expect from automated renewal workflows?
Agencies with automated renewal workflows commonly land in the 88-92% range for personal lines, versus noticeably lower retention at agencies still relying on manual renewal tracking. The largest driver of client churn in insurance brokerage is not price shopping, it is simple neglect of a renewal notice that goes out late.
Are API-based raters worth paying more for than scraping-based ones?
Yes, structurally. Carriers periodically update their systems in ways that break scraping-based integrations without warning, meaning an agency can lose quoting capability for a specific carrier overnight. API-based raters with genuine carrier partnerships cost more but do not carry that overnight-loss risk, which matters more each year.
What cybersecurity baseline should a P&C brokerage enforce across its stack?
Multi-factor authentication and endpoint protection across the AMS, CRM, and document systems are the minimum. Insurance brokers hold concentrated troves of financial and property data, making them attractive targets. One credential-stuffing attack can cost far more than the entire annual software budget the stack was assembled to optimize.
Sources
- https://www.appliedsystems.com
- https://www.ezlynx.com
- https://www.indio.com
- https://www.salesforce.com/products/financial-services-cloud
- https://www.hubspot.com
- https://www.docusign.com
- https://www.imageright.com
- https://www.naic.org
- https://www.crowdstrike.com
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 tkTop 10 Best Tech Stack Tools for Cannabis Dispensary Chains in 2027
 tkTop 10 Best Tech Stack Tools for First-Time Business Owners in 2027
 tkTop 10 Best Tech Stack Tools for Private Equity Portfolio Companies in 2027
 tkTop 10 Best Tech Stack Tools for Third-Party Logistics (3PL) Warehouse Operators in 2027
 tkTop 10 Best Tech Stack Tools for Concrete and Paving Contractors in 2027
 tkTop 10 Best Tech Stack Tools for Virtual Healthcare and Telemedicine Startups in 2027
 tkTop 10 Best Tech Stack Tools for Lawn Care and Landscaping Companies in 2027
 tkTop 10 Best Tech Stack Tools for Managed IT Services Providers (MSPs) in 2027
 tkTop 10 Best Tech Stack Tools for Direct-to-Consumer (DTC) Apparel Brands in 2027
 tkTop 10 Best Tech Stack Tools for Fencing and Deck Contractors in 2027