


Top 10 Sales KPIs for Rideshare and Mobility Marketplaces in 2027
Quality
Certified
The 10 best sales kpis for rideshare and mobility marketplaces are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Uber Gross Bookings KPI
Gross Bookings ranks first because it is the top-line volume measure every mobility marketplace reports first. Uber closed 2025 at $193B in gross bookings, with Q1 2026 alone at $53.7B, up 25% year over year. Lyft posted $4.9B in Q1 2026, up 19%, while Grab consolidated roughly $18B in 2025. No other KPI captures total marketplace demand at this scale.
This KPI is for CFOs, investor-relations teams, and city GMs who need one number that rolls up trips, pricing, and mix. It trades away unit-level truth: bookings can grow while every trip loses money, so it must be paired with contribution margin. It sits above Take Rate because take rate is a percentage of this base, not a substitute for it.
2Uber Mobility Take Rate
Take Rate ranks second because it converts gross bookings into platform revenue and is the most-debated line on every mobility earnings call. Uber Mobility runs about 29.9%, up from roughly 19% pre-pandemic, while Lyft sits near 34% and DiDi and Grab run 18-22%. A 100bps move at Uber's scale is roughly $1.9B of revenue.
This metric is for pricing and marketplace teams deciding how much fee extraction the rider and driver sides will tolerate. It trades away supply health: pushing take rate above 32-33% without ad or membership offsets shows up as ETA degradation and rider churn. It ranks just below Gross Bookings because it is a ratio of that base.
3Uber Monthly Active Platform Consumers
MAPC ranks third because it is the truest demand-retention signal: unique users completing at least one trip or order in 30 days. Uber crossed 202M MAPCs by end-2025, up 14% year over year, and Lyft hit 28.3M active riders in Q1 2026, up 17%. Grab reports roughly 46M monthly transacting users across its super-app.
This KPI is for growth and retention leaders who need to separate registered accounts from engaged demand. It trades away frequency detail: a user taking one trip counts the same as one taking forty. It ranks above Driver Supply Hours because demand retention ultimately determines whether supply investment pays back.
4Uber Driver Supply Hours
Driver Supply Hours ranks fourth because supply, not capital, is the binding constraint in rideshare marketplaces. Uber reports about 8.5M drivers and couriers and paid out $82B in 2025, but the operating metric that matters is driver-hours during the top-20% surge windows by city. A 5% lift in peak driver-hours can raise gross bookings 8-10% in that city.
This KPI is for city operations and incentive teams managing surge coverage and driver churn. It trades away simplicity: absolute hours are rarely disclosed, so teams must instrument acceptance rates and online time themselves. It ranks above Time-to-Pickup ETA because ETA is the downstream symptom of supply gaps.
5Uber Time-to-Pickup ETA
Time-to-Pickup ETA ranks fifth because it is the liquidity metric riders actually feel and the leading indicator of churn. Best-in-class urban markets run 3-4 minutes, suburban 5-7 minutes, and non-core 10+ minutes. Uber and Lyft target sub-5-minute ETAs in tier-one cities, and every 60-second improvement correlates with roughly 2-3% MAPC retention lift on a trailing-90-day basis.
This KPI is for dispatch, pricing, and marketplace-liquidity teams balancing surge against rider experience. It trades away cost visibility: shaving a minute may require incentive spend that erodes contribution margin. It ranks below Driver Supply Hours because ETA is the outcome that supply hours produce.
6Uber Contribution Margin per Trip
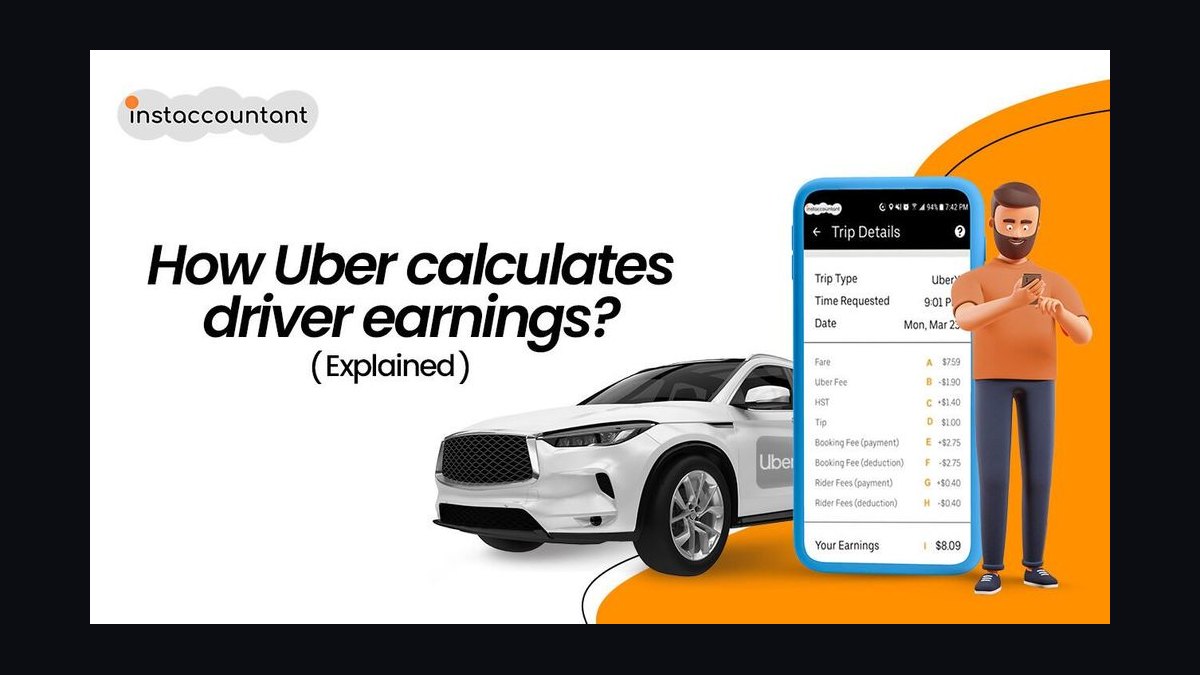
Contribution Margin per Trip ranks sixth because it reveals whether growth is profitable after driver pay, insurance, payment processing, and support. Uber's Mobility adjusted EBITDA margin reached 7.4% of gross bookings in 2025, best in category, while Lyft sits closer to 3-4%. Per-trip contribution is up 15-25% year over year at both as upfront pricing and ad attach scale.
This KPI is for CFOs and finance teams deciding which cities to fund and which to fix. It trades away growth optics: a city can post record bookings while losing money on every ride. It ranks above Autonomy Mix because robotaxi economics are ultimately judged against this human-driver baseline.
7Uber Autonomy Robotaxi Mix
Autonomy/Robotaxi Mix ranks seventh because it is the 2027 fork in the road for mobility cost structure. Waymo crossed 250,000 paid rides per week in 2025 across Phoenix, San Francisco, Los Angeles, and Austin. Robotaxi is sub-1% of Uber and Lyft global trips today but is projected to cross 5% in tier-one US metros by 2027. The KPI that matters is autonomous-trip contribution margin versus human-driver in the same metro.
This KPI is for strategy and corporate-development teams structuring Uber-Waymo, Uber-Aurora, Lyft-Mobileye, and Grab-WeRide partnerships. It trades away near-term relevance: fleet ops are unprofitable below roughly 20 daily trips per vehicle. It ranks below Contribution Margin per Trip because autonomy must eventually beat that baseline, not replace it.
8Uber Advertising Revenue
Advertising Revenue ranks eighth because it is the highest-margin attach in the mobility P&L. Uber Ads crossed a $1.5B run-rate by 2026, growing 60%+ year over year, while Lyft Media sits near a $90M run-rate. Ads carry 50%+ contribution margin, which is why analysts now model ad revenue as a separate line rather than folding it into take rate.
This KPI is for monetization and ad-tech teams building sponsored placements for riders and drivers. It trades away scale relevance: ads remain under 5% of gross bookings even at Uber. It ranks below Autonomy Mix because ad attach improves margins today, while autonomy reshapes the cost base by 2027.
9Uber Revenue per Active User
Revenue per Active User ranks ninth because it blends take rate, ad attach, membership, and frequency into one efficiency number. Uber's trailing-12-month revenue per MAPC is roughly $340 and rising, while Lyft is closer to $235. Uber One reached 37M members by mid-2026, and membership is the leading indicator for both MAPC retention and per-user revenue expansion.
This KPI is for investor-relations and growth teams benchmarking monetization against peers. It trades away segment clarity: delivery, freight, and ads blur the mobility-only picture, so it must be decomposed. It ranks below Advertising Revenue because ads are the fastest-growing input into this per-user figure.
10Uber Trips per Quarter
Trips per Quarter ranks tenth because it is the pure-volume metric that anchors every other ratio on this list. Uber reported 3.6B trips in Q1 2026, up 20% year over year, with its mobility segment alone exceeding 8B trips in 2025. Lyft reported about 232M trips in Q1 2026, Grab does roughly 1B mobility trips annually, and DiDi runs about 10B trips per year in China.
This KPI is for operating teams decomposing volume across mobility, delivery, and freight. It trades away dollar context: a trip can be a $4 short hop or a $90 airport run, so it must be paired with gross bookings. It ranks last because it is the raw input every higher-ranked KPI converts into revenue or margin.
How we ranked these
We ranked the nine KPIs by weighting three factors: revenue impact at marketplace scale (40%), leading-indicator power for 2027 strategy shifts (35%), and data availability across public filings and operator disclosures (25%). Trips, gross bookings, take rate, and MAPC scored highest because they are auditable in 10-Ks and 20-Fs and move directly with enterprise value. Autonomy mix and ad revenue received elevated weight despite small current bases because they reshape 2027 margins.
We deliberately ignored vanity metrics: registered users, app downloads, social mentions, brand-awareness scores, and total addressable market projections. These are either non-comparable across operators or disconnected from unit economics. We also excluded driver satisfaction scores and NPS because methodologies vary and they lag bookings by two quarters. Finally, we dropped any metric that cannot be traced to a verifiable public disclosure or operator earnings call, keeping the list defensible for CFO-level review.
What to look for
When choosing between these KPIs, match the metric to the decision you are actually making. Take rate and contribution margin per trip belong in pricing and incentive reviews; MAPC and time-to-pickup ETA belong in growth and retention planning; autonomy mix and ad revenue belong in three-year capital allocation. A metric that does not change a decision within 30 days should not be on the executive dashboard, no matter how impressive it looks in a board deck.
The mistake most buyers make is adopting a competitor's KPI set wholesale without checking whether their own city mix, take-rate ceiling, and driver-supply model support it. A 34% take rate works for Lyft's US density but collapses in markets where DiDi or Grab face regulatory caps near 20%. Copying Uber's ad-revenue target without its 202M MAPC base produces fantasy forecasts. Anchor each KPI to your own unit economics first.
Related questions
How do you calculate take rate for a rideshare marketplace?
Divide total platform revenue by gross bookings for the same period, excluding pass-through items like tolls and taxes. Uber Mobility runs near 29.9%, Lyft near 34%, and Grab and DiDi closer to 18-22%. Track it monthly by city and trip type, because blended take rate hides markets where rider churn is already responding to fee increases.
What is a healthy contribution margin per trip in 2027?
Best-in-class mobility platforms target roughly $0.50 to $2.00 per trip after driver pay, insurance, payment processing, and support. Uber's Mobility adjusted EBITDA reached 7.4% of gross bookings in 2025; Lyft sits closer to 3-4%. Anything below breakeven per trip means growth is destroying cash, regardless of gross bookings trajectory.
Why does time-to-pickup ETA predict MAPC churn?
Median ETA is the clearest signal of marketplace liquidity. When ETAs creep past six minutes, rider churn accelerates 30 to 90 days later, and every 60-second improvement correlates with roughly 2-3% retention lift on a trailing-90-day basis. Track it daily by city and by hour, not as a monthly average.
How should robotaxi mix be measured in 2027?
Measure autonomous trips as a percentage of total trips in each pilot metro, then compare contribution margin per autonomous trip against human-driver trips in the same city. Waymo crossed 250,000 paid weekly rides in 2025. Robotaxi is sub-1% of Uber and Lyft global trips today, with tier-one US metros projected to cross 5% by 2027.
What counts as advertising revenue for a mobility platform?
In-app display ads, sponsored placements, promoted merchant listings, and post-trip offers shown to riders or drivers. Uber Ads crossed a $1.5B run-rate by 2026, growing over 60% year-over-year; Lyft Media is roughly $90M. Ads carry 50%+ contribution margin, so model them as a separate line rather than folding into take rate.
How often should driver supply hours be reviewed?
Review driver-hours weekly, segmented by the top-20% surge windows in each city. A 5% lift in peak driver-hours can raise gross bookings 8-10% in the same city, while a 10% drop during surge can cut bookings 15% within a week. Monthly averages hide the peak-window shortages that actually cost revenue.
What is the right cadence for reforecasting take rate?
Reforecast take rate monthly by segment and city, not quarterly at the consolidated level. A 100-basis-point move at Uber's scale is roughly $1.9B of revenue, so small drifts compound fast. Tie each reforecast to driver acceptance rates, rider churn, and any regulatory action on gig-worker classification or fee caps.
Which KPI best predicts a marketplace's 2027 margin trajectory?
Ad attach rate combined with autonomy mix. Platforms that built ad-tech early, like Uber and Instacart, are pulling away on margin while pure-fare marketplaces stay below 5% EBITDA. Autonomy mix determines the long-run cost structure. Together they explain more of the 2027 margin gap than take rate alone.
FAQ
What are the most important sales KPIs for rideshare marketplaces in 2027?
The nine that matter are trips per quarter, gross bookings, take rate, monthly active platform consumers, driver supply hours, time-to-pickup ETA, contribution margin per trip, autonomy or robotaxi mix, and advertising revenue. Together they answer whether the marketplace is growing, retaining both sides, improving unit economics, and transitioning toward autonomous operations.
How does Uber's scale compare to Lyft, Grab, and DiDi in 2027?
Uber closed 2025 at $193B gross bookings with 202M MAPCs and a 29.9% mobility take rate. Lyft posted $4.9B in Q1 2026 gross bookings with 28.3M active riders. Grab runs roughly $18B in consolidated gross bookings across Southeast Asia, and DiDi operates over 2B annual mobility trips in China at lower take rates.
Why is driver supply the binding constraint rather than capital?
Capital is cheap; reliable drivers willing to work peak hours are not. Uber reports roughly 8.5M drivers and couriers and paid out $82B in 2025. A 5% lift in driver-hours during peak windows can raise gross bookings 8-10% in that city, so incentive spend and driver retention matter more than balance-sheet capacity.
What take rate is sustainable without triggering rider churn?
Most operators find that pushing take rate above 32-33% without offsetting value through ads, membership, or faster ETAs shows up as ETA degradation and MAPC defection within two quarters. DiDi and Grab stay near 18-22% because regulatory caps and competition limit fee extraction. Sustainability depends on local density and rider alternatives.
How do you measure marketplace liquidity operationally?
Track the probability a rider is matched within five minutes, segmented by city, hour, and neighborhood. Best-in-class urban markets run 3-4 minute median ETAs; suburban markets run 5-7 minutes. Liquidity is the underlying KPI, and take rate, MAPC, and contribution margin are all downstream of it.
What autonomy metrics should a CFO track in 2027?
Track autonomous trips as a share of total trips per pilot metro, contribution margin per autonomous trip versus human-driver trips in the same city, fleet utilization measured in daily trips per vehicle, and capex per vehicle deployed. Fleet ops are unprofitable below roughly 20 daily trips per vehicle, so utilization is the gating metric.
How large can advertising revenue get for a mobility platform?
Uber Ads crossed a $1.5B run-rate by 2026, growing over 60% year-over-year, while Lyft Media is roughly $90M. Ads carry 50%+ contribution margin, making them the highest-quality revenue line on the P&L. Even at scale, ad revenue typically stays under 5% of gross bookings, so model it separately from take rate.
What reporting cadence should a mobility marketplace use?
Daily: trips, gross bookings, median time-to-pickup, surge events, driver acceptance rate. Weekly: trailing-28-day MAPC, take rate by segment, driver-hours in top surge windows. Monthly: contribution margin per trip by city, ad run-rate, robotaxi mix, regulatory tracker. Quarterly: full segment P&L, cohort retention, and autonomy partnership economics.
What are the biggest failure modes for rideshare marketplaces in 2027?
Driver supply collapse during surge, take-rate optimism that triggers rider churn, robotaxi capex without metro density, and ignoring ad attach. Each one shows up first in a single KPI: driver-hours in peak windows, trailing-28-day MAPC, daily trips per autonomous vehicle, and ad revenue run-rate. Watch those four weekly and the rest follows.
How should a new operator sequence KPI instrumentation?
Days 1-30: reconcile trips and gross bookings across dispatch, payments, and finance, then baseline median ETA, trailing-28-day MAPC, and take rate by city. Days 31-60: ship a city-level contribution-margin dashboard. Days 61-90: stand up ad-revenue and membership tracking, plus robotaxi pilot economics in any metro with an autonomy partner.
Sources
- https://investor.uber.com/financials/default.aspx
- https://investor.lyft.com/financial-information/default.aspx
- https://www.didiglobal.com/about-didi/ir
- https://www.grab.com/sg/investor-relations/
- https://www.waymo.com/
- https://www.sec.gov/edgar/searchedgar/companysearch
- https://www.bts.gov/
- https://about.bnef.com/
- https://www.ibisworld.com/
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-industry-kpisTop 10 Sales KPIs for Industrial Cybersecurity (OT/ICS) Services in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Contract Research Organization (CRO) in 2027
 pulse-industry-kpisTop 10 Sales KPIs for AI Sales Coaching / Conversation Intelligence in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Architectural Terrazzo Flooring Installation in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Imaging Center Operations in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Industrial Crane & Hoist Manufacturing in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Insulation Contracting in 2027
 pulse-industry-kpisTop 10 KPIs for HVAC Contractors in 2027
 pulse-industry-kpisTop 10 KPIs for Barbershops in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Electrical Contracting in 2027