
The Best KPIs for Self-Storage Facilities in 2027
 Curated byKory White · Fractional CRO · Maryland
 PULSEKNOWLEDGE LIBRARY
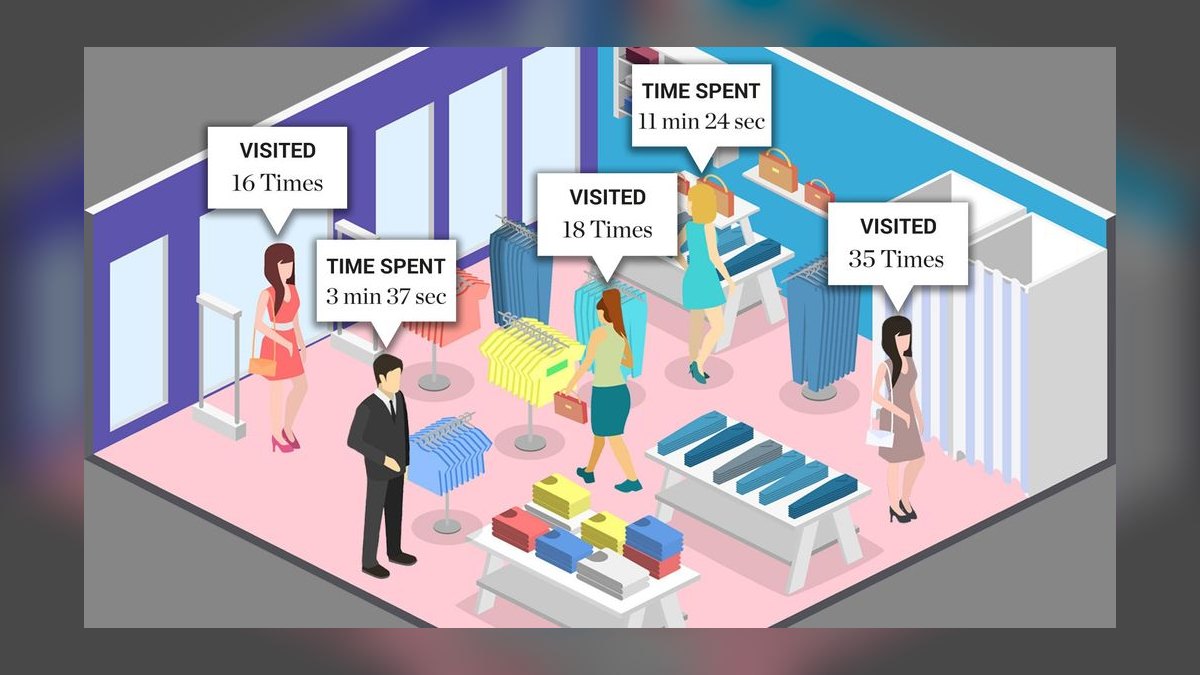
The best KPIs for self-storage facilities in 2027 are economic occupancy, revenue per available square foot, the street-to-in-place rate spread, existing customer rate increase capture, net move-ins, average length of stay, online conversion, and NOI margin. Physical occupancy alone misleads — it rises fastest when you discount hardest.
What these metrics actually measure and why the mix is different here
Self-storage sits in an unusual corner of commercial real estate: the cost base is close to fixed. Property taxes, insurance, a part-time or remote manager, modest utilities on non-climate space, and a marketing budget cover most of the operating line. There is no food cost, no meaningful cost of goods, and very little labor that scales with occupancy. That single structural fact reshapes which numbers matter. When an additional unit rents, the vast majority of that rent falls through to net operating income, and when a tenant absorbs a rate increase, essentially all of it does. Stabilized facilities commonly report NOI margins in the 60%–72% range, far above almost any other operating business of comparable revenue. The practical consequence is that a KPI set built for retail (traffic, basket size, inventory turns) or for multifamily (renewal rate, concession burn-off, turn cost) does not transfer cleanly. You need a set built around rate management on a fixed cost base.
The second structural difference is demand behavior. Nobody schedules a storage need six months out. The trigger is a life event — a move, a downsizing, a renovation, a divorce, a death in the family, a small business outgrowing a garage — and the search happens within days of the event. Demand is therefore hyper-local, intent-heavy, and largely captured through search. Trade sources including the Self Storage Association and Storable have consistently documented that the overwhelming majority of rentals now originate online, which makes the website the leasing office and online conversion a frontline operating metric rather than a marketing report line. A facility with a slow site, stale availability, or a broken online move-in flow is losing rentals it already paid to generate.
The third difference is rate elasticity after move-in. Vacating a storage unit is physically painful — you need a truck, a free weekend, and somewhere else to put things. That friction means existing tenants tolerate periodic rate increases far better than apartment renters do. The Existing Customer Rate Increase, universally shortened to ECRI, is the mechanism that converts that friction into revenue, and in the public REIT disclosures it is the dominant driver of same-store revenue growth. Public Storage, Extra Space Storage, and CubeSmart all describe revenue management functions built around this exact dynamic in their annual filings. Independent operators who copy the discipline — not the technology budget, just the discipline — close most of the performance gap against institutional portfolios.
Put together, the KPI mix must answer four questions simultaneously: how full am I, how much of my potential rent am I actually collecting, how much pricing runway do I have left, and how fast is the bucket leaking. Physical occupancy answers only the first. Every other number on the list exists because that first number, on its own, can be bought with discounts.
Here is the working definition of each core metric, stated precisely enough to build a report against.
Physical occupancy is rented units divided by total rentable units, and it should also be computed on a square-footage basis because a facility full of 5x5s and empty of 10x20s reads very differently by unit count than by area. Stabilized facilities typically operate in the high 80s to low 90s. Running above the mid-90s for an extended period is usually a pricing signal, not a victory lap.
Economic occupancy is rent actually collected divided by gross potential rent at current street rates for the same unit mix. It captures everything physical occupancy hides: the first-month-free promo, the manager's discretionary discount, the delinquent tenant, and the tenant who signed three years ago and has never seen an increase. A double-digit gap between physical and economic occupancy is normal; the size and direction of that gap over time is the interesting part.
Revenue per available square foot (RevPAF) is total realized rent divided by total rentable square footage, quoted monthly. It is the single best scoreboard because it collapses occupancy and rate into one number that cannot be gamed by either alone. Compare it against your own trailing twelve months first, then against local competitors, then against published market benchmarks — in that order of reliability.
Street-to-in-place spread is today's advertised rate for a comparable vacant unit minus the average rate paid by existing tenants in that same unit type, expressed as a percentage. This is your pricing runway. A wide spread means room to run increases; a spread near zero means your growth has to come from occupancy or new supply absorption instead.
ECRI capture is the realized revenue lift from a rate-increase batch, net of the revenue lost to move-outs that batch triggered, measured 60 to 90 days after the notices go out. Gross lift is a vanity number. Net lift is the metric.
Net move-ins is move-ins minus move-outs over a period, tracked weekly. It answers whether the bucket is filling or draining right now, well before the monthly financials say so.
Average length of stay is average tenancy duration in months, ideally reported as a cohort curve rather than a single average, because the distribution is heavily skewed by a long tail of multi-year tenants who have absorbed several increases and cost nothing to retain.
Online conversion is best tracked as a two-stage funnel: sessions to reservations, then reservations to completed move-ins. Collapsing it into one number hides which stage is broken.
NOI margin is net operating income over total revenue, and it functions as the catch-all health check. Because self-storage trades on a capitalization rate applied to NOI, every operating improvement translates directly into asset value, which is why this metric belongs on the same dashboard as the operational ones.
Running the measurement cycle end to end
The KPI set only produces value inside a repeating operating cycle. Measurement without a scheduled action is a dashboard, not a program. The cycle below is what disciplined operators actually run, and it is deliberately simple enough for a single-facility owner to execute without a revenue management team.
Step one — establish the baseline. Pull a unit-mix report showing every unit type, count, square footage, current street rate, and the average in-place rate for occupied units of that type. This one table produces physical occupancy by type, the rate spread by type, and gross potential rent. Most management platforms — Storable's products, Yardi Breeze, and comparable systems — export this directly. If yours cannot, build it once in a spreadsheet from the rent roll; it takes an afternoon and you will use it every month afterward.
Step two — compute economic occupancy honestly. Take actual rent billed for the month, not cash collected, and divide by gross potential rent from step one. Then run the same calculation on cash collected to expose delinquency separately. If billed-basis economic occupancy is 86% and cash-basis is 81%, you have a collections problem sitting on top of a pricing problem, and they need different fixes.
Step three — quantify the concession drag. Sum every dollar of discount, promotional rate, and waived fee for the month and express it as a percentage of gross potential rent. This number is usually larger than owners expect because the standard first-month-free offer is often applied to units that would have rented anyway. Segment it: how much promo went to slow-moving unit types versus fast-moving ones. Promo on a unit type running at 95% occupancy is pure margin donation.
Step four — build the ECRI queue. List every tenant past a defined tenure threshold — commonly nine to twelve months since move-in or since their last increase — with their current rate, the current street rate for their unit type, and the resulting spread. Sort by spread descending. Tenants with the widest spread and the longest tenure are the safest increases because they are the furthest below market and the most physically anchored.
Step five — release the increase in batches, never all at once. Send notices to a subset, respect your state's required notice period and your lease terms, and hold the rest. Batching lets you measure response before committing the whole rent roll.
Step six — measure net lift at 60 and 90 days. Compare the annualized revenue added by tenants who stayed against the revenue lost from those who left, plus the cost and downtime of backfilling those vacated units. Then feed that result back into the next batch's sizing.
Step seven — backfill through the website. Every unit vacated by an increase should re-rent at the current street rate, which is typically well above what the departing tenant was paying. This is the quiet part of the ECRI math: a move-out triggered by an increase often results in a *higher* rate on that unit within weeks, provided demand supports it and the online funnel converts.
The cycle repeats on a fixed cadence rather than opportunistically. Opportunistic increases — run only when cash is tight — produce clustered move-outs and no learning curve. A standing cadence produces a rolling series of measurable experiments, and after three or four batches you know your own facility's elasticity better than any benchmark could tell you.
One implementation note that saves real money: hold the ECRI queue and the online pricing engine in the same system, or at minimum reconcile them weekly. When street rates move and the in-place comparison does not update, the queue prioritizes the wrong tenants and the measured spread is fiction.
What the numbers typically look like and how long changes take
Benchmarks are useful as sanity checks, not targets. The most reliable comparison is always your own facility's trailing twelve months, because unit mix, climate-controlled share, market tier, and vintage all shift the ranges substantially. With that caveat, here are the shapes practitioners see.
Occupancy. Stabilized facilities generally run physical occupancy in the high 80s to low 90s. A lease-up property is a different animal entirely — it may take 24 to 36 months to reach stabilization depending on market absorption, and judging it against stabilized benchmarks during that window produces bad decisions. The gap between physical and economic occupancy at a discount-heavy facility often runs ten to fifteen points; at a tightly managed one it narrows considerably, though it never closes completely because some spread between in-place and street rates is healthy and intentional.
Rate structure. Climate-controlled units command a meaningful premium over comparable non-climate space, commonly in the range of a quarter to roughly forty percent more per square foot depending on market and climate. Smaller units almost always carry a higher rate per square foot than larger ones — a 5x5 will out-earn a 10x20 on a per-foot basis every time — which is why unit-mix analysis matters and why RevPAF at the facility level must be read alongside RevPAF by unit type. Published street rate benchmarks from market research firms are directionally useful, but they lag and they average across wildly different submarkets. Shop your own three nearest competitors monthly; that data is free, current, and specific.
Rate spread. A street-to-in-place spread in the twenty to forty percent range is common and represents healthy pricing runway. A spread compressed into single digits means one of two things: either you have been running increases aggressively and have caught up to market, or your street rates have fallen. Those require opposite responses, so check which one it is before acting.
ECRI sizing and response. Institutional operators typically run increases in the high single digits to mid teens on a nine-to-twelve-month cadence. The associated move-out response is modest — a few percentage points of incremental churn above baseline — and the arithmetic strongly favors the increase because the retained tenants' lift is multiplied across the whole cohort while the churn cost applies to a small slice, and vacated units backfill at street rate. Run your own numbers before adopting anyone else's percentage: measure your baseline monthly move-out rate first, then attribute only the excess above baseline to the increase.
Length of stay. Median tenancies commonly land somewhere in the range of ten to eighteen months, but the average is dragged upward by a long tail. The economically important insight is that tenants past roughly the two-year mark are dramatically more profitable than new ones — acquisition cost is fully amortized, they have absorbed multiple increases, and they generate almost no management overhead. Protect that cohort deliberately: they are the ones for whom a poorly timed or oversized increase does the most damage.
Online funnel. Session-to-reservation conversion in the low single digits is typical for storage sites, and reservation-to-move-in conversion sits substantially higher because reservation intent is strong. Both stages respond to unglamorous fixes: page load speed, accurate live unit availability, transparent pricing without a required phone call, and a working online move-in that completes the lease and payment without staff involvement. These are engineering and configuration changes, not campaigns, and they usually land within a few weeks.
Timelines to impact. Website conversion fixes show up in reservation counts within two to four weeks. A promo restructure shows up in economic occupancy within one to two months. An ECRI batch shows measurable net lift at sixty days and a confident read at ninety. RevPAF moves gradually because it is a blended number — expect one to two quarters before a program change is unambiguous in the trend. NOI margin lags everything, and a full quarter of clean data is the minimum before drawing conclusions.
Cost to instrument. Most of this requires no new spending. Management platforms already produce the underlying data; the work is defining the metrics consistently and building the report once. Where costs do appear, they are modest and concentrated in website performance work and competitor rate shopping. The expensive alternative — outsourcing operations to a third-party manager — trades a percentage of revenue for institutional revenue management, and whether that math works depends almost entirely on how much of the discipline above you are willing to run yourself.
Where operators consistently get this wrong
Worshipping physical occupancy. This is the dominant failure and it feels like success while it happens. A permanent first-month-free offer plus a manager empowered to discount will fill a building. It will also compress your street rates, widen the concession drag, and cap RevPAF. The tell is a high physical occupancy sitting next to a mediocre economic occupancy and a narrow rate spread. If you are above the mid-90s physically and your rates have not moved in a year, you are underpriced, not popular.
Skipping ECRI out of fear. Owners imagine a mass exodus. The measured response is far smaller, and the fear is asymmetric: the cost of an increase that goes slightly too far is a handful of move-outs that backfill at street rate; the cost of never running one is permanent suppression of the largest revenue lever available. The correct response to uncertainty is a small batch, not no batch.
Running ECRI without measuring net lift. The mirror-image error. Sending increases and never reconciling the resulting move-outs, downtime, and backfill rates means you never learn your facility's elasticity and you cannot size the next batch intelligently. Gross lift always looks great. Net lift is what changed.
Letting physical and economic occupancy drift apart unnoticed. If nobody computes economic occupancy monthly, the discount drag compounds silently. Managers grant discretionary concessions to close rentals, promos apply to unit types that never needed them, and delinquent accounts linger. Twelve points of gap accumulates one small decision at a time.
Treating the website as a brochure. Slow load times, availability that does not reflect the actual rent roll, prices hidden behind a call-for-quote, and an online move-in flow that dead-ends at a form all bleed conversions every single day. Because the loss is invisible — you never see the person who left — this failure persists for years. Test the full online move-in path yourself, on a phone, monthly.
Reacting to move-out spikes a quarter late. Without weekly net move-in tracking, a bad increase batch or a new competitor opening two miles away shows up in the monthly financials long after the cheap responses expired. Weekly is not excessive here; the fixes are cheap when caught early and expensive when caught late.
Reporting facility-level averages only. A single blended occupancy number hides that your 10x10s are full and your 10x30s are half empty. Every core metric — occupancy, spread, RevPAF, net move-ins — should be reported by unit type. The action is almost always unit-type specific.
Ignoring delinquency in the economic occupancy calculation. Billed-basis and cash-basis economic occupancy are different metrics with different remedies. Reporting only one of them means either your collections problem or your pricing problem stays invisible.
Choosing which lever to pull
Given a set of readings, the decision is usually obvious once the metrics are separated properly. The framework below routes from diagnosis to action.
Start with the physical-versus-economic gap. If physical occupancy is high and economic occupancy is well below it, the problem is discounting and stale in-place rates — the fix is trimming promos to slow-moving unit types and building the ECRI queue. If both are high and moving together, you have pricing power you are not using; raise street rates on the tightest unit types and watch reservation volume for two weeks before extending it further.
If physical occupancy is low, the next question is whether it is a demand problem or a conversion problem. Check the online funnel first, because it is cheaper to fix. If sessions are healthy but reservations are not, the site is the bottleneck — availability accuracy, speed, pricing transparency, form length. If reservations are healthy but move-ins are not, the handoff is broken — confirmation flow, follow-up cadence, or a move-in process that requires a call during business hours. Only after both funnel stages check out should you conclude the market is soft and consider rate reductions, and even then reduce on specific unit types rather than across the board.
If the street-to-in-place spread has compressed to single digits, stop planning increases and diagnose why. Either you have already captured the runway, in which case growth has to come from occupancy and street rate, or your street rates have slipped relative to competitors, in which case the fix is upward repricing on new rentals, not tenant increases.
If NOI margin is falling while revenue metrics hold steady, the problem is on the expense line — a property tax reassessment, an insurance renewal, or a utility increase — and no amount of revenue management addresses it. Handle it as an expense issue.
A closing note on cadence, because the framework only works if it runs on a schedule. Daily, confirm live website availability and check competitor street rates. Weekly, review net move-ins and occupancy by unit type and both stages of the online funnel — this is where leaks surface early. Monthly, run economic occupancy on both bases, RevPAF by unit type, and the net-lift read on the most recent increase batch. Quarterly, step back to NOI margin, length-of-stay cohorts, and the translation of RevPAF gains into implied asset value at your market cap rate. That last step is the one owners skip and the one that matters most at sale, because in a business valued on a cap rate applied to NOI, a durable improvement in monthly revenue per square foot compounds into a materially different exit number.
Related questions
Should a facility ever run above 95% physical occupancy?
Briefly, during peak season or lease-up momentum, yes. Sustained occupancy above the mid-90s almost always indicates underpricing — the market is telling you it would pay more. The correct response is raising street rates on the tightest unit types, not celebrating the fill rate.
How often should ECRIs be scheduled?
A standing cadence of roughly nine to twelve months per tenant is the common pattern, run in rolling batches rather than a single annual sweep. Batching lets you measure response, size the next increase from your own data, and avoid clustering move-outs into one month.
Does climate-controlled space change the KPI set?
Not the metric definitions, but it changes the ranges. Climate-controlled units carry higher rates per square foot and higher operating costs, so report RevPAF and occupancy separately for climate and non-climate space. Blending them hides which half of the building is underperforming.
What is the single most useful metric if I can only track one?
RevPAF. It collapses occupancy and rate into one figure that cannot be inflated by discounting your way to a full building or by holding rates high on an empty one. Track it monthly by unit type against your own trailing twelve months.
How do I benchmark against competitors without paid data?
Shop them directly. Pull their published street rates by unit size monthly from their own websites, note their promo offers, and track whether their availability tightens or loosens. That is current, specific, and free — far more useful than a national average.
FAQ
What is the difference between physical and economic occupancy?
Physical occupancy is the share of rentable units or square feet currently leased. Economic occupancy is rent actually billed divided by gross potential rent at current street rates for the same unit mix. A facility can be physically full while collecting substantially less than its potential, because promotional rates, manager discounts, waived fees, and long-tenured tenants on stale rates all reduce collected rent without reducing the fill rate. The gap between the two numbers is where revenue management operates.
Why is RevPAF better than tracking occupancy and rate separately?
Because occupancy and rate trade against each other, and either one alone can be manipulated. Deep discounting produces high occupancy with poor revenue; aggressive pricing produces high rates with empty units. Revenue per available square foot divides realized rent by total rentable square footage, so it captures both simultaneously. It is the closest thing self-storage has to a single scoreboard, and it normalizes across facilities of different sizes and unit mixes.
Will raising rates on existing tenants drive them away?
Some will leave, but far fewer than owners fear, because moving stored belongings requires a truck, labor, and a destination. Measured properly — excess move-outs above your baseline churn rate, net of the revenue lift from tenants who stayed and the backfill at street rate on units that vacated — a well-sized increase is reliably net positive. Start with a small batch, measure at sixty and ninety days, and size the next one from your own result rather than a benchmark.
How do I track online conversion for a self-storage site?
Split it into two stages. First, sessions to reservations — this measures whether the site presents accurate availability, transparent pricing, and a fast path to booking. Second, reservations to completed move-ins — this measures whether the handoff, confirmation, and move-in process actually closes. Collapsing both into one percentage hides which stage is failing, and the fixes for the two stages are entirely different.
Which metrics belong on a weekly review versus a monthly one?
Weekly: net move-ins, occupancy by unit type, and both online funnel stages. These move fast and the fixes are cheap when caught early. Monthly: economic occupancy on billed and cash bases, RevPAF by unit type, concession drag, and net lift on the latest rate-increase batch. Quarterly: NOI margin, length-of-stay cohorts, and the cap-rate translation of operating gains into asset value.
Does this KPI set work for a facility still in lease-up?
The definitions hold but the benchmarks do not. A lease-up property is climbing toward stabilization over a multi-year window, so judging it against stabilized occupancy ranges produces panic-driven discounting. During lease-up, weight absorption pace, cost per move-in, and street rate integrity more heavily, and defer RevPAF and NOI margin comparisons until the property approaches its stabilized fill.
Sources
- https://www.ssa.com/ — Self Storage Association industry data, demand drivers, and operating benchmarks
- https://investors.publicstorage.com/ — Public Storage investor relations, same-store occupancy and revenue disclosures
- https://ir.extraspace.com/ — Extra Space Storage investor relations and quarterly operating supplementals
- https://ir.cubesmart.com/ — CubeSmart investor relations, same-store revenue and occupancy reporting
- https://www.yardimatrix.com/ — Yardi Matrix national self-storage research and street rate reporting
- https://www.storable.com/ — Storable self-storage management software and industry insights
- https://www.insideselfstorage.com/ — Inside Self-Storage operator benchmarks and market coverage
- https://www.sec.gov/edgar/searchedgar/companysearch — SEC EDGAR, for primary REIT 10-K and 10-Q filings
Related on PULSE
- [What are the most important KPIs every self-storage facility should track in 2027?](/knowledge/ik0456)
- [Top 10 Self-Storage Facility Revenue KPIs](/knowledge/ik0669)
- [What are the key sales KPIs for the Equine Boarding & Training Facilities industry in 2027?](/knowledge/ik0246)
Read it free — or make it yours for $1.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
 pulse-industry-kpisWhat are the key sales KPIs for the Commercial Architecture and Engineering Firm industry in 2027?
 pulse-industry-kpisThe Best KPIs for Independent Bakeries in 2027
 pulse-industry-kpisWhat are the key sales KPIs for the Luxury Fashion House industry in 2027?
 pulse-industry-kpisWhat are the key sales KPIs for the Clinical Trial Site Network industry in 2027?
 pulse-industry-kpisWhat are the key sales KPIs for the Industrial Diamond & Superabrasive Tool Manufacturing industry in 2027?
 pulse-industry-kpisWhat are the key sales KPIs for the Architectural Hardware Specification Consulting industry in 2027?
 pulse-industry-kpisWhat are the key sales KPIs for the Used Vehicle Retail industry in 2027?
 pulse-industry-kpisWhat are the key sales KPIs for the Construction Equipment Rental industry in 2027?
 pulse-industry-kpisWhat are the key sales KPIs for the Medical Device OEM industry in 2027?
 pulse-industry-kpisWhat are the key sales KPIs for the Health Club and Gym Operations industry in 2027?