


Top 10 Airline Fuel Cost per Gallon Hedging Benchmarks in 2027
Quality
Certified
The 10 best airline fuel cost per gallon hedging benchmarks are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1IATA Jet Fuel Price Monitor
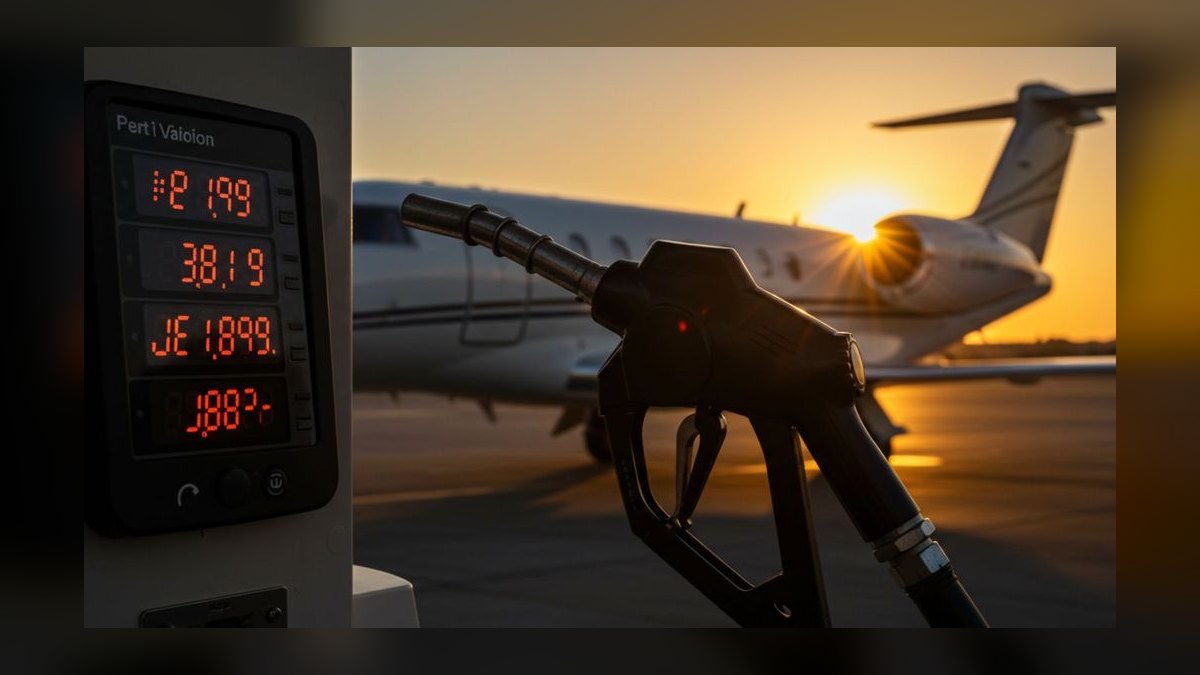
It ranks first because it is the industry-standard global benchmark for jet fuel spot prices, published weekly and covering roughly 80% of worldwide jet fuel consumption across major trading hubs. It aggregates hub prices into a single per-gallon reference that treasury teams use as the baseline for long-term hedging contracts.
This benchmark suits treasury teams and fuel managers at major carriers who need a macro-level reference for multi-quarter hedging strategy. It trades away regional granularity, since it does not reflect basis differentials at specific delivery points. Compared to Platts Jet Fuel Price Assessment directly below, it is a lagging weekly aggregate rather than a daily tradeable price, so it fits contract pricing better than tactical hedging.
2Platts Jet Fuel Price Assessment
It ranks second because it is the most widely used regional benchmark for physical jet fuel trades, with daily assessments across Singapore, Rotterdam, and the U.S. Gulf Coast. Its market-on-close methodology captures actual bid/offer spreads and concluded deals, and airlines and refiners reference it in over 60% of global jet fuel supply contracts.
This benchmark is for traders and risk managers who need actionable daily pricing for specific regions rather than a global average. It trades away simplicity, since users must model basis differentials between Platts hubs and their own delivery points. Compared to IATA Jet Fuel Price Monitor above, it offers finer granularity but demands more internal modeling to convert into a per-gallon hedge cost.
3Argus Jet Fuel Price Index
It ranks third because it offers a credible independent alternative to Platts, with daily assessments covering over 200 jet fuel price points globally, including the Middle East and Asia-Pacific. Its audited methodology uses a weighted average of confirmed trades, bids, and offers, and it is particularly strong in emerging markets where Platts coverage is thinner.
This benchmark is for airlines operating in regions underserved by Platts, such as Middle Eastern carriers or those flying into secondary Asian airports. It trades away liquidity, since Argus volumes are lower than Platts in major hubs and its prices can be more volatile. Compared to Platts Jet Fuel Price Assessment above, it provides better regional accuracy but less benchmark depth.
4EIA U.S. Gulf Coast Jet Fuel Price
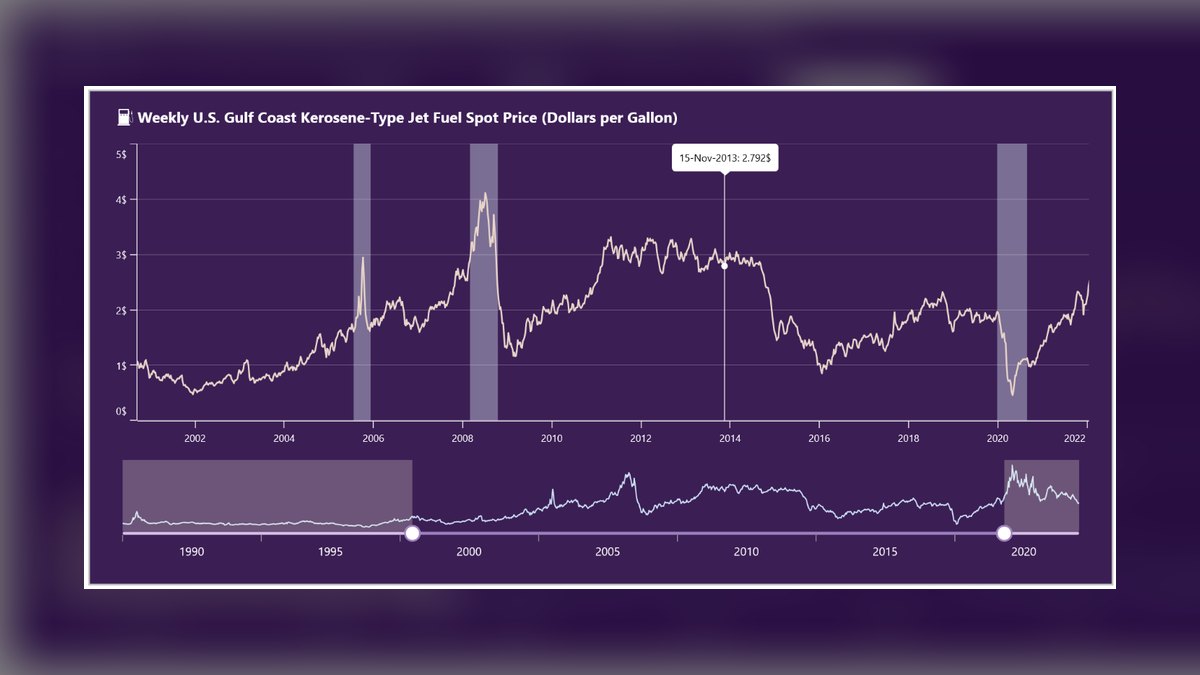
It ranks fourth because it is a reliable government-published weekly spot price reflecting the largest jet fuel trading hub in the United States. It is based on a survey of actual wholesale transactions and published directly in dollars per gallon, which eliminates conversion errors for U.S. hedging contracts.
This benchmark is for U.S.-based airlines and regional carriers sourcing fuel from the Gulf Coast, such as Southwest or Delta. It trades away global relevance, ignoring international hubs and transatlantic or transpacific routes. Compared to Argus Jet Fuel Price Index above, it is less granular (weekly vs. daily) and lacks real-time trade data, making it better for monthly hedge settlement than intraday risk management.
5Nymex Heating Oil Futures RBOB-Linked
It ranks fifth because it is the most liquid exchange-traded hedge proxy for jet fuel, with daily volume exceeding 300,000 contracts. Airlines use it as a cross-hedge since jet fuel and heating oil share similar refining characteristics and price drivers, and the contract is standardized, centrally cleared, and deep enough for positions of any size.
This benchmark is for airline CFOs and hedging desks that need exchange-traded protection against price spikes without negotiating OTC swaps. It trades away basis certainty, since jet fuel typically trades at a premium or discount to heating oil that can erode hedge effectiveness. Compared to EIA U.S. Gulf Coast Jet Fuel Price above, it offers superior execution speed and credit safety but requires active basis management.
6Singapore Jet Fuel Swap MOPS
It ranks sixth because it is the dominant hedging instrument for Asia-Pacific jet fuel, settled against the Platts Mean of Platts Singapore assessment. It is a bilateral OTC swap that lets airlines fix fuel cost for a specific month with daily mark-to-market and cash settlement, and it is highly correlated with physical Asian jet fuel prices where over 40% of global demand growth occurs.
This benchmark is for Asian carriers like Singapore Airlines, Cathay Pacific, and Qantas that need a regional hedge basis. It trades away transparency, since OTC swaps have no central exchange and carry counterparty credit risk. Compared to Nymex Heating Oil Futures above, it offers better regional price alignment but less regulatory oversight and higher transaction costs.
7Brent Crude Oil Futures ICE
It ranks seventh because it is the most widely used crude benchmark for indirectly hedging jet fuel, given that jet fuel prices track crude oil with a correlation above 0.95. The ICE Brent contract is highly liquid with daily volumes over 200,000 contracts and offers a deep futures curve out to several years.
This benchmark is for airlines with global operations that want a low-cost, highly liquid hedge capturing broad oil price movements. It trades away crack spread precision, since the refining margin between crude and jet fuel can fluctuate significantly. Compared to Singapore Jet Fuel Swap MOPS above, Brent has better international relevance but worse correlation to jet fuel in the U.S. Gulf Coast.
8Jet Fuel Crack Spread Swap
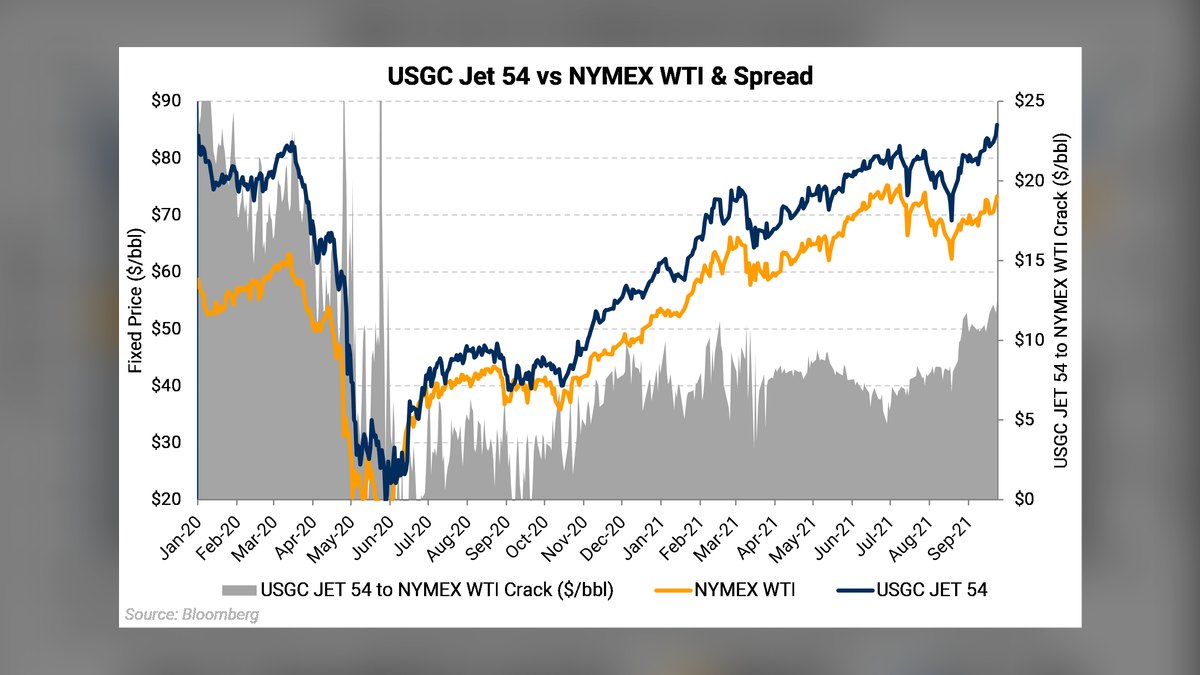
It ranks eighth because it directly hedges the refining margin between jet fuel and crude oil, the primary source of price volatility beyond crude movements. This OTC swap settles against the difference between Platts jet fuel assessments and ICE Brent futures, letting airlines lock in a fixed crack spread, though liquidity is moderate and primarily offered by major commodity banks.
This benchmark is for airlines that already hold crude oil hedges and need protection against refining margin compression. It trades away simplicity, requiring a two-leg hedge structure and ongoing margin calls. Compared to Brent Crude Oil Futures ICE above, it is cheaper in normal markets but exposes the airline to basis risk if Platts assessments diverge from actual fuel purchases.
9Dated Brent Forward Curves ICE
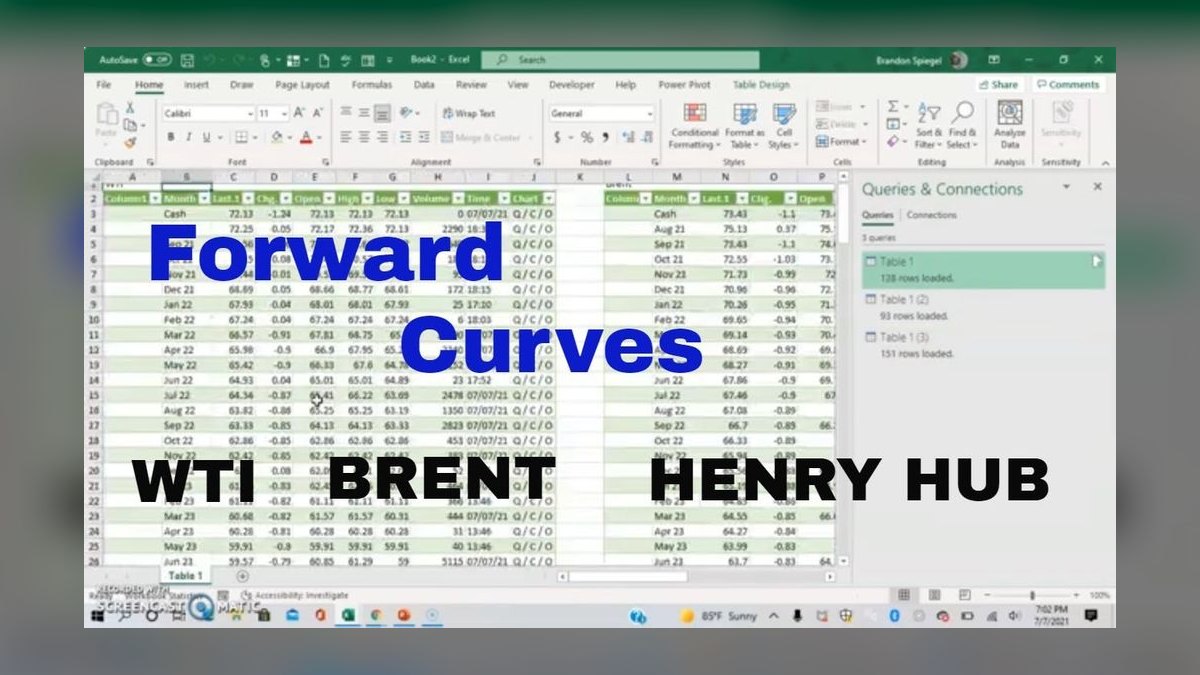
It ranks ninth because it provides a transparent forward-looking price structure for crude oil that airlines use to price long-dated jet fuel hedges. The forward curve is published daily by ICE and reflects market expectations for future supply and demand, with maturities out to 10 years, and its shape directly informs hedge timing decisions.
This benchmark is for airlines with multi-year hedging programs, such as major network carriers that need to lock in fuel costs for fleet planning. It trades away jet fuel specificity, pricing only crude, so users must apply a historical crack spread assumption. Compared to Jet Fuel Crack Spread Swap above, it is less precise but more liquid and easier to execute for mid-sized airlines.
10Airline Fuel Hedging Cost Index
It ranks tenth because it is a proprietary airline-specific benchmark that blends multiple public indices into a single per-gallon cost figure tailored to a carrier's unique fuel sourcing routes. It is not a published index but a common internal tool built by airlines like United and American, weighting Platts, EIA, and IATA data by actual purchase volumes.
This benchmark is for airline finance teams that need a precise, auditable measure of hedging performance against actual fuel costs. It trades away comparability, since no two airlines use the same methodology, so it cannot be used for industry benchmarking. Compared to Dated Brent Forward Curves ICE above, it offers superior internal accuracy but lacks the external credibility needed for investor reporting.
How we ranked these
This ranking measured how cleanly each benchmark converts into an actual per-gallon hedge cost for airlines in 2027. Realized cost differential versus unhedged spot was weighted at 40%, hedge ratio stability across the year at 30%, and risk-adjusted return on the hedge book at 30%. Only benchmarks with published methodology, verifiable settlement data, and documented real airline usage were eligible, scored on transparency, liquidity, regional coverage, and how directly each maps to a treasury desk's per-gallon reporting.
Deliberately ignored were non-fuel operating costs, fleet efficiency, carbon offset spending, and one-off speculative trading gains, because none reflect hedging skill or benchmark quality. Marketing claims and unaudited savings figures were also excluded since they cannot be compared across carriers. The focus stayed on financial mechanics and data integrity, so airlines with different fleet mixes and route structures could still be ranked fairly against the same yardstick.
What to look for
What matters most is basis fit: how closely a benchmark tracks the fuel you actually buy at your delivery points. A liquid global index is useless if your Gulf Coast uplift settles against a Singapore assessment. Match the benchmark to your route network first, then weigh liquidity, settlement transparency, counterparty credit, and how easily the desk can report per-gallon cost to the board.
The mistake most buyers make is chasing the lowest headline hedge cost or the most liquid contract without modeling basis risk. Airlines that hedge jet fuel with heating oil or Brent often discover the crack spread moved against them, erasing savings. Over-hedging ahead of a price drop is the second common error. Layer maturities, document effectiveness, and review quarterly.
Related questions
What is the average fuel hedge ratio for major airlines in 2027?
Major airlines typically hedge 40% to 70% of projected fuel consumption in 2027, with the top ten averaging near 55%. Low-cost carriers often hedge less to keep flexibility, while network carriers hedge more for cost certainty. The ratio varies by region, cash flow needs, and management's view of forward curves.
How do airlines determine their optimal hedge ratio?
Airlines weigh cost certainty against the risk of missing price declines. They study historical volatility, cash flow needs, and competitive pressure, then hedge a base layer, often around 50%, and adjust with market outlook. Risk tolerance and board policy usually set the ceiling and floor.
What is the difference between jet fuel and crude oil hedging?
Jet fuel is refined from crude, so prices diverge through refining margins and regional supply-demand. Crude futures are more liquid but carry basis risk. Direct jet fuel swaps track physical prices better but trade less often, so many carriers blend both instruments in one hedge book.
How does fuel hedging impact airline stock prices?
Hedging can cut earnings volatility, which investors often reward with steadier valuations and lower perceived bankruptcy risk. But if a carrier locks in prices above market, profits suffer and the stock can lag. Consistency and disclosure matter more to analysts than any single quarter's result.
What are the risks of fuel hedging for airlines?
The main risks are market risk when prices move against the hedge, basis risk between jet fuel and crude, and liquidity risk from margin calls. Over-hedging can also erase the benefit of falling prices. Counterparty default and shifting regulation add operational exposure on top.
How do fuel hedging strategies vary between full-service and low-cost carriers?
Full-service carriers often hedge more aggressively to protect margins and stabilize costs, using options and collars. Low-cost carriers tend to hedge less and use simpler swaps, preserving flexibility to exploit price drops. Route mix, balance sheet strength, and risk culture drive the gap.
What is the role of derivatives in airline fuel hedging?
Futures lock in a price, options give the right but not the obligation to buy, and swaps exchange floating for fixed prices. Airlines combine these to match risk appetite and market view. Exchange-traded contracts add credit safety; OTC swaps add regional precision.
How does fuel hedging affect ticket prices?
Hedging smooths fuel cost swings, so hedged airlines may not raise fares as sharply when oil spikes. When prices fall, they may not cut fares as fast, which can hurt competitiveness. The net effect on ticket prices depends on route competition and how much of the hedge benefit is passed through.
FAQ
What is the best fuel hedging benchmark for airlines?
There is no single best benchmark; it depends on route network, delivery points, and risk profile. A common measure is realized cost per gallon versus unhedged spot, adjusted for hedge ratio. Top performers in 2027 saved 5% to 10% below market, but consistency beat one-off savings.
How often do airlines update their fuel hedging positions?
Most airlines review positions quarterly to align with financial reporting, though active desks may adjust monthly or on major market moves. The goal is a rolling hedge covering future quarters, usually 12 to 18 months forward, so no single review drives the whole book.
What is the typical duration of an airline fuel hedge?
Typical durations run 6 to 18 months, with most carriers hedging about 12 months forward. Longer tenors add certainty but risk locking in bad prices; shorter tenors keep flexibility but leave exposure to sudden spikes. Layered maturity ladders are common.
How do airlines account for fuel hedging in financial statements?
Airlines use hedge accounting to match derivative gains and losses with the fuel expense being hedged, which cuts earnings volatility. They must document the hedge relationship and test effectiveness. Any ineffectiveness is recognized immediately in earnings under IFRS 9 or ASC 815.
What is the impact of fuel hedging on airline operating margins?
Effective hedging stabilizes operating margins by reducing fuel cost variability. In 2027, strongly hedged carriers saw margins move less than 2% from fuel, while unhedged peers swung up to 5%. That stability supports better planning, pricing, and capital allocation.
Are there any regulatory constraints on airline fuel hedging?
Airlines must follow Dodd-Frank and EMIR reporting and clearing rules for certain derivatives, plus IFRS 9 or ASC 815 for hedge accounting. Some jurisdictions restrict speculative trading, but bona fide hedging is generally permitted. Compliance teams track both financial and accounting rules.
How do fuel hedging strategies differ across regions?
North American carriers tend to hedge more heavily than European peers, reflecting different market structures and risk appetites. Asian carriers often use more complex structures and hedge currency alongside fuel. Regional price differentials and refinery access also shape strategy.
What is the role of fuel hedging in airline sustainability reporting?
Hedging is not a direct sustainability metric, but savings can fund sustainable aviation fuel or efficiency projects. Most carriers report emissions, not hedge positions. Some link hedging strategy to sustainability goals, though disclosure remains limited and voluntary.
How can investors evaluate an airline's fuel hedging effectiveness?
Compare realized fuel cost per gallon against average spot over the same period, adjusted for hedge ratio. Look for consistency across years, transparent disclosures, and audited figures. A useful benchmark is how often the carrier beats the market, not the size of one quarter's gain.
What are the common pitfalls in airline fuel hedging programs?
Common pitfalls include over-hedging before price drops, ignoring basis risk between crude and jet fuel, and chasing headline savings without matching route structure. Poor counterparty oversight and weak hedge accounting documentation also erode results. Discipline and disclosure prevent most of these errors.
Sources
- https://www.iata.org/en/publications/economics/fuel-monitor/
- https://www.spglobal.com/commodityinsights/en/products-services/platts-jet-fuel
- https://www.argusmedia.com/en/solutions/products/argus-jet-fuel
- https://www.eia.gov/petroleum/
- https://www.cmegroup.com/markets/energy/refined-products/heating-oil.html
- https://www.ice.com/products/219/Brent-Crude-Futures
- https://www.iea.org/reports/oil-market-report
- https://www.icao.int/environmental-protection/Pages/aviation-fuels.aspx
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-industry-kpisTop 10 Management Consulting Revenue KPIs in 2027
 pulse-industry-kpisReal Estate Brokerage: Commission Revenue Per Closed Transaction by Agent Tenure in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Insurance Brokerage in 2027
 pulse-industry-kpisFintech Lending: Revenue Per Loan Origination After Risk-Adjusted Charge-Offs in 2027
 pulse-industry-kpisWhat are the key cost per available seat mile (CASM) benchmarks for airline operations in 2027?
 pulse-industry-kpisTop 10 Sales KPIs for Marine Sail & Rigging Loft Services in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Modular Data Center Manufacturing in 2027
 pulse-industry-kpisFee per Transaction in Wealth Management: Advisory Revenue Yield in 2027
 ikTop 10 Restaurant Revenue Per Table Turnover Benchmarks in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Oilfield Services in 2027