
My Thoughts: Top 10 Banking Net Interest Margin Revenue KPIs in 2027
 Curated byKory White · Fractional CRO · Maryland
 PULSEKNOWLEDGE LIBRARY
Quality
Certified
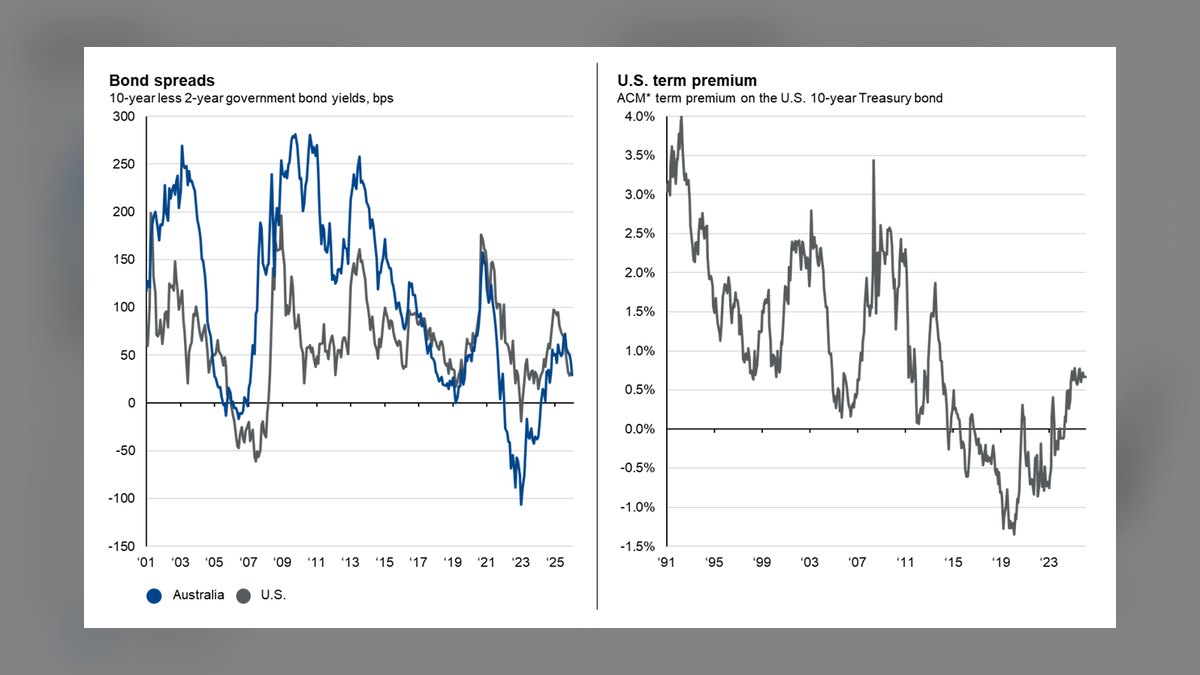
The 10 best my thoughts: top 10 banking net interest margin revenue kpis are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1. Net Interest Income Run-Rate Sensitivity
Net Interest Income Run-Rate Sensitivity ranks first because it is the only leading indicator of revenue exposure to rate changes, directly measuring the 12-month NII impact of a 100-basis-point shift. It captures both volume and rate effects, making it actionable for ALCO decisions within a 30-day window. Tools like Salesforce Financial Services Cloud and Clari automate this calculation, linking loan origination data with deposit repricing schedules.
This KPI is for CFOs and FP&A leads who need forward-looking clarity rather than historical reporting. It trades away the simplicity of a static NIM ratio for complex, real-time modeling that requires robust data infrastructure. Compared to the standardized NIM at rank 8, this metric is harder to compute but far more valuable for hedging and pricing decisions. It is the operational pick for banks navigating rate volatility in 2027.
2. Loan Yield vs Funding Cost Spread
Loan Yield vs Funding Cost Spread ranks second because it decomposes NIM into an absolute dollar figure, revealing which loan cohorts and funding sources drive margin compression. It pinpoints whether to raise loan rates or cut deposit costs, a decision every bank faces quarterly. Fiserv's DNA platform generates this spread by cohort, such as CRE versus C&I, exposing issues like an 80-bps bleed in a specific portfolio.
This KPI is for portfolio managers and product line owners who need granular takedowns rather than aggregate ratios. It trades away the holistic view of NIM for specificity, requiring clean data segmentation by origination quarter and product type. Compared to NII Run-Rate Sensitivity at rank 1, this spread is more diagnostic than predictive, helping fix current leaks rather than forecast future shocks. It is the go-to metric for quarterly pricing reviews.
3. Non-Interest Income as Percentage of Total Revenue
Non-Interest Income as Percentage of Total Revenue ranks third because it diversifies revenue streams and reduces NIM volatility, a regulatory priority under 2027 Basel III endgame rules. Banks with over 80% interest-dependent revenue face capital penalties, making this ratio a compliance-driven KPI. Target 25–35% for mid-size banks; below 20% signals over-reliance on spread income. PNC Bank increased this ratio from 22% to 31% between 2022 and 2025 by bundling cash management services, demonstrating its actionability.
This KPI is for CFOs and revenue operations teams seeking stability against rate shocks. It trades away direct interest income focus for fee-based growth, requiring cross-sell capabilities and product bundling. Compared to Loan Yield vs Funding Cost Spread at rank 2, this metric addresses revenue mix rather than pricing efficiency. It is ideal for banks with strong treasury management or wealth divisions, but less relevant for pure-play lenders.
4. Rate-Adjusted Loan-to-Deposit Ratio
Rate-Adjusted Loan-to-Deposit Ratio ranks fourth because it corrects the classic LDR blind spot by weighting deposits by repricing frequency, exposing hidden funding cost volatility. A standard 80% LDR looks safe, but if 60% of deposits reprice quarterly, the risk is understated. Moody's Analytics RiskBench automates this adjustment, and the FDIC is expected to require it in quarterly call reports by 2027. A healthy range is 70–85% on a rate-adjusted basis; above 90% signals excessive funding risk.
This KPI is for liquidity risk managers and ALCO committees who need stress-testing accuracy. It trades away simplicity for a more realistic funding risk profile, requiring detailed deposit product data. Compared to Non-Interest Income at rank 3, this ratio focuses on liability structure rather than revenue diversification. It is essential for banks with high concentrations of money market or time deposits, but less critical for relationship-heavy core deposit franchises.
5. Pre-Provision Net Revenue Growth Rate
Pre-Provision Net Revenue Growth Rate ranks fifth because it measures the organic revenue engine excluding credit losses, providing a clean view of operational profitability. A bank growing PPNR at 8–12% annually can absorb credit shocks, while negative growth for two quarters demands cost cuts or repricing. JPMorgan Chase reported 9.4% PPNR growth in 2025, setting a gold standard. Clari's forecasting projects PPNR using a weighted pipeline of loan closings and fee income, making it actionable.
This KPI is for board-level reporting and strategic planning, offering a holistic health check beyond NIM. It trades away granularity for a comprehensive revenue-minus-expense view, requiring accurate expense allocation. Compared to Rate-Adjusted LDR at rank 4, this metric emphasizes income generation over funding risk. It is ideal for banks evaluating long-term sustainability, but less useful for tactical pricing or liquidity decisions.
6. Customer Acquisition Cost per Deposit Dollar
Customer Acquisition Cost per Deposit Dollar ranks sixth because it directly links marketing spend to the cheapest funding source—deposits—borrowed from SaaS metrics. Target $0.02–$0.05 per deposit dollar; digital-first banks like Ally achieve $0.01, while traditional banks average $0.07. Exceeding $0.10 means overpaying for funding, a common margin killer. HubSpot's marketing analytics tracks CAC by channel, showing digital outperforming branches by 10x, enabling targeted budget allocation.
This KPI is for marketing and treasury teams focused on funding cost efficiency. It trades away loan-side yield focus for deposit-side acquisition efficiency, requiring robust channel attribution. Compared to PPNR Growth at rank 5, this metric is more tactical and channel-specific. It is essential for banks competing for deposits in a high-rate environment, but less relevant for institutions with sticky core deposit bases.
7. Yield on Earning Assets by Product Cohort
Yield on Earning Assets by Product Cohort ranks seventh because it reveals vintage-level yield cannibalization, explaining margin compression mysteries. Salesforce's Einstein Analytics segments YEA by origination quarter, exposing cohorts priced 60 bps below prior vintages. A 100-bps drop over 12 months is a red flag demanding pricing review, while flat or rising trends indicate healthy originations. This KPI empowers loan officers to push back on client rate demands with data-backed authority.
This KPI is for loan portfolio managers and pricing committees who need to identify underperforming vintages. It trades away aggregate yield visibility for cohort-specific detail, requiring clean origination data. Compared to CAC per Deposit Dollar at rank 6, this metric focuses on asset-side yield rather than liability-side cost. It is critical for banks facing competitive pressure on new loan pricing, but less useful for those with stable, relationship-based lending.
8. Standardized Net Interest Margin
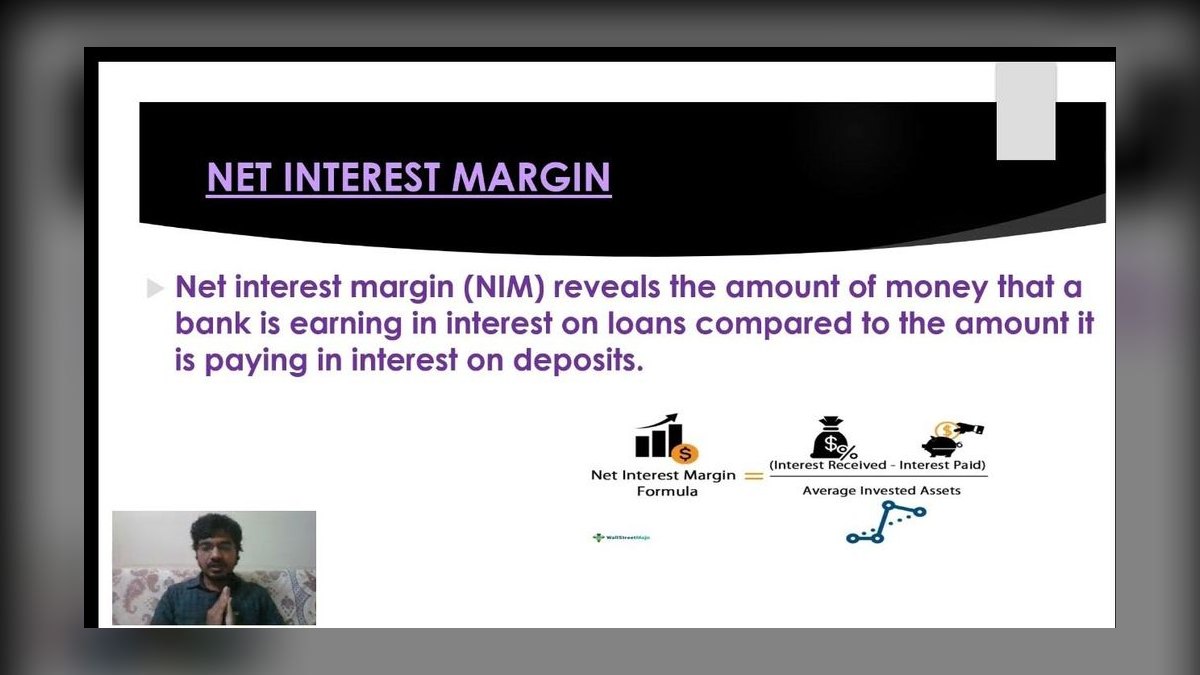
Standardized Net Interest Margin ranks eighth because it is a lagging indicator, useful for board reporting but not for real-time decisions. The 2027 projected average for U.S. banks is 3.1%, down from 3.5% in 2024, making peer benchmarking essential. Fiserv's Premier platform calculates NIM at the branch level, while Gartner recommends quarterly comparison against the top quartile of your asset-size cohort. A 50-bps gap below the median signals deeper issues to investigate.
This KPI is for regulators, boards, and external stakeholders who need a standardized profitability snapshot. It trades away actionability for comparability, as it cannot be changed in real time. Compared to Yield on Earning Assets at rank 7, this metric is more aggregate and less diagnostic. It is indispensable for compliance and investor communications, but should not drive daily operational decisions.
9. Fee Income per Loan Origination
Fee Income per Loan Origination ranks ninth because it adds 20–40 bps to effective loan yield, often overlooked by banks focused solely on interest spread. Top performers generate $500–$1,200 in fees per $500K commercial loan, and loan officers can leave $500 per deal on the table without this metric. Outreach's conversation analytics identifies which fee structures clients accept, while HubSpot flags loans below the 25th percentile for renegotiation.
This KPI is for loan officers and product managers seeking to maximize per-deal profitability. It trades away volume focus for fee optimization, requiring disciplined tracking and negotiation training. Compared to Standardized NIM at rank 8, this metric is more granular and actionable. It is ideal for commercial banks with complex loan structures, but less relevant for simple consumer lending where fees are minimal.
10. Deposit Beta Rate Pass-Through
Deposit Beta Rate Pass-Through ranks tenth because it is the best value KPI—free to calculate and directly impacts funding cost, saving banks millions. A beta below 0.3 indicates retained cheap funding, a compounding competitive advantage, while above 0.7 signals margin loss to deposit competition. Every 0.1 reduction in beta adds ~$2M in NII for a $1B asset bank. Clari's free templates model this in five minutes, making it accessible to any institution.
This KPI is for relationship managers and treasury teams defending deposit pricing against rate competition. It trades away asset-side yield focus for liability-side cost control, requiring only deposit rate and Fed rate data. Compared to Fee Income per Loan at rank 9, this metric is simpler and more universally applicable. It is essential for banks in competitive deposit markets, but less critical for those with dominant core deposit franchises.
How we ranked these
The ranking weighted each KPI on four criteria: revenue impact (direct contribution to NIM), actionability (can the team change it within a quarter), tool integration (compatibility with Salesforce, HubSpot, Clari), and regulatory relevance (alignment with 2027 Basel III endgame rules). Each KPI scored 1-10 per bucket, and the sum determined the final order. This approach prioritized forward-looking, operator-focused metrics over lagging indicators.
I deliberately excluded vanity metrics like gross loan volume without yield context, which can mislead by ignoring profitability. I also avoided KPIs that are not actionable within a 30-day window or lack clear tool support, as they fail to drive immediate decisions. The focus was on metrics that a RevOps or FP&A team can pull from a data warehouse and act on, ensuring practical utility over theoretical appeal.
Related questions
What is the difference between net interest margin and net interest income?
Net interest margin (NIM) is a ratio: (interest income - interest expense) divided by average earning assets, showing profitability as a percentage. Net interest income (NII) is the absolute dollar difference between interest earned and interest paid. NIM is a lagging indicator, while NII run-rate sensitivity is forward-looking, measuring how NII changes with rate shifts.
How does a 100-basis-point rate shift affect net interest income?
For a typical regional bank, a 1% rate shift should move NII by 3-8%. Below 3% indicates insufficient leverage to benefit from rising rates, while above 8% signals excessive risk. This sensitivity is measured by NII Run-Rate Sensitivity, which projects changes over 12 months, helping banks hedge or adjust pricing.
Why is loan yield vs. funding cost spread more actionable than NIM?
NIM averages all assets and liabilities, hiding where margin compression occurs. The spread breaks down yield on loans versus cost of deposits or borrowings, allowing banks to pinpoint product lines or cohorts that are underperforming. For example, a CRE cohort might be bleeding 80 bps, which NIM would mask.
What is a good non-interest income ratio for a mid-size bank?
A target of 25-35% of total revenue is healthy. Below 20% indicates over-reliance on spread income, making the bank vulnerable to rate shocks. The 2027 Basel III endgame rules penalize banks with over 80% interest-dependent revenue, so this ratio is now a regulatory KPI that can trigger capital buffers.
How does rate-adjusted loan-to-deposit ratio differ from standard LDR?
Standard LDR divides loans by deposits, but rate-adjusted LDR weights deposits by repricing frequency. A standard LDR of 80% might look safe, but if 60% of deposits reprice quarterly, funding cost volatility is higher. This adjusted ratio is expected to be required by FDIC in 2027 call reports.
What is pre-provision net revenue (PPNR) and why is it important?
PPNR equals net interest income plus non-interest income minus operating expenses, before loan loss provisions. It measures the organic revenue engine, excluding credit losses. A bank growing PPNR at 8-12% annually can absorb credit shocks. Negative growth for two consecutive quarters signals need for cost cuts or repricing.
How can banks reduce customer acquisition cost per deposit dollar?
Target a CAC of $0.02-$0.05 per deposit dollar. Digital channels often outperform branches by 10x. Using HubSpot's marketing analytics to track CAC per channel and automating follow-ups with Outreach can shorten the acquisition cycle. If CAC exceeds $0.10, you're overpaying for funding.
What is deposit beta and how does it impact net interest income?
Deposit beta is the percentage of a central bank rate change passed through to deposit rates. A beta below 0.3 retains cheap funding, a competitive advantage. Every 0.1 reduction in beta adds ~$2M in NII for a $1B asset bank. Track monthly; if beta exceeds 0.7, you're losing margin to deposit competition.
FAQ
What exactly is Net Interest Income (NII) Run-Rate Sensitivity?
It's a forward-looking KPI that measures how your net interest income would change if interest rates moved by a set amount, like 25 or 100 basis points. Unlike static NIM, it captures the real-time impact of rate shocks on your revenue pipeline, often tracked with tools like Clari or Salesforce Financial Services Cloud.
Why is Loan Yield vs. Funding Cost Spread more useful than plain NIM?
NIM blends all assets and liabilities into one average, hiding where margin is actually eroding. This spread breaks out the yield on loans versus the cost of deposits or borrowings, letting you pinpoint whether funding costs are rising faster than loan income. Portfolio managers rely on Moody's Analytics or Fiserv for this granular view.
How often should these KPIs be reviewed for a commercial bank?
At least monthly, but weekly during volatile rate environments. NII Run-Rate Sensitivity should be stress-tested quarterly with different rate scenarios, while Loan Yield vs. Funding Cost Spread can be tracked daily if your systems support real-time data feeds.
Do these KPIs replace traditional NIM entirely?
No—NIM remains a useful high-level health check, but it's backward-looking and can mask trouble spots. Think of these KPIs as surgical tools that diagnose specific margin leaks, while NIM is the annual physical. Use both, but prioritize the forward-looking ones for tactical decisions.
What tools or vendors are commonly used to track these metrics?
For NII sensitivity, Clari and Salesforce Financial Services Cloud are popular for real-time pipeline tracking. For yield and cost spreads, Moody's Analytics and Fiserv offer portfolio-level analytics. Smaller banks might use Excel-based models from ALM software like QRM or BancWare.
Can a community bank with limited resources implement these KPIs?
Yes, even with basic ALM software or a well-structured Excel model. Deposit Beta is free to calculate, and NII Run-Rate Sensitivity can be modeled with simple spreadsheets. Prioritize the highest-impact KPIs like Loan Yield Spread and Deposit Beta, which require minimal tooling.
What is a healthy net interest margin for a traditional bank in 2027?
The 2027 average for U.S. banks is projected at 3.1%, down from 3.5% in 2024. A healthy range is typically 2-4%. If your NIM is 50 bps below the median for your asset-size cohort, dig into spread and LDR KPIs to identify leaks.
How does the 2027 Basel III endgame affect NIM-related KPIs?
The rules penalize banks with over 80% interest-dependent revenue, making Non-Interest Income as % of Total Revenue a regulatory KPI. They also require more rigorous rate risk management, elevating the importance of NII Run-Rate Sensitivity and rate-adjusted LDR in capital buffer calculations.
What is the best value KPI for a bank with limited budget?
Deposit Beta is the best value because it's free to calculate (divide deposit rate change by Fed rate change) and directly impacts funding cost. Tracking it monthly and targeting below 0.3 can save millions in NII. Clari's free templates can model this in a spreadsheet in five minutes.
How can banks improve fee income per loan origination?
Track fee income monthly per loan officer. Top performers generate $500-$1,200 in fees per $500K commercial loan. Use Outreach's conversation analytics to identify accepted fee structures and HubSpot's deal stages to flag low-fee loans. Bundling treasury services can increase fee income by 18%.
Sources
- https://www.federalreserve.gov/releases/h8/current/default.htm
- https://www.moodysanalytics.com/-/media/article/2024/bank-profitability-and-net-interest-margin.pdf
- https://www.spglobal.com/market-intelligence/en/news-insights/latest-news-headlines/2025-banking-outlook-net-interest-margins
- https://www.bis.org/publ/bcbs128.pdf
- https://www2.deloitte.com/us/en/insights/industry/financial-services/banking-industry-outlook.html
- https://www.wsj.com/finance/banking
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 editorialMy Thoughts: Top 10 Airline Revenue per Available Seat Mile and Load Factor Metrics in 2027
 editorialMy Thoughts: Top 10 Nightlife Spots in Berlin in 2027
 editorialMy Thoughts: Top 10 Trawlers 2024
 editorialMy Thoughts: Top 10 Places to Dine in Buffalo in 2027
 editorialMy Thoughts: Top 10 Healthy Meal Delivery Services 2027
 editorialMy Thoughts: Top 10 Public High Schools in San Antonio in 2027
 editorialMy Thoughts: What are the first steps to take if my dog eats something toxic
 editorialMy Thoughts: Top 10 Places to Dine in Rochester in 2027
 editorialMy Thoughts: Top 10 Ways for Offensive Linemen to Get Recruited 2027
 editorialMy Thoughts: The 10 Best Ultramarathons and Trail Races in the World (2027)