

Should I open or buy a PrimoHoagies franchise in 2027?
 Curated byKory White · Fractional CRO · Maryland
Quality
Certified
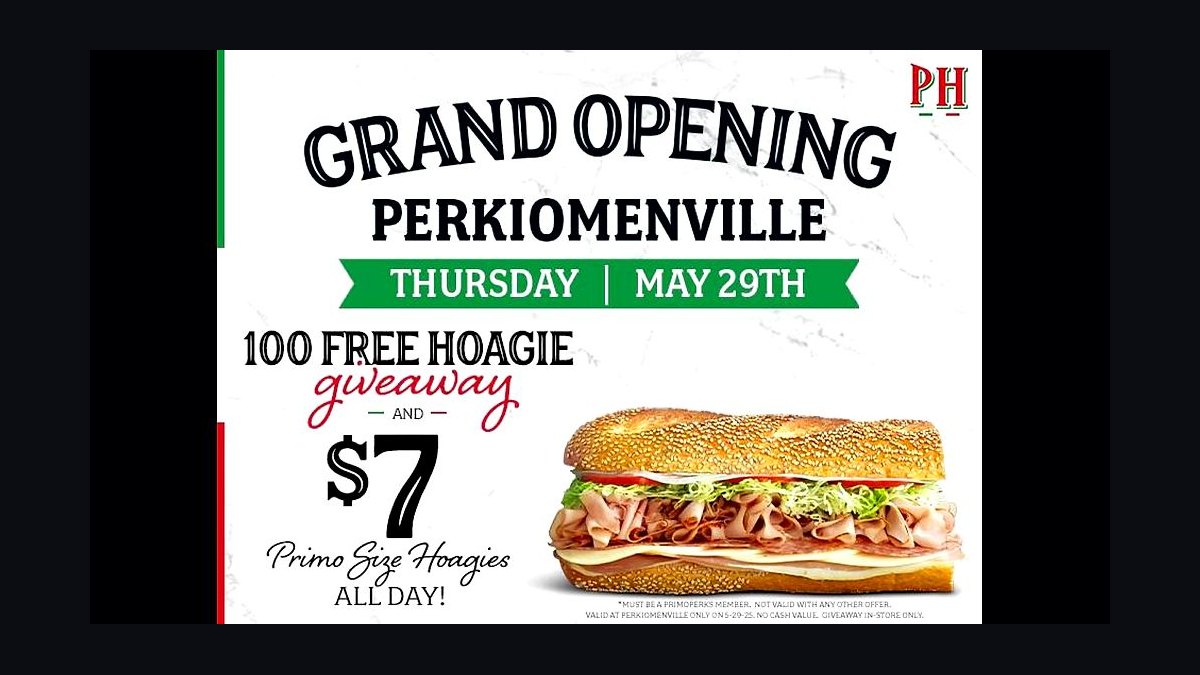
Buy an existing PrimoHoagies before you open a new one — if a profitable unit is available in the Philadelphia–South Jersey core. An existing store hands you day-one cash flow and a proven site. Opening new costs roughly $350,000 to $550,000 all-in and takes 6–12 months before a single hoagie sells.
What a PrimoHoagies franchise actually is, and why the distinction matters
PrimoHoagies is not a sub chain. It is a premium Italian-deli concept founded in Philadelphia in 1992, built on hand-sliced premium meats, a signature sharp provolone, and a seeded Italian roll baked to a proprietary spec. Everything about the unit economics flows downstream from that positioning, and if you evaluate it with a Subway or Jersey Mike's mental model you will misprice the deal in both directions.
Start with what "premium" does to your P&L. A premium deli concept carries a higher food cost than a value sub chain — you are buying better meat, and better meat costs more per pound. In exchange, you charge more per ticket and you attract a customer who is not shopping on price. The trade is real: higher gross revenue per transaction, thinner percentage margin on food, and a much higher penalty for sloppy execution. A value chain can survive a mediocre sandwich because the customer paid mediocre money. A premium chain cannot. The entire reason someone drives twenty minutes past three other sandwich shops is that yours is meaningfully better. Break that once and you don't get a second chance with that customer.
Now the "open versus buy" question, which is the actual decision on the table and the one most prospective franchisees skip past. These are two genuinely different businesses wearing the same brand.
Opening new means you sign a franchise agreement, pay the initial franchise fee, select a site, negotiate a lease, build out a deli, buy slicers and cases and refrigeration, hire and train a crew from zero, and then spend six to eighteen months climbing a ramp curve toward whatever your site can actually produce. You control every variable. You also pay for every variable. Your capital goes out the door for the better part of a year before revenue comes in, and your working-capital reserve is what keeps you solvent through the ramp.
Buying an existing unit means you acquire a going concern from a franchisee who wants out. You inherit a customer base, a trained crew, an established bakery relationship, an equipment package of unknown remaining life, a lease with a finite term, and a reason the seller is selling. You typically pay a multiple of the store's earnings rather than a build cost — which means a genuinely good store costs you *more* than building, and a struggling store costs less. That is the whole trade. You are choosing between paying a premium for proof, or paying less for a problem you believe you can fix.
The reason this matters more at PrimoHoagies than at a generic QSR is site quality and brand density. In the core Mid-Atlantic footprint, the good corners are largely taken — by PrimoHoagies units, by competing delis, by whatever else wanted that traffic pattern. If you insist on opening new in a mature territory, the sites available to you are, almost by definition, the sites nobody wanted. Meanwhile, the resale market in that same territory is where the proven locations change hands. The buy path is not the lazy path in a dense market. It is often the only path to a genuinely good address.
Flip the geography and the logic inverts. In an expansion market, there is no resale inventory to speak of, brand awareness is near zero, and you are effectively opening an independent premium deli that happens to pay royalties. That can work — but you should price it as a startup, not as a franchise purchase, and your capital plan needs to fund a much longer ramp than the brochure implies.
One adjacent point worth holding onto: this open-versus-buy framing applies to essentially every service and food franchise, not just this one. The same calculus governs a window-cleaning route, a print-and-ship storefront, a junk-removal territory. Dense mature market with resale inventory → buy the proven unit. Greenfield market with no awareness → build, but fund it like a startup. What changes brand to brand is the *size* of the ramp penalty, and at a premium regional deli that penalty is unusually large because the brand equity, not the food category, is what pulls people in the door.
Working the decision: a sequence that keeps you out of trouble
Most people run this backwards. They fall for the concept, call the franchise development team, and then reverse-engineer a justification. Run it in the order below instead, and let the numbers disqualify the deal before you're emotionally committed.
Phase one — capital honesty (week one). Before you read a single disclosure document, write down two numbers: total investable capital, and liquid cash you can lose without changing how you live. If the second number is under roughly $150,000, stop. Every failure story in this category traces back to a franchisee who was fully invested at open with nothing left for the ramp. The reserve is not a nice-to-have; it is the product.
Phase two — read Item 7 and Item 19 (weeks two to three). Item 7 gives you the estimated initial investment ranges. Item 19 is the financial performance representation — and its *absence* or narrowness tells you as much as its content. Note whether Item 19 reports system-wide averages or only a top-quartile subset, whether it separates core-market units from expansion units, and whether it reports revenue only or revenue and expense. A revenue-only Item 19 is a marketing document. Also read Item 20, the outlet table: openings, closures, transfers, and terminations over the last three years. Transfers are resales. A high transfer count in your target state means resale inventory exists — that's your buy-side deal flow. A high termination count means something is wrong.
Phase three — call franchisees, and call the ones who left (weeks three to five). Item 20 gives you contact information for current franchisees and, critically, former ones. Call fifteen current operators. Then call every former operator you can reach. Ask current owners: what's your actual food cost, what percentage of revenue is catering, how long did the ramp take, what do you pay a skilled slicer, how consistent is your bakery? Ask former owners one question and then shut up: what happened? The answers cluster fast, and the cluster is the truth about the system.
Phase four — run both paths in parallel (weeks five to ten). Do not choose open-versus-buy in the abstract. Get a real site proposal and a real build estimate for the open path, and get financials on every available resale in your territory for the buy path. Then compare them on the same metric: cash-on-cash return in year two, and total cash out before breakeven. Frequently one path is obviously better on those two numbers, and it is not always the one you expected.
Phase five — diligence the specific deal (weeks ten to fourteen). On a resale, this means three years of tax returns and P&Ls, POS data, the lease with all options and escalators, an equipment condition assessment, and franchisor approval of you as a transferee. On a new build, it means a signed LOI, a contractor bid, and a franchisor-approved site study.
Phase six — decide, or walk. The discipline here is that walking is a legitimate outcome. Sunk diligence cost is not a reason to sign.
Costs, timelines, and what the ranges really mean
The initial franchise fee is $35,000. Ongoing royalty runs in the 6%–7% range of gross sales, with a marketing contribution of roughly 2% on top. Call it 8%–9% off the top before you've paid for a single slice of capicola. Total initial investment for a new build lands in the neighborhood of $350,000 to $550,000 depending on whether you're taking a raw shell or a second-generation restaurant space with usable infrastructure.
Where that money goes, in rough proportion:
- Franchise fee — $35,000, paid at signing, not negotiable and not refundable once you're past the disclosure period.
- Leasehold construction and buildout — the single largest line, and the one with the widest spread. A second-generation food space with existing hoods, grease traps, plumbing, and three-phase power can save you well into six figures versus a raw retail shell. This is the difference between the bottom and the top of the range more than any other factor.
- Deli equipment — slicers, refrigerated display cases, walk-in cooler, prep tables, POS. Commercial slicers are the heart of the operation and cheap ones will cost you in downtime and inconsistent portioning.
- Signage, décor, and brand elements — non-optional, spec'd by the franchisor.
- Opening inventory — premium proteins tie up more cash per shelf-foot than commodity cold cuts.
- Grand-opening marketing — front-loaded, and higher in a market where nobody knows the brand.
- Training and travel — you and your key staff, at your expense.
- Working capital — the reserve that funds payroll and rent until the store cash-flows. Budget more than the FDD's low end. Always.
Liquidity requirement: plan on $120,000–$200,000 in genuinely liquid cash, separate from whatever a lender is financing. Franchise brands qualify buyers on liquidity because they've watched undercapitalized operators fail in month nine.
Timeline for a new build: six to twelve months from signed agreement to open door, and the variance is almost entirely site and permitting. Site selection and lease negotiation eat two to four months. Permitting and construction eat three to six, longer in municipalities with slow health and building departments. Training and pre-opening run three to six weeks. Then you ramp — and the ramp is where forecasts break. In a core market with brand recognition, a good site can approach a normal sales level within a couple of quarters. In a market where "hoagie" needs explaining, plan on years, not quarters, and fund accordingly.
Timeline for a resale: dramatically shorter on the operational side — thirty to ninety days from LOI to close is common — but gated by two things you don't control. First, landlord consent to lease assignment. Second, franchisor approval of you as a transferee, which includes your own application, financial qualification, and training. Both can stall a deal. Build both into your LOI as conditions.
On the revenue side, be conservative and be specific. Do not model an average. Model *your* site, using the Item 19 disclosure as a range rather than a target, discounted for the fact that you are a first-time operator and your first year will be worse than a seasoned one's. Then stress-test: what happens at 20% below your projection? If the answer is insolvency, the deal is too tight regardless of how good the concept is.
A note on financing. Franchise concepts with an established operating history are generally financeable through SBA 7(a) loans, and the SBA maintains a franchise directory that lenders reference. Expect to put meaningful equity in, personally guarantee the debt, and pledge collateral. Read the personal guarantee before you read anything else in the loan package. Adjacent point: on a resale, SBA financing of a business acquisition is well-trodden ground and lenders are comfortable underwriting against historical cash flow — which is another quiet argument for the buy path, since a startup build has no history to underwrite against.
Where franchisees get this wrong
They evaluate the brand instead of the site. PrimoHoagies could be an excellent system and your specific corner could still be a bad business. Daypart traffic, lunch density, parking, visibility from the road, co-tenancy — these determine outcomes more than the logo does. A great brand at a mediocre address loses to a mediocre brand at a great address, every time.
They plan to be absentee owners. This is the most expensive mistake in the category. A hand-slicing deli is not a heat-and-serve operation with a job aid taped to the wall. Portion control, slice thickness, roll handling, and product rotation are judgment calls made hundreds of times a day by hourly employees. The owner-operators who work the line catch drift the same week it starts. The absentee owners find out from a review. If you are hiring a general manager to run the store, add that salary and benefits load to your overhead before you compute your return — and understand that you are converting a job-plus-return into a return-only investment with a materially thinner margin.
They underestimate labor. Turnover in quick-service restaurants runs brutally high across the industry, and a concept requiring a skilled slicer feels it worse than one requiring a button-pusher. A new hire takes weeks, not days, to reach competence on a slicer. Every departure costs you productivity, quality, and ticket time during the relearning window. The fix is not clever recruiting; it's paying above the local market for the two or three people who actually matter and building a bench before you need one. Pay them like the constraint they are.
They ignore catering. Premium hoagie trays are a genuine second revenue channel for this concept, and it behaves nothing like the retail counter. Catering is relationship sales: offices, contractors, schools, funeral homes, sports leagues. It's forecastable, higher-ticket, and it flattens your labor curve because you prep it off-peak. Operators who treat it as an afterthought leave real money on the table. Operators who assign someone to actively work it build a book of recurring accounts that competitors can't easily poach. If you have any background in outbound sales, this is where that skill compounds — treat it like a pipeline, with a list, a cadence, and a close rate you actually track.
They assume the supply chain travels. The roll is the product. It is baked to a specific spec, it is not a generic foodservice item, and its availability and quality vary by geography. In the dense core, fresh delivery is routine. Further out, you may be dealing with frozen shipment or a local bakery that has to be trained onto the spec. Ask the franchise team directly what your bakery source will be, how far it ships, and what the contingency is if that bakery fails an audit or closes. Ask existing franchisees in your target region how consistent their rolls are. Hesitation in that answer is data.
They misprice a resale. Buyers look at the asking price and compare it to build cost. Wrong comparison. Compare it to the earnings you're buying. Then verify those earnings — tax returns over seller-prepared spreadsheets, POS exports over summary P&Ls. Add back only genuinely discretionary owner expenses, not "adjustments" that quietly assume you'll run a leaner store than the seller could. And find out why they're selling. Retirement and relocation are fine. A lease expiring in eighteen months with no renewal option, a road-widening project, or an anchor tenant leaving the center are not — and none of those will appear in the financials.
They skip the former franchisees. Current operators are, to some degree, invested in the system looking good. Former operators have nothing to protect. The FDD gives you their contact information for exactly this reason. Use it.
They confuse premium with expensive. Premium means the customer perceives more value than they paid. If you cut portion to protect food cost, you haven't protected margin — you've dismantled the reason the business exists. The correct levers are waste control, yield management on the slicer, mix shift toward higher-margin items, catering volume, and disciplined purchasing. Not shrinking the sandwich.
A framework for choosing your path
Here is the decision compressed into rules you can actually apply.
Buy an existing unit when: you're in the dense Mid-Atlantic core; a profitable store is genuinely available; the lease has five-plus years of term or firm options; the equipment has real remaining life; the seller's reason for exiting is personal rather than structural; and the asking price implies a cash-on-cash return in year one that beats what you'd model in year three of a new build. Verify the earnings independently. Then verify them again.
Open new when: you have a demonstrably superior site that isn't available any other way; the territory has no resale inventory; you're capitalized to fund a long ramp without stress; and you personally intend to operate. New builds reward operators who want the store shaped exactly to their standard from day one — and punish anyone treating it as passive income.
Walk away when: your liquid reserve is thin; you plan to hire out the operating role entirely; you're far outside the brand's recognized footprint without a specific, funded plan to build awareness; or the resale you're looking at is cheap for a reason you can't name. Cheap deals in this category are cheap because someone already tried and failed at that address.
Consider an adjacent path when: the numbers don't clear but the category still appeals. Other sub and sandwich franchises carry lower buildout costs and simpler operations, at the price of thinner differentiation and lower ticket. An independent Italian deli gives you complete control and zero royalty — and requires you to build brand, recipes, and supply chain yourself, which is precisely the work the franchise fee buys. Non-food service franchises in shipping, cleaning, or home services generally require less capital and no perishable inventory, though they trade the deli's walk-in traffic for outbound sales effort. None of these are better in the abstract. They're different distributions of risk, capital, and personal time, and the right one depends on which of those three you have most of.
The meta-rule: the deal has to work on the numbers you can verify, not the numbers you're shown. Everything else is decoration.
Related questions
Is buying an existing franchise always cheaper than opening new?
No. A profitable existing unit usually costs *more* than building, because you're paying a multiple of proven earnings rather than construction cost. Cheaper resales are typically underperforming. You're choosing between paying for certainty or paying less for a turnaround.
Do I need restaurant experience to be approved?
Not strictly, but it helps materially — both in approval odds and in survival. Franchisors train you on their system; they don't train you on managing food cost, scheduling labor, or handling a lunch rush. Operators without that background face a steeper and more expensive first year.
How much does the franchisor's approval matter on a resale?
Completely. A transfer requires franchisor consent, and you must qualify as a new franchisee would — application, financials, and training. A seller cannot hand you the store privately. Build franchisor approval into your LOI as a closing condition.
What's the single biggest predictor of failure here?
Insufficient working capital at open. Undercapitalized operators run out of runway during the ramp, cut the things that make the concept work, and enter a spiral. Everything else — site, labor, supply chain — is survivable if you have cash.
Should I plan for one unit or several?
Model one unit standing alone. Multi-unit economics only improve once you can share management, delivery routes, and catering infrastructure across nearby stores. If unit one doesn't work by itself, three won't fix it.
FAQ
What does it cost to open a PrimoHoagies franchise?
The initial franchise fee is $35,000, and total initial investment for a new location runs roughly $350,000 to $550,000 depending heavily on your real estate. Taking over a second-generation restaurant space with existing kitchen infrastructure lands you near the bottom of that range; building out a raw retail shell pushes you toward the top. Ongoing royalty runs 6%–7% of gross sales with roughly 2% more for marketing.
How much liquid cash do I need on hand?
Plan on $120,000 to $200,000 in liquid capital beyond any financing. Franchisors and SBA lenders both screen on liquidity because undercapitalized operators are the ones who fail during the ramp period. Treat any reserve below that as a signal to wait rather than a hurdle to argue around.
How long from signing to opening?
Six to twelve months for a new build, with site selection and permitting driving almost all of the variance. A resale closes far faster — often thirty to ninety days — but requires both landlord consent to the lease assignment and franchisor approval of you as a transferee, either of which can extend the timeline.
Where do I find the real financial numbers?
Item 19 of the Franchise Disclosure Document, read alongside Item 7 for costs and Item 20 for the outlet table showing openings, closures, and transfers. Then validate all of it by calling current franchisees and, more importantly, former ones — the FDD provides contact information for both.
Does location within the brand's footprint really change the math?
Substantially. In the Philadelphia and South Jersey core, brand recognition does the customer-acquisition work for you. Outside the established footprint, you're funding brand education out of your own marketing budget on top of the system marketing fee, and your ramp to a stable sales level is measured in years rather than quarters.
Can I run this as a passive investment with a hired manager?
You can, but the economics change and not in your favor. Add a full management salary to overhead, then recognize that a hand-slicing premium deli depends on daily judgment calls about portion, quality, and freshness that an owner catches and a hired manager often doesn't. This concept rewards owner-operators.
Sources
- https://www.ftc.gov/business-guidance/resources/franchise-rule-compliance-guide — FTC Franchise Rule compliance guide, covering FDD disclosure obligations including Items 7, 19, and 20.
- https://www.sba.gov/funding-programs/loans/7a-loans — SBA 7(a) loan program terms, eligibility, and use for franchise acquisition and buildout.
- https://www.sba.gov/document/support-sba-franchise-directory — SBA Franchise Directory, used by lenders to confirm a brand's eligibility for SBA-backed financing.
- https://www.franchise.org/ — International Franchise Association, franchising standards, research, and franchisee education resources.
- https://www.franchisebusinessreview.com/ — independent franchisee satisfaction survey data across brands and categories.
- https://www.entrepreneur.com/franchises — franchise rankings, category comparisons, and investment cost overviews.
- https://www.bls.gov/oes/current/oes352021.htm — Bureau of Labor Statistics wage data for food preparation workers, useful for modeling labor cost by metro.
- https://www.restaurant.org/research-and-media/research/ — National Restaurant Association industry research on operating costs, labor, and consumer trends.
- https://www.primohoagies.com/franchise — the brand's own franchise development site for current territory availability and FDD requests.
Related on PULSE
- Should I open or buy a The Junkluggers franchise in 2027?
- Should I open or buy a Pak Mail franchise in 2027?
- Should I open or buy a PostNet franchise in 2027?
- Should I open or buy a Fish Window Cleaning franchise in 2027?
- Should I open or buy a Shine Window Care franchise in 2027?
- Should I open or buy an Image360 franchise in 2027?
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-qHow Many Employees Should I Schedule Each Shift at My Escape Room in 2026?
 pulse-qShould I open or buy a Nekter Juice Bar franchise in 2027?
 pulse-qShould I Hire a Fractional CRO If I Need a 30-60-90 Plan Before a Board Meeting in 2026?
 pulse-qShould I open or buy a Sub Zero Nitrogen Ice Cream franchise in 2027?
 pulse-qHow Many Sales Reps Do I Need to Hire for My Solar Company to Hit Its Install Goal in 2026?
 pulse-qHow Many Employees Should I Schedule Each Shift at My Roller Rink in 2026?
 pulse-qShould I open or buy a Frenchies Modern Nail Care franchise in 2027?
 pulse-qWhat Service Fees Should a Real Estate Brokerage Charge in 2027?
 pulse-qHow Do I Get My Optical Staff to Sell Premium Lenses and Coatings in 2026?
 pulse-qHow Many Employees Should I Schedule Each Shift at My Ice Cream Shop in 2027?