
“Revenue in regulated markets.” — LinkedIn Banner
 Curated byKory White · Fractional CRO · Maryland
 PULSEKNOWLEDGE LIBRARY
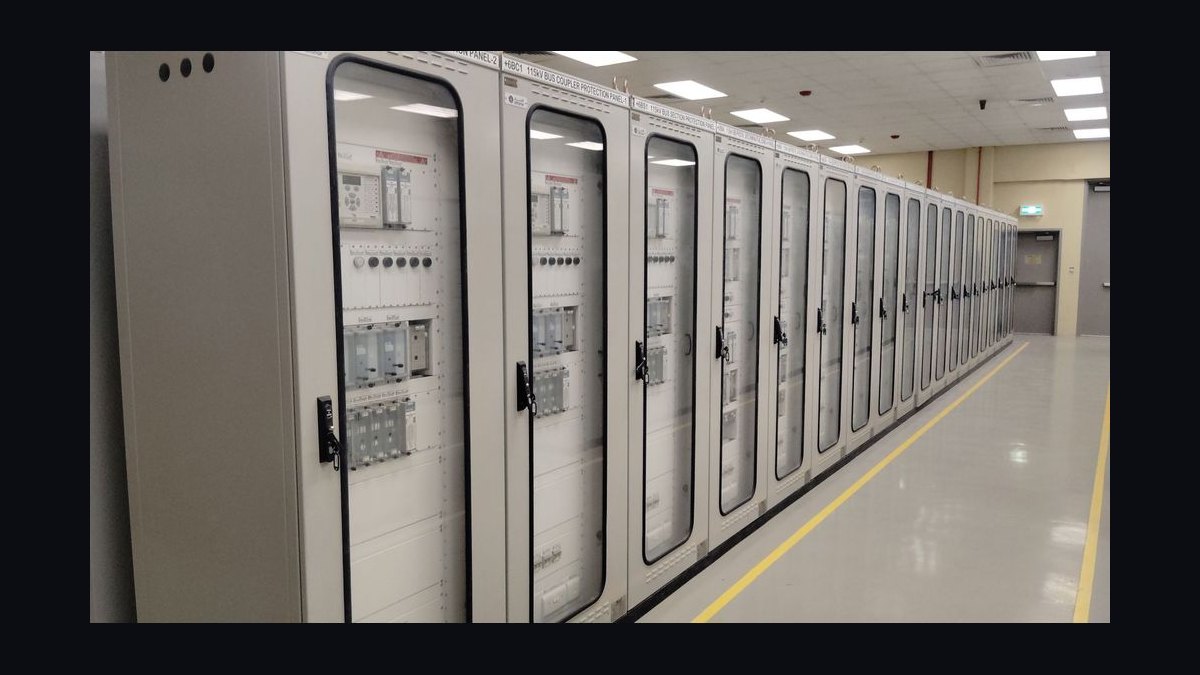
Revenue in regulated markets is income earned inside industries where a government body governs pricing, licensing, or market entry — utilities, healthcare, telecom, and finance are the classic cases. Rates and contracts are often pre-approved, making this revenue more predictable than open-market sales, but it is capped, slowed by review cycles, and carries compliance costs that quietly shrink net margin.
What the phrase captures and why it's on a banner
"Revenue in regulated markets" is doing two jobs at once. On one level it's a factual description: a sales motion where a regulator has real influence over what you can charge, who you can sell to, and how quickly a deal can close. Utilities file rate cases with state commissions before they can raise a customer's bill. Healthcare vendors sell into reimbursement schedules set by Medicare and Medicaid rather than negotiating list price directly with the buyer. Telecom carriers operate under universal service obligations and wholesale access pricing rules. Financial services firms price products under usury caps, mandatory disclosures, and capital adequacy rules that cap how aggressively they can compete on price. In each of these, the top-line figure on a revenue report is the output of a negotiation with a regulator as much as it is the output of a negotiation with a customer.
On a second level, the phrase is a credential. Someone who puts "Revenue in regulated markets" on a LinkedIn banner is signaling that they've already absorbed everything a normal SaaS motion doesn't have to deal with — legal review as a standing pipeline stage rather than an occasional detour, security questionnaires as a recurring tax on deal velocity, and procurement committees that include a compliance officer sitting next to the economic buyer. It's shorthand for "I don't get blindsided by a 90-day legal review," which matters because plenty of experienced revenue operators do get blindsided by exactly that, usually right after they've already forecast the deal into this quarter's number.
The operational weight behind the phrase comes down to three structural differences from unregulated selling. First, regulated revenue compresses your addressable pricing range. Rate-of-return, price-cap, and revenue-cap regimes each impose a ceiling — and sometimes a floor — on what you can charge, so growth has to come from volume, operating efficiency, or adjacent unregulated services rather than from raising prices whenever demand allows it. Second, it stretches the sales cycle by inserting checkpoints that no amount of rep skill can shortcut: security review, legal redlining, and multi-stakeholder sign-off are structural, not negotiable. Third, it changes what "revenue" means on the books. Deferred revenue, regulatory assets, and pending rate cases mean the number reported this quarter may not match the cash or margin eventually realized — a rate increase can be approved on paper months before it ever appears on a customer invoice.
The step-by-step process
Winning and recognizing revenue in a regulated market follows a fairly consistent sequence whether the buyer is a hospital system, a utility commission, or a bank's procurement desk. Each stage below can independently stall a deal that would have closed in weeks in an unregulated market, which is exactly why mapping the sequence matters more here than it does in a typical B2B motion.
The process opens with compliance qualification: confirming the product already meets the baseline certifications the vertical requires — HIPAA and SOC 2 in healthcare, PCI-DSS anywhere payment data touches the product, or a relevant state filing for energy services. Deals that skip this step don't die quietly; they die later, in security review, after real selling hours have already been spent. Next is stakeholder mapping — identifying not just the economic buyer but the compliance champion, the data protection officer, and the vendor risk committee that will eventually gate the deal. Regulated deals commonly touch eight to twelve stakeholders, roughly double the four to six typical of an unregulated enterprise sale. From there the deal enters security and risk review, where 200 to 500 discrete security questions on a single enterprise deal is routine, consuming real selling time unless a dedicated security-response process is already built. Legal redlining follows, adding two to four weeks per negotiation round, because regulated contracts commonly run 20 to 50 pages covering data residency, breach notification timelines, and audit rights that a standard 5-to-10-page SaaS agreement never touches. Only after those gates clear does the deal reach regulatory or rate approval — for utilities and similarly regulated sellers, revenue itself can be contingent on a commission approving a rate case, a step that can delay recognition by six to eighteen months from filing. The cycle closes with revenue recognition and reporting, where deferred revenue, regulatory assets, and disclosure requirements under standards like ASC 980 determine when and how the deal actually lands on the income statement — and where it sits relative to the cash that eventually shows up in the bank.
This same sequence shows up, with the labels swapped, in adjacent regulated categories that rarely get grouped with utilities and healthcare — government contracting (where a procurement cycle replaces the rate case), insurance (where state insurance commissioners approve rate filings the same way utility commissions do), and cross-border payments (where each jurisdiction's licensing regime effectively runs its own version of stage one). A revenue leader who has run this sequence once in any regulated vertical usually recognizes the shape of it immediately in a new one, even when the specific regulator and paperwork are unfamiliar — which is part of why "regulated markets" experience transfers across industries better than raw quota history does.
Costs, timelines, and typical ranges
Because regulated revenue is shaped by fixed rules rather than open pricing, its costs and timelines are more knowable than in unregulated markets — but only if the right ranges are being tracked in the first place. On pricing structure: cost-plus regulation, common in utilities, guarantees recovery of operating costs plus a return on capital typically in the 5 to 10 percent range, producing stable but modest margins that don't move much year to year. Price-cap regulation, more common in telecom and energy, ties allowed price increases to inflation minus a built-in productivity factor, meaning an efficient operator can push realized margins to 10 to 20 percent by beating that efficiency target rather than by raising prices. Revenue-cap regulation, typical in transmission and transportation, limits total revenue rather than per-unit price, so growth has to come from regulator-approved capital investment rather than from selling more volume at the same rate.
Timelines follow an equally predictable but slow rhythm. Utility rate cases are typically filed every two to five years and can delay revenue recognition by six to eighteen months between filing and implementation. On the sales-cycle side, regulated deals routinely run 30 to 50 percent longer than comparable unregulated deals, with security and legal review together accounting for roughly 30 to 40 percent of that added time. Analysts evaluating regulated operators tend to watch allowed return on equity — commonly 8 to 12 percent for U.S. utilities — rather than raw revenue growth, because growth in a capped market says less about commercial performance than efficiency against the allowed return does. The same logic extends to how boards and investors read a regulated company's earnings calls: a utility beating its allowed ROE by operating leaner is a stronger signal than one showing double-digit revenue growth, which in a capped market can just mean rate-base expansion rather than commercial execution.
The overhead is real and worth pricing in explicitly rather than absorbing as a surprise later. Compliance-related costs — legal review hours, security audit fees, errors-and-omissions insurance premiums — commonly add 10 to 15 percent to deal economics in regulated verticals. Revenue teams that don't model this overhead into deal pricing are effectively underpricing risk, and it doesn't show up as a line item anyone flagged in advance; it shows up later as margin compression that finance has to explain after the fact. On the operating side, teams frequently report spending 20 to 40 percent of their time on documentation and audit trails rather than direct selling or account growth — a cost that needs to be staffed for deliberately, the same way a company staffs for customer support, rather than treated as friction to be eliminated.
Where teams get it wrong
The most common failure is treating a regulated deal like an unregulated one with extra paperwork stapled on. A rep who evaluates pipeline health the way they would at a general SaaS company will consistently misforecast regulated deals, because the bottleneck isn't the economic buyer's enthusiasm — it's whether a security officer, a data protection officer, or a rate commission has cleared the deal. Hiring managers make the parallel mistake: crediting a candidate's quota attainment at an unregulated company as evidence they can run a regulated motion, when the actual predictor is whether they've navigated a rate case, a HIPAA audit, or a multi-round redlining cycle against a Fortune 500 legal department.
A second recurring error is underinvesting in the infrastructure that makes compliance friction survivable. Without a dedicated security-response process, a team answering 200 to 500 questions per deal by hand loses 10 to 20 hours of selling time to paperwork alone, deal after deal, and the aggregate cost never shows up as a single line item because it's spread across every rep on the team. The same is true of contract lifecycle management: companies that build pre-approved templates and legal playbooks report cutting redlining friction by 40 to 60 percent, but most only invest in that infrastructure after losing several deals to a faster-moving competitor, rather than building it in before the losses start.
A third mistake is static thinking about the regulatory environment itself. Regulated revenue isn't a fixed target — data-privacy rules evolve, reimbursement schedules get revised, and new state-level regimes appear with real frequency. Teams that build their pitch and product posture around today's compliance requirement, rather than anticipating the next revision, end up rebuilding reactively instead of proactively. The same shortsightedness shows up in market-expansion decisions: entering a new regulated vertical — moving from healthcare into fintech, for example — typically takes 12 to 18 months of regulatory scoping and partner-ecosystem work, and teams that treat it like a normal expansion sprint consistently blow through that timeline because they never budgeted for the scoping phase at all.
Finally, teams underweight relationship capital with the compliance ecosystem itself. The operators who move fastest in regulated markets already have relationships with compliance consultants, specialized law firms, and industry associations that shorten the cold-start problem with a new account's risk committee. Teams that rely solely on their economic-buyer relationship and ignore this network consistently find their deals stalling in exactly the review stage their competitors have already learned to pre-clear — and they often misdiagnose the stall as a pricing or product objection rather than what it actually is, an unmanaged compliance relationship.
Decision framework: when to choose what
Not every decision inside a regulated market is the same, and the right move depends on where a company sits and which lever it's pulling. Three decisions recur often enough to warrant a simple framework: whether to prioritize efficiency gains under a price-cap regime versus diversifying into unregulated adjacent services, whether to enter a new regulated vertical or expand deeper into an existing one, and whether a revenue-leader candidate is actually ready to run a regulated motion versus better suited to an unregulated one.
On the growth-lever question, a company operating under cost-plus regulation with margins pinned near the 5 to 10 percent range gets more leverage from diversification — consulting services, adjacent unregulated offerings, ancillary data products — than from squeezing further efficiency out of an already-capped return. A company under price-cap regulation, by contrast, gets direct margin upside from efficiency investment, since it keeps the spread between actual costs and the capped price it's allowed to charge. On the expansion question, deepening share in an existing regulated vertical is the faster, lower-risk path when the regulatory relationships and compliance infrastructure already exist; entering a genuinely new vertical only pays off within a reasonable timeframe when the company is willing to commit the 12 to 18 months of regulatory scoping that real new-vertical entry requires — trying to compress that timeline is one of the more common ways a promising expansion turns into a stalled one. On the hiring question, a candidate's fit for regulated revenue is best tested by asking how they've navigated a gatekeeper, modeled compliance overhead into deal economics, or restructured a contract around a data-localization requirement — not by their raw quota history, which measures a different skill entirely.
Related questions
How long does a typical regulated-market sales cycle take compared to an unregulated one?
Regulated deals commonly run 30 to 50 percent longer than unregulated deals, with security review and legal redlining accounting for most of the added time before signature.
What does "allowed return on equity" mean for a regulated utility?
It's the return regulators permit a utility to earn on invested capital, commonly 8 to 12 percent in the U.S. — analysts track it instead of raw revenue growth to judge performance.
Why does revenue recognition lag behind an approved rate increase?
A commission can approve a rate case months before the new rate is implemented in customer billing, so the revenue is deferred and accrued rather than recognized immediately.
What's the fastest way to reduce security-questionnaire drag on regulated deals?
Building a dedicated security-response process and maintaining pre-answered questionnaire templates cuts the 10 to 20 hours per deal reps otherwise lose to manual compliance paperwork.
Is it possible to sell into both regulated and unregulated markets with one team?
Yes, but it typically requires separate compliance workflows and playbooks — most companies master one market type first, then build a distinct regulatory function before expanding into the other.
FAQ
What does "revenue in regulated markets" actually mean? It refers to generating sales while complying with industry-specific rules — common in healthcare, finance, energy, and telecom. Revenue in these sectors typically requires licensing, ongoing reporting, and adherence to pricing or data-privacy rules set by a government body rather than by the open market.
Why would someone put this phrase on a LinkedIn banner? It functions as a filter. A "Revenue in regulated markets" banner signals to investors, recruiters, and partners that the person understands long sales cycles, legal review, and compliance-driven procurement — and it distinguishes them from operators built only for fast, unregulated closes.
How do revenue operations differ in regulated versus unregulated markets? In regulated markets, every deal passes through compliance checks, contracts run longer, and sales cycles stretch 30 to 50 percent further. Unregulated markets allow faster pricing and channel experimentation, but regulated markets typically deliver more predictable, recurring revenue once a deal closes.
What are the biggest challenges for revenue teams in regulated industries? The main hurdles are complex legal approvals, slower onboarding, and restricted marketing claims. Teams commonly spend 20 to 40 percent of their time on documentation and audit trails rather than direct selling.
What skills matter most for a revenue leader in a regulated market? Deep regulatory knowledge, tight cross-functional collaboration with legal and compliance, and the discipline to build scalable, repeatable processes. Patience and risk management outweigh raw quota-closing speed in these environments.
How does pricing strategy change under regulation? Pricing is constrained by rate caps, reimbursement schedules, or transparency rules. Instead of dynamic pricing, teams typically use tiered or value-based models that require pre-approval from a regulator or auditor before they can go to market.
Sources
- International Monetary Fund — imf.org
- World Bank — worldbank.org
- U.S. Securities and Exchange Commission — sec.gov
- European Securities and Markets Authority — esma.europa.eu
- McKinsey & Company — mckinsey.com
- Bloomberg — bloomberg.com
- Federal Energy Regulatory Commission — ferc.gov
- Centers for Medicare & Medicaid Services — cms.gov
Related on PULSE
- Revenue by Channel Pie
- NRR Beats New Logos — Revenue Law Banner
- Revenue Operations — Mission Banner
- Revenue Gauge (KPI) — Icon / Clip Art
- Activity to Revenue — Motivational Print
- "Revenue Is a Lagging Indicator of Trust" — Quote Card
Read it free — or make it yours for $1.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
 graphic“Slow is smooth. Smooth is fast.” — LinkedIn Banner
 graphic“We’re hiring closers.” — LinkedIn Banner
 graphicIndustrial Robotics CRO — LinkedIn Banner
 graphicBusiness Development — LinkedIn Banner
 graphicMotion creates momentum. — LinkedIn Wallpaper
 graphic“Calm closers win.” — LinkedIn Banner
 graphic“The next call is the most important one.” — LinkedIn Banner
 graphicFaster deals, fewer leaks. — LinkedIn Wallpaper
 graphicMarketing Operations — LinkedIn Banner
 graphicBuild the revenue engine. — LinkedIn Wallpaper