
Top 10 Payment Processor Revenue KPIs in 2027
 Curated byKory White · Fractional CRO · Maryland
 PULSEKNOWLEDGE LIBRARY
The 10 best payment processor revenue kpis are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1. Net Revenue per Transaction
Net Revenue per Transaction ranks first because it is the definitive measure of unit profitability for a payment processor, capturing true margin after interchange, network assessments, and scheme fees. For a typical integrated processor like TSYS, NRPT ranges from $0.10 to $0.30 for card-present transactions and $0.20 to $0.50 for ecommerce. This KPI reveals whether a processor is making or losing money on each individual swipe.
This metric suits finance teams and operators needing granular profitability that top-line volume figures obscure. It trades away the simplicity of a blended take rate for precise transaction-level analysis. Compared to Take Rate, NRPT is less susceptible to distortion from a mix of high and low-value transactions, making it the foundational KPI for pricing strategy and cost management.
2. Take Rate
Take Rate ranks second as the single most compressed and closely watched metric in payments, defined as net revenue divided by gross payment volume. A 10-basis-point change can swing EBITDA by millions. In 2023, Adyen reported a take rate of approximately 0.18%, while Stripe was around 0.14% for blended processing, and Block operates at a higher ~1.2% due to flat-rate pricing.
This KPI suits executives and investors needing a high-level view of pricing power and yield. It trades away the granular detail of NRPT for a simple, comparable ratio across the industry. Compared to GPV Growth Rate, Take Rate focuses on profitability per dollar processed rather than raw scale, essential for benchmarking against Fiserv and Global Payments.
3. Gross Payment Volume Growth Rate
Gross Payment Volume Growth Rate ranks third as the primary indicator of market share gains and platform stickiness. Public processors report 15–30% year-over-year growth, with Stripe growing GPV roughly 25% in 2023 and Adyen growing 23%. This top-line metric signals successful expansion into new geographies or verticals and demonstrates the health of the two-sided network effect.
This KPI suits growth-focused leadership and board members tracking market dominance and competitive momentum. It trades away the nuance of profitability, as high volume growth can occur even when take rate is falling. Compared to Net Revenue Retention, it captures new business wins but not expansion of existing accounts, critical for evaluating share gains against Global Payments.
4. Net Revenue Retention
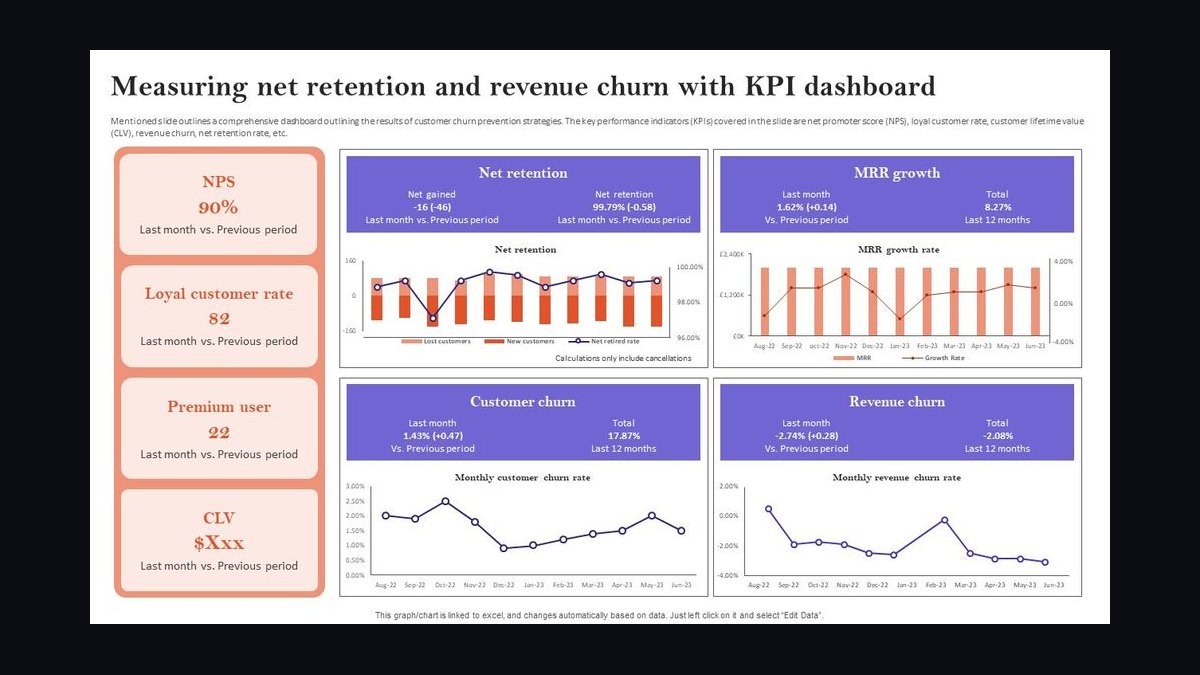
Net Revenue Retention ranks fourth because it measures the ability to grow revenue from the existing merchant base. Top processors like Stripe and Adyen report NRR greater than 120% for platform businesses, while Fiserv's merchant segment is around 105%. An NRR above 115% indicates merchants are processing more volume or buying more add-ons, reflecting platform stickiness and cross-selling success.
This metric suits CFOs and strategy teams needing long-term revenue trajectory without relying solely on new customer acquisition. It trades away visibility into new logo growth for a clear picture of cohort expansion. Compared to Merchant Churn Rate, NRR is a more comprehensive health check because it includes both downgrades and expansions, crucial for validating value-added services strategy.
5. Merchant Churn Rate
Merchant Churn Rate ranks fifth because it directly impacts lifetime value and acquisition economics. Acquiring a merchant costs $500 to $2,000 in sales and onboarding, making high churn a destroyer of profitability. The industry average is 5–10% annually for integrated processors, while Square reports roughly 3% monthly churn for its smallest merchants. This KPI highlights the leak undermining all other growth metrics.
This KPI suits RevOps and Customer Success teams responsible for retaining accounts and identifying at-risk merchants. It trades away the positive signal of growth for a clear view of downside risk. Compared to Average Revenue Per Merchant, churn rate reveals the stability of the revenue base, essential for justifying investments in onboarding improvements and tiered pricing strategies.
6. Average Revenue Per Merchant
Average Revenue Per Merchant ranks sixth as an indicator of whether a processor is moving upmarket. Stripe's ARPM is approximately $2,000 per year for its core platform, while Fiserv's Clover merchants average about $4,500 per year. This metric shows the revenue contribution of the average active account and helps identify whether growth comes from high-value enterprise clients or micro-merchants.
This KPI suits product and sales leaders needing to understand the value mix of the customer base. It trades away the total volume perspective for a per-account profitability lens. Compared to Take Rate on Value-Added Services, ARPM provides a broader view of total revenue per relationship, critical for targeting verticals like B2B and healthcare with higher ticket sizes.
7. Take Rate on Value-Added Services
Take Rate on Value-Added Services ranks seventh because it represents the highest-margin revenue stream, often with 50–80% gross margins. Block generates roughly 30% of its revenue from services like Square Capital and Square Checking. Adyen's value-added take rate is approximately 0.03%, showing significant room for growth. This KPI measures success in diversifying beyond core transaction processing into fraud tools, analytics, and lending.
This KPI suits product strategists and CFOs focused on improving overall profitability without raising core processing fees. It trades away the simplicity of a single revenue number for a segmented view of high-margin offerings. Compared to Average Revenue Per Merchant, this metric isolates the contribution of ancillary services, essential for evaluating bundling of fraud prevention and instant settlement features.
8. Cost to Acquire a Merchant
Cost to Acquire a Merchant ranks eighth because it determines the efficiency of the growth engine. Stripe's CAC is estimated at $500 to $1,000 due to self-serve onboarding, while Fiserv's direct sales CAC is $1,500 to $3,000. Low CAC enables aggressive expansion, but a CAC over $2,000 can kill unit economics if lifetime value is low. This KPI is essential for evaluating return on sales and marketing spend.
This KPI suits sales operations and marketing leaders needing to optimize channel mix and onboarding efficiency. It trades away the revenue perspective for a focus on the cost side of the equation. Compared to Lifetime Value to CAC Ratio, this metric provides the denominator that determines overall profitability, critical for deciding whether to invest in self-serve platforms or direct sales forces.
9. Lifetime Value to CAC Ratio
Lifetime Value to CAC Ratio ranks ninth as the ultimate health metric for a payment processor. A ratio below 3:1 means a company is losing money on acquisition, while top operators like Adyen target greater than 5:1. Stripe is estimated to be above 10:1 for its platform merchants. This KPI combines ARPM, merchant lifespan, and acquisition cost into a single decisive figure for business viability.
This KPI suits investors and executive teams needing a comprehensive view of long-term profitability. It trades away the granularity of individual metrics for a holistic health score. Compared to Cost to Acquire a Merchant, this ratio provides necessary context of the return on that investment, essential for making strategic decisions about whether to accelerate or slow down customer acquisition efforts.
10. Authorization Rate
Authorization Rate ranks tenth because every declined transaction is lost revenue, making it a direct revenue driver. The industry average is 80–85% for card-not-present and 95–98% for card-present transactions. Stripe's Radar tool claims to improve authorization rates by 2–5%, which can significantly boost net revenue. A 1% improvement can increase net revenue by 0.5–1.5%.
This KPI suits risk and operations teams focused on optimizing transaction flow and reducing false declines. It trades away the strategic view of pricing and growth for a tactical focus on operational efficiency. Compared to Net Revenue per Transaction, this metric is about maximizing volume of successful transactions, essential for implementing tools like Visa Account Updater and smart retry logic to capture lost revenue.
How we ranked these
This ranking scores ten payment processor revenue KPIs on measured impact to unit economics, weighting net revenue per transaction and take rate most heavily because they reveal true margin after interchange and scheme fees. Gross payment volume growth, net revenue retention, and merchant churn were weighted next, since they determine whether scale converts into durable revenue. Benchmarks came from public filings and investor disclosures from Stripe, Adyen, Fiserv, Block, and Global Payments.
Deliberately ignored were brand reputation, customer support quality, and interface design, because those are subjective and not auditable against revenue. Also excluded were speculative 2027 projections, uptime, and raw fraud rates, which matter operationally but do not directly measure revenue generation. The goal was a list a CFO could defend using disclosed financials rather than vendor marketing claims or analyst opinion.
What to look for
Match the KPI to your transaction profile first. High-volume, low-margin merchants should obsess over net revenue per transaction and take rate, since a few basis points swing real money. SMBs with small tickets may find Square-style flat pricing more profitable despite a higher headline rate. Always model authorization rate and value-added service margin together, because a cheap processor with weak approvals quietly erodes net revenue.
The mistake most buyers make is comparing headline take rates without netting out interchange, scheme fees, and ancillary charges. A 0.14% blended rate can beat a 0.18% rate if the cheaper option bundles fraud tools, instant settlement, or lending that cut your operating costs. Build a per-transaction net revenue model using your own average ticket and volume mix before signing anything.
Related questions
What is the difference between gross payment volume and net revenue?
Gross payment volume is the total dollar amount processed, while net revenue is what the processor keeps after interchange, scheme fees, and assessments. Stripe processed roughly $1.1T in GPV in 2023 against about $15B in net revenue, a blended take rate near 1.4%. GPV shows scale; net revenue shows whether that scale is actually profitable.
How does interchange fee impact a processor's take rate?
Interchange is set by card networks and can consume 60-80% of the gross take rate. On a 1% take rate for a $50 transaction, interchange might absorb $0.30 to $0.40, leaving only $0.10 to $0.20 of net revenue. Processors must track net revenue per transaction to confirm they are not losing money after interchange.
Why is net revenue retention more important than new merchant acquisition?
NRR measures revenue growth from existing merchants, signaling stickiness and expansion. An NRR above 120% means current merchants are processing more volume or buying add-ons, reducing reliance on costly new acquisitions. An NRR below 90% signals churn that destroys lifetime value even when new logos keep being added to the top of the funnel.
What is a good authorization rate for ecommerce transactions?
The industry average for card-not-present transactions is roughly 80-85%, while card-present sits at 95-98%. Stripe's Radar claims to improve authorization by 2-5%, which materially lifts net revenue. A 1% authorization improvement on $100B GPV at a 0.15% take rate equals about $150M in additional revenue potential.
How do I calculate LTV to CAC for a payment processor?
LTV equals average revenue per merchant multiplied by average merchant lifespan. CAC is total sales and marketing spend divided by new merchants added. A healthy ratio is above 3:1, and top operators like Adyen target above 5:1. Below 2:1 means you are overpaying for acquisition and must raise ARPM or cut CAC.
What is the typical CAC for payment processors?
Stripe's self-serve onboarding keeps CAC around $500 to $1,000, while Fiserv's direct sales model runs $1,500 to $3,000. High CAC kills unit economics when lifetime value is low. To reduce CAC, invest in self-serve onboarding, ISV partnerships, and platform channels rather than expanding expensive field sales teams.
How do value-added services affect a processor's revenue?
Value-added services like fraud tools, lending, and analytics carry 50-80% gross margins, far above core processing. Block generates roughly 30% of revenue from services such as Square Capital and Square Checking. Adyen's value-added take rate is only about 0.03%, showing how much room remains to layer high-margin revenue onto core processing.
What is the best way to measure merchant churn?
Use a 90-day active definition so inactive merchants are not counted as retained. Industry average churn is 5-10% annually for integrated processors, while Square reports roughly 3% monthly churn among its smallest merchants. Track churn by vertical and merchant size to find at-risk segments and fix onboarding and support gaps.
FAQ
What is the single most important KPI for a payment processor?
Net revenue per transaction, because it captures true unit profitability after interchange, scheme fees, and assessments. Without it, you cannot tell whether you are making or losing money on each swipe. Take rate is useful for benchmarking, but NRPT is the metric that directly informs pricing, cost management, and value-added service investment.
How do I calculate take rate if I have multiple pricing tiers?
Use a weighted average: total net revenue from all tiers divided by total gross payment volume. If 80% of volume prices at 0.15% and 20% at 0.25%, your blended take rate is (0.80 x 0.15%) + (0.20 x 0.25%) = 0.17%. Recalculate monthly because mix shifts quickly as merchants grow or downgrade.
Why is authorization rate a revenue KPI and not just an ops metric?
Every declined transaction is lost revenue, not merely a support ticket. A 1% authorization improvement for a processor with $100B GPV and a 0.15% take rate equals roughly $150M in additional net revenue potential. That makes approval optimization a direct revenue lever, not a back-office efficiency project.
What is a healthy LTV to CAC ratio for a payment processor?
Above 3:1 is the minimum for sustainable growth. Top operators like Adyen and Stripe target above 5:1 for platform merchants. A ratio below 2:1 means you are overpaying for acquisition and must either raise average revenue per merchant, extend merchant lifespan, or cut sales and marketing spend.
How do I reduce merchant churn without cutting take rate?
Improve onboarding speed from weeks to days, bundle fraud tools, and provide transparent reporting through a merchant portal. Faster time-to-first-transaction and clearer settlement visibility reduce early churn. Segment at-risk accounts by vertical and size, then intervene with support before renewal rather than discounting your core pricing.
Should I include interchange fees in my take rate calculation?
No. Take rate should be net revenue after interchange and scheme fees divided by gross payment volume. A gross take rate that includes interchange is misleading because you do not control those pass-through costs. Report net take rate consistently so comparisons across processors like Adyen, Stripe, and Fiserv remain meaningful.
What is the typical net revenue per transaction for card-present versus card-not-present?
For a typical integrated processor, NRPT ranges from $0.10 to $0.30 for card-present transactions and $0.20 to $0.50 for card-not-present ecommerce. The higher ecommerce figure reflects greater risk, higher interchange, and more attached value-added services such as fraud screening and network tokenization.
How often should I track these payment processor KPIs?
Daily: net revenue per transaction, take rate, GPV, and authorization rate. Weekly: merchant churn and average revenue per merchant. Monthly: net revenue retention, LTV to CAC, and CAC. Quarterly: a full dashboard for board review. Daily tracking catches issues early while monthly metrics guide strategic decisions.
What are common failure modes in payment processor KPI measurement?
Measuring GPV growth without take rate, ignoring interchange leakage, counting inactive merchants as active, overweighting LTV from value-added services, and benchmarking against the wrong cohort. Avoid these by tracking net revenue, using a 90-day active definition, and segmenting every metric by merchant size and vertical.
How can I improve my authorization rate?
Use account updater services like Visa Account Updater, implement smart retry logic, and deploy fraud tools such as Stripe Radar. A 2-5% improvement is achievable and flows almost directly to net revenue. Monitor false declines separately from genuine fraud so you do not trade revenue for marginal risk reduction.
Sources
- https://stripe.com/au/annual/2023
- https://www.adyen.com/investor-relations
- https://www.fiserv.com/en/investor-relations.html
- https://squareup.com/us/en/press
- https://www.globalpayments.com/en-ca/investors
- https://www.mckinsey.com/industries/financial-services/our-insights/payments
- https://www.gartner.com/en/documents/4001840
- https://www.forrester.com/report/the-forrester-wave-merchant-payment-providers-q1-2024/
Related on PULSE
- [More payment processor revenue kpis rankings and buying guides](/knowledge)
- [PULSE Tools and calculators](/tools)
- [Everything on PULSE RevOps](/)
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
 pulse-industry-kpisTop 10 Insurance Loss Ratio and Combined Ratio Benchmarks in 2027
 pulse-industry-kpisTop 10 Fitness Center Revenue KPIs in 2027
 pulse-industry-kpisMembership Dues Revenue per Active Member: Association Renewal KPI in 2027
 pulse-industry-kpisFintech Lending: Revenue Per Loan Origination After Risk-Adjusted Charge-Offs in 2027
 pulse-industry-kpisTop 10 Automotive Dealership Revenue KPIs in 2027
 pulse-industry-kpisTop 10 Amusement Park Revenue KPIs in 2027
 pulse-industry-kpisTop 10 Hotel Revenue KPIs in 2027
 pulse-industry-kpisTop 10 Airlines Revenue per Available Seat Mile Performance Indicators in 2027
 pulse-industry-kpisTop 10 Optometry Practice Revenue KPIs in 2027
 pulse-industry-kpisBilling Multiplier Realization: A Consulting Firm’s True Revenue Efficiency KPI in 2027