


Land Mobile Radio integrator market — public safety buying gotchas in 2027
Quality
Certified
The 2027 Land Mobile Radio integrator market for public safety is not the competitive marketplace the brochures imply. A handful of OEMs anchor the channel, integrators resell within locked territories, and margin has quietly migrated from hardware to perpetual refresh, licensing, and service attachments. Buyers who treat an LMR procurement like a cloud RFP will absorb spectrum, siting, and interoperability risk they never priced in.
A county that learns the hard way
Picture a mid-sized county — roughly 400 sworn officers, 12 fire stations, and a shared mutual-aid talkgroup with three neighboring jurisdictions. In early 2027 the county awards a Phase II trunked P25 system to the incumbent integrator that has serviced its legacy analog fleet for a decade. The proposal looks clean: 900 portables, 220 mobiles, eight sites, a five-year service agreement, and a line that reads "interoperability gateway included." The award is unanimous. Everyone feels good.
Fast forward eighteen months. A neighboring city upgrades its own system and the shared talkgroup stops roaming cleanly. The county's gateway license turns out to be metered per talk-path, and the "included" allocation covers two. Adding six more paths is a change order. Then a new commercial licensee appears on an adjacent channel, degrading coverage in a river valley the county assumed was covered. Mitigation means a ninth site — quoted by the same integrator, naturally. By year three the county is paying more in annual service than it budgeted for the entire first year of hardware, and the original procurement lead has rotated to a different department.
Nothing in that story is exotic. It is the default outcome of buying into a channel whose economics reward lock-in. The gotchas are not secrets; they are simply not volunteered. This page walks through the mechanism, the numbers, and the contractual moves that separate agencies who get burned from agencies who don't.
How the channel mechanism actually works
The first thing to internalize is that the market is narrower than the logo count suggests. Industry coverage routinely describes "multiple major OEMs and a robust integrator ecosystem," and on paper that is true. In practice, most public-safety P25 infrastructure in North America traces back to a very small set of manufacturers. The integrators surrounding them are largely territory-locked dealers rather than independent system architects.
That distinction matters enormously. An integrator pitching a trunked system is often economically incapable of recommending a competing OEM even when that OEM would be the better technical fit. Their factory certifications, spare-parts inventory, rebate tiers, and engineering training all point one direction. Ask directly: "How many OEM infrastructure lines are you certified to deploy, and what percentage of your LMR revenue came from each last year?" If the answer is one line at 90%-plus, you are talking to a single-vendor reseller wearing an integrator's badge. That is not automatically disqualifying — but it changes how you read every recommendation they make.
The second mechanism is the margin migration. The advertised price of a P25 subscriber radio in 2027 sits within roughly 10–15% of a commodity two-way radio. That is not where the money is. The real revenue comes from software assurance, feature licenses, encryption modules, over-the-air programming fees, and "lifecycle" guarantees required to keep the system supported. Independent commentary on emerging LMR pricing has flagged that agencies are increasingly pushed into frequent hardware and software refreshes whose necessity is debatable. The headline radio price barely moved; the back-end attachment roughly doubled in real terms over several years according to multiple market trackers.
The third mechanism is risk transfer. Spectrum congestion, tower siting, zoning delays, and AHJ approvals are all passed through to the buyer. The integrator's milestone billing typically is not. If a new licensee degrades your coverage two years post-cutover, that is your problem to mitigate — often by purchasing additional sites from the same integrator.
Read that flowchart as a pre-award checklist. Every "No" branch is a place where the agency, not the vendor, ends up holding the risk. The two branches that matter most in 2027 are the refresh cadence and the live interoperability test, because those are the two the vendor will most resist putting in writing.
Real numbers, ranges, and benchmarks
Concrete figures help here, with the caveat that every deployment differs. Treat these as planning ranges, not quotes.
Total cost of ownership shape. A seven-year contract commonly lands 40–60% above the hardware line item once recurring service, encryption key management, and firmware subscriptions are included. A sheriff's office buying 300 portables at roughly $2,800 each — a headline of about $840,000 — can easily see a total contract value north of $1.6 million. The recurring charges are rarely itemized in the initial proposal.
Service escalation. Maintenance and subscription lines often escalate 5–10% annually after year two. Over a seven-year term that compounds meaningfully. Ask for the escalation schedule in writing for all seven years, not just the first three.
Interoperability patch costs. When a software update breaks cross-system roaming, the "compatibility patch" frequently runs $12,000–$18,000 per site and requires the integrator to re-certify the entire RF footprint. Multiply by site count and you have a five- or six-figure surprise that was not in any budget.
Gateway licensing. ISSI/CSSI gateway licensing is frequently sold as "included" but metered per talk-path. A county with a dozen mutual-aid paths can find that the included allocation covers two or three.
Uptime reality. Honest ranges for actual public-safety LMR availability sit around 99.5% to 99.9%, not the 99.999% implied in marketing. Request third-party uptime audits for the specific configuration, and confirm whether planned maintenance windows are excluded from the SLA math.
Spectrum pressure. Urban LMR band utilization has been reported above 85% in several recent market reports. That is the environment you are deploying into, and it is not static.
Technician scarcity. Integrating modern digital platforms with legacy LMR has increased system complexity, and qualified technicians are scarce. That scarcity is real — and it is also the standing justification for time-and-materials change orders, premium after-hours rates, and travel-loaded service tickets that quietly dominate the operating budget. Few agencies audit LMR service invoices the way they audit IT managed-services invoices.
Termination economics. Early-exit penalties are often structured so that switching costs more than staying. Read that clause before you sign, and model the year-four exit cost explicitly.
Trade-offs and alternatives
There is no clean escape from a thin channel, but there are meaningful choices.
Single-OEM vs. multi-OEM integrator. A multi-OEM integrator can present genuine alternatives and is more likely to write competitive service terms. The trade-off is that even multi-OEM shops have a dominant line, and their depth of expertise on the secondary line may be shallow. Ask for reference deployments on the secondary line specifically.
Capital purchase vs. subscription model. Subscription-flavored LMR spreads cost and shifts refresh risk to the vendor — in theory. In practice, read the refresh obligations carefully; many "subscription" structures still require the agency to fund hardware replacement on a fixed cadence. The trade-off is cash-flow predictability versus long-run total cost.
Incumbent renewal vs. competitive rebid. Rebidding is expensive and disruptive, and incumbents know it. But an agency that never rebids has no pricing leverage at all. A middle path: rebid the service and maintenance layer separately from the infrastructure, even if the infrastructure stays with the incumbent.
Open-architecture vs. proprietary. A small handful of integrators offer open-architecture designs, allow third-party maintenance, or use modular contracts. These are exceptions, not the rule, and their combined market share is under 10%. If you find one, the trade-off is usually a smaller reference base and less mature tooling — but far better long-run leverage.
Buy now vs. extend the legacy system. Sometimes a two-year bridge on the existing system, paired with a properly structured rebid, beats signing a bad seven-year deal under time pressure.
The point of that second diagram is sequencing. Most agencies get hurt because they let a deadline force a signature. Buying eighteen months of runway on the legacy system is almost always cheaper than a bad seven-year contract.
Common pitfalls and how to avoid them
Pitfall one: treating "P25 compliant" as "interoperable." Compliance is not interoperability. A radio that passes P25 Common Air Interface testing can still fail to roam across a neighboring jurisdiction's trunked system if the integrator used proprietary site-connection protocols or custom talk-group routing. The fix: demand a live, multi-vendor interoperability demonstration before signing, not a certification letter from the manufacturer.
Pitfall two: accepting "included" without a line item. Every "included" claim should be itemized with a quantity, a unit, and a cap. Gateway talk-paths, encryption modules, firmware updates, and programming seats are the usual suspects.
Pitfall three: ignoring the refresh treadmill. Map the vendor's stated end-of-life dates against your own budget cycle. If the refresh cadence is not fixed in the contract, assume it will accelerate.
Pitfall four: letting the integrator own the spectrum and siting risk. Negotiate contractual responsibility for coverage degradation caused by third-party spectrum changes, or at minimum a defined remediation path with capped costs.
Pitfall five: not auditing service invoices. Set up the same invoice-audit discipline you use for IT managed services. Travel load, after-hours premiums, and parts markups are where the quiet money goes.
Pitfall six: assuming the integrator in front of you is the exception. There are integrators that genuinely behave better — published change-order policies, multi-OEM certifications, honest end-of-life roadmaps, willingness to write spectrum and interoperability commitments into the contract. But a handful of better-behaved firms does not reform a channel whose underlying economics reward lock-in. Assume the norm and require the exception to be proven in writing.
Pitfall seven: losing institutional memory. The team that negotiated the deal is often gone by year four, exactly when the expensive clauses activate. Write a plain-language contract summary and store it where the next procurement lead will find it.
Related questions
Why does the LMR integrator channel stay so narrow?
Because factory certifications, spare-parts inventory, and rebate tiers lock dealers to one or two OEM lines. An integrator cannot credibly recommend a competing manufacturer without walking away from most of their revenue. That structural reality, not malice, keeps the channel thin.
Is P25 compliance enough to guarantee multi-agency roaming?
No. P25 covers the air interface, not site-connection protocols, talk-group routing, or key management. Two compliant systems can still fail to roam. Only a live cross-agency test with the actual neighboring system proves interoperability.
How much should an agency budget above the hardware quote?
Plan for 40–60% above the hardware line over seven years, with service escalating 5–10% annually after year two. Model the year-four exit cost explicitly before signing anything.
Can a small agency get competitive LMR pricing at all?
Sometimes, by splitting the infrastructure bid from the service and maintenance bid. Even when the infrastructure stays with the incumbent, a separately competed service layer creates real pricing pressure.
What is the single most valuable contract clause?
A fixed refresh cadence with capped escalation, paired with a defined interoperability test protocol. Those two clauses neutralize the largest sources of surprise cost in years three through seven.
FAQ
What makes the LMR integrator market different from normal IT procurement? Public-safety LMR is dominated by a small number of OEMs that control the ecosystem, and integrators operate within narrow regional or brand-specific channels. Unlike IT, where many vendors compete on price and features, LMR buyers face limited choices and heavy lock-in through proprietary service contracts and refresh cycles.
Why are multi-year service attachments a bigger cost than the hardware? The headline radio equipment often represents less than 30% of total contract value. The real expense comes from mandated maintenance, software subscriptions, and periodic upgrades priced with little competition, often escalating 5–10% annually after year two.
Can an agency avoid vendor lock-in by choosing a P25-compliant system?
P25 compliance ensures interoperability at the air interface, but it does not prevent proprietary management software, encryption key management, or network management tools from tying you to a single vendor. True multi-vendor competition rarely survives past the initial procurement.
How should a buyer evaluate integrator claims about mission-critical reliability? Request independent third-party uptime audits for the specific system configuration, not generic marketing. Most integrators will only provide internal SLA data, which can exclude planned maintenance windows or certain failure modes. Honest ranges for actual uptime sit around 99.5% to 99.9%, not the 99.999% often implied.
What hidden costs appear in years three through seven? Typical surprises include mandatory firmware update fees, proprietary battery and accessory replacements that double in price, and end-of-life notices on components that force premature upgrades. Budget for 20–40% annual cost growth after the initial contract term.
Are there any integrators that break the lock-in pattern? A small handful offer open-architecture designs, allow third-party maintenance, or use modular contracts. However, these are exceptions, not the rule, and their combined market share is under 10%. Most buyers will still encounter the standard captive model.
Sources
- FCC — Land Mobile Radio and public safety spectrum
- APCO International — public safety communications standards and resources
- NPSTC — Funding and Maintaining Public Safety Radio Systems
- CISA — Public Safety Communications and interoperability guidance
- Mission Critical Partners — emerging LMR system pricing model analysis
- Coherent Market Insights — Land Mobile Radio Systems Market
- Fortune Business Insights — Land Mobile Radio Market report
- Motorola Solutions — LMR system documentation
Related on PULSE
- The Project 25 P25 radio integrator market in 2027 — public safety procurement gotchas
- Public safety radio interoperability still fails multi-agency response in 2027
- Dispatch and command-and-control integrator market in 2027 — gotchas for buyers
- Are Land Leases Worth It?
- How RevOps teams audit vendor service invoices
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 acg-systemsUtility and SCADA communications integrator market — co-op buyer challenges in 2027
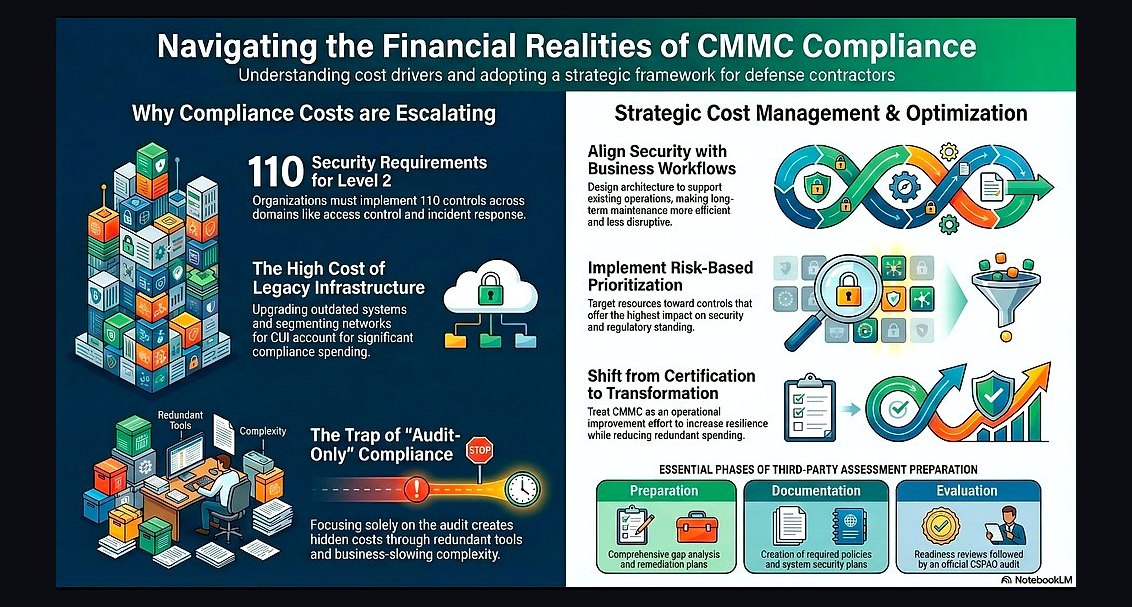 acg-systemsCMMC 2.0 compliance cost — why small federal integrators are getting crushed in 2027
 acg-systemsThe Annapolis MD AV integrator market — what buyers should watch for in 2027
 acg-systemsNG911 PSAP modernization integrator market — why these projects fail in 2027
 acg-systemsFAA air traffic control comms integrator market — NextGen modernization realities in 2027
 acg-systemsFederal AV+comms warranty and service gaps — what happens after install in 2027
 acg-systemsAir-to-ground communications integrator market — what buyers need to know in 2027
 acg-systemsFederal IDIQ and GWAC contract integrator market — buyer + integrator friction in 2027
 acg-systemsThe Motorola MOTOTRBO and ASTRO lock-in in public-safety LMR — buyer alternatives in 2027
 acg-systemsCleared-workforce shortage hitting federal AV+comms integrators in 2027