

How is the 2027 vendor consolidation wave forcing RevOps to kill data silos between CDP and CRM?
 Curated byKory White · Fractional CRO · Maryland
Quality
Certified
The 2027 vendor consolidation wave is forcing RevOps to kill CDP-CRM data silos because AI-driven scoring, orchestration, and buying-committee tracking break the moment marketing and sales data disagree. Teams either merge onto one platform or bridge with reverse ETL — but standing still means duplicate records, contradictory lead scores, and stalled pipeline velocity that consolidation was supposed to fix.
The two paths RevOps can take to close the CDP-CRM gap
When a vendor consolidation initiative lands on a RevOps leader's desk, there are really only two structurally different responses, and picking the wrong one wastes a budget cycle. The first path is full platform consolidation: retiring a standalone CDP like Segment or mParticle and adopting a CRM vendor's native data layer instead, most commonly Salesforce Data Cloud or HubSpot's Operations Hub-powered Smart CRM. This collapses behavioral data (page views, product usage, email engagement) and transactional data (opportunity stage, contract value, support tickets) into one schema owned by one vendor, which is exactly what the consolidation wave is pushing buyers toward — fewer contracts, fewer integrations, one throat to choke.
The second path is a bridge architecture: keep the CDP and CRM as separate systems of record but connect them with reverse ETL tools such as Hightouch or Census, syncing CDP segments into CRM list views and CRM status changes back into CDP audiences in near real time. This path exists because full consolidation isn't always possible — a company running a legacy Oracle CRM, a heavily customized Salesforce org with hundreds of custom objects, or a multi-brand structure with incompatible schemas often can't rip and replace without a multi-quarter project. Gartner's forecast that 60% of B2B organizations will have consolidated their CDP and CRM stacks into a single data layer by 2027 describes the first path; the remaining 40% are not ignoring the mandate, they are executing the second one.
The trade-off is straightforward: consolidation gives you a single schema and native AI governance but forces a migration with real failure risk, while bridging preserves your existing systems and vendor relationships but leaves you permanently dependent on sync jobs that can drift, lag, or silently break. Neither path is "doing nothing" — the vendor consolidation wave has made the do-nothing option, tolerating the silo, the one option that reliably produces bad outcomes, because AI agents in both systems are now making autonomous decisions (sending emails, reprioritizing deals, adjusting discounts) based on whichever data source they can see, and a silo means they see different, contradictory versions of the same prospect.
How to decide between consolidating and bridging
The decision hinges on three questions RevOps should answer before signing anything: does a common customer ID already exist across both systems, how much data latency can the business tolerate, and how entrenched is the CRM. Answer those honestly and the decision tree below resolves cleanly — most teams sort into "bridge" if any legacy constraint is present, and "consolidate" only when the CRM is modern, the ID problem is solved, and there's an internal team to run the migration.
Reading the tree in practice: a mid-market company on HubSpot with no legacy baggage almost always lands on full consolidation into Smart CRM, because the native integration removes the sync-drift risk entirely. A large enterprise running Salesforce alongside a heavily customized Oracle instance for a legacy business unit almost always lands on bridging, because the cost of migrating the legacy unit outweighs the benefit for the next two to three years. The mistake RevOps teams make most often is skipping the ID question and jumping straight to "which platform should we buy" — without a common customer ID, neither path works, and identity resolution has to come first regardless of which architecture you eventually choose.
What the numbers say about each path
The case for treating this as urgent rather than optional rests on specific, quotable figures, not vague warnings. On the cost-of-inaction side: RevOps teams operating with unresolved CDP-CRM silos report spending 30-50% of their time on data reconciliation tasks rather than revenue-generating work, per benchmarks circulated by Revenue.io and LeanData. Forrester has flagged that unchecked AI silos in a consolidated stack — meaning the platforms were merged but governance wasn't — can produce 20-30% revenue leakage, because AI agents keep acting on the stale half of the merged data. Winning by Design has tracked sales cycle length increasing roughly 25% since 2024, a trend that makes single-source-of-truth engagement tracking non-negotiable for any team relying on AI-assisted forecasting.
On the migration-risk side, Gartner reports that roughly 40% of Salesforce Data Cloud implementations fail due to poor data mapping — a number RevOps leaders should treat as a planning input, not a scare statistic: it means field-mapping and deduplication work needs its own budgeted phase, not a rushed weekend before go-live. Buying committee size also matters to the ROI case: Gartner puts typical B2B buying committees at six to 10 people per deal, and every one of those people is generating dark-funnel signal (content downloads, webinar attendance, private event RSVPs) that only a unified profile can connect to the named contacts sales is tracking in the CRM.
On the success-metric side, teams that do consolidate successfully are targeting a profile completeness rate — the percentage of records with both CDP behavioral data and CRM transactional data merged — above 85%, up from the 40-60% typical of siloed environments. Post-integration, lead scoring precision improvements of 15-25% are the commonly cited AI model accuracy lift, sync latency targets sit under 5 minutes for critical events like demo requests, cross-system duplication rates are pushed below 2% using tools like DemandTools or Validity, and early adopters report pipeline velocity (time from lead creation to closed-won) accelerating 10-18% once the silo is gone. Those five numbers — 85% completeness, 15-25% scoring lift, sub-5-minute latency, sub-2% duplication, 10-18% velocity gain — are what RevOps should put in front of finance to justify the consolidation spend, because they tie directly to pipeline outcomes rather than IT tidiness.
Implementation details and sequencing
Regardless of which path a team picks, the sequencing looks similar, and skipping steps is what causes the 40% Data Cloud failure rate cited above. The work starts with an audit and identity resolution phase, moves through architecture selection, then governance, then AI retraining, and only then goes live — running these out of order (especially retraining AI models before the schema is stable) is the single most common cause of a botched consolidation.
The audit phase should catalog every field that feeds a scoring model or automation trigger in both systems — not just the obvious ones like email and lead status, but the ones that quietly diverge, like "engaged" definitions that differ between a CDP's session-based tracking and a CRM's activity-log-based tracking. Identity resolution typically uses a privacy-safe hashing protocol so that email, device ID, and CRM account ID all map to one record; skipping this step is what produces the "ghost profile" problem, where a prospect looks engaged in the CDP and unresponsive in the CRM simultaneously.
Once architecture is chosen, the governance phase is where most teams under-invest. This means setting explicit data freshness SLAs (for example, CDP events must land in the CRM within five minutes) and conflict resolution rules (for example, CRM field wins over CDP for deal stage, but CDP wins for engagement recency) — without written rules, AI agents in tools like Gong, Clari, or a CRM's native copilot will pick a source inconsistently, and nobody will notice until a prospect who signed a contract gets a "we miss you" win-back email because the CDP hadn't caught up. Tools like Monte Carlo or Bigeye for data lineage tracking, and OneTrust or TrustArc for consent orchestration, are the practical governance layer — the second matters because a unified profile that still respects a CCPA opt-out or a GDPR consent withdrawal has to enforce that policy identically across both systems, or marketing automation will keep retargeting someone the CRM has already flagged as opted out.
Retraining AI scoring and next-best-action models comes only after the schema and governance rules are stable — retraining against a schema that's still shifting wastes the retraining cycle and reintroduces the exact scoring contradictions consolidation was meant to fix. SaaStr's guidance to pilot on roughly 20 accounts before full rollout exists precisely to catch these sequencing errors cheaply: a small pilot surfaces mismatched field mappings and broken triggers before they touch the full pipeline. Expect the full sequence to take three to six months for a mid-market company (200-500 employees) and nine to 12 months for an enterprise carrying custom objects and legacy integrations — and budget for monthly drift monitoring indefinitely afterward, because sync rules and schemas both decay as new tools get added to the stack.
Related questions
Does full CDP-CRM consolidation always beat a reverse-ETL bridge?
No. Consolidation wins when the CRM is modern and a common ID already exists; a bridge via Hightouch or Census wins when a legacy CRM, heavy customization, or a multi-brand structure makes migration too risky to justify in the near term.
What breaks first when CDP and CRM data disagree?
AI scoring and orchestration break first — a next-best-action engine acting on stale CRM status while the CDP shows active dark-funnel behavior sends contradictory emails, misprioritizes deals, and erodes rep trust in the tooling.
How long does a CDP-CRM consolidation actually take?
Three to six months for a mid-market company doing straightforward data mapping and dedup; nine to 12 months for an enterprise with custom objects and legacy integrations that need a phased migration.
Is a data lake a substitute for consolidating CDP and CRM?
Only with a dedicated data engineering team running tools like Snowflake or BigQuery plus dbt for transformation and Monte Carlo for monitoring — most RevOps teams find a lake too slow for real-time 2027 AI scoring needs.
FAQ
What is the biggest risk of keeping CDP and CRM separate through the 2027 consolidation wave? The biggest risk is AI-driven revenue leakage: when scoring models in the CDP and CRM disagree on intent, sales chases the wrong leads, marketing sends irrelevant campaigns, and Forrester's estimated 20-30% revenue leakage range becomes a realistic outcome rather than a hypothetical one.
How do I choose between consolidating into the CRM versus the CDP? If the CRM is Salesforce with more than roughly 500 employees, consolidating into Salesforce Data Cloud is usually right because it ships with native AI governance; SMB teams on HubSpot typically stay in Smart CRM; enterprises with legacy CRMs are better served keeping the CDP as master and bridging with reverse ETL.
What role does AI governance play once CDP and CRM are consolidated? Governance stops AI agents from acting on stale or conflicting data by enforcing data freshness SLAs and explicit conflict resolution rules — without them, a merged schema still produces contradictory automated actions, just from one platform instead of two.
How does consolidation change buying committee tracking? A unified profile lets RevOps see interactions from all six to 10 typical buying committee members across marketing, sales, and support; without it, the CRM usually tracks only the primary contact while the CDP's dark-funnel signal from the rest of the committee goes unused.
Does consolidation eliminate compliance risk from GDPR and CCPA? It reduces it but doesn't eliminate it — GDPR fines can reach 4% of global annual revenue while CCPA penalties are assessed per violation, so a unified profile still needs a single enforced consent policy so marketing automation can't act on CDP data after a CRM-recorded opt-out.
What's a realistic first KPI to track after starting consolidation? Profile completeness rate — the share of records with both CDP behavioral data and CRM transactional data merged — is the earliest signal; targeting above 85%, up from a typical siloed baseline of 40-60%, shows the merge is actually working before scoring or velocity metrics have time to move.
Sources
- Gartner: Predicts 2027 research on data and analytics strategy
- Forrester: B2B revenue operations research
- McKinsey: AI in sales and revenue operations
- SaaStr: RevOps and go-to-market playbooks
- Salesforce: Data Cloud overview
- HubSpot: Smart CRM and Operations Hub
- Segment (Twilio): Customer Data Platform and Personas
- OneTrust: Consent and preference management
Related on PULSE
- How do consolidated CRM and CDP platforms in 2027 actually reduce data silos for RevOps teams?
- How are RevOps teams in 2027 handling data silos left by vendor consolidation?
- What data silos most damage revenue operations after vendor consolidation?
- Is the 2027 vendor consolidation wave killing best-of-breed point solutions for RevOps?
- What does the 2027 vendor consolidation wave mean for your RevOps tool stack?
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 revopsHow is AI in the funnel reshaping the scoring of B2B inbound leads in 2027?
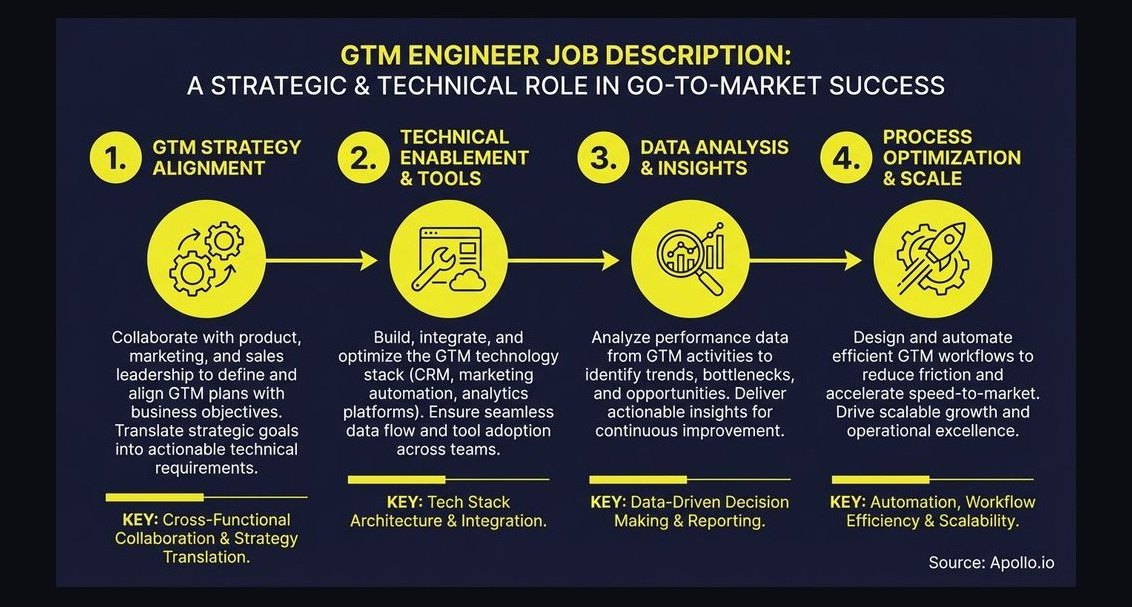 revopsWhat is a GTM engineer and why is the role exploding in 2027?
 revopsWhat does the WNBA's 2026 CBA mean for player pay and revenue sharing in 2027?
 revopsWhat triggers are early-stage RevOps teams using in 2027 to hand off AI-qualified leads to human sales reps without losing context?
 revopsWhat is the cost of AI vendor lock-in for B2B sales teams in 2027?
 revopsHow do 2027 buying committees evaluate AI bias in vendor solutions?
 revopsHow do you rebuild a sales team's trust in the forecast after a mid-year quota reset in 2027?
 revopsHow can RevOps use AI in the funnel to identify stalled deals before the buying committee loses interest in 2027?
 revopsWhat vendor consolidation moves are most likely to disrupt existing ABM workflows in 2027?
 revopsHow is AI changing sales territory and quota planning in 2027?