


What’s the most persuasive technique from *Pitch Anything* for investor pitches?
Quality
Certified
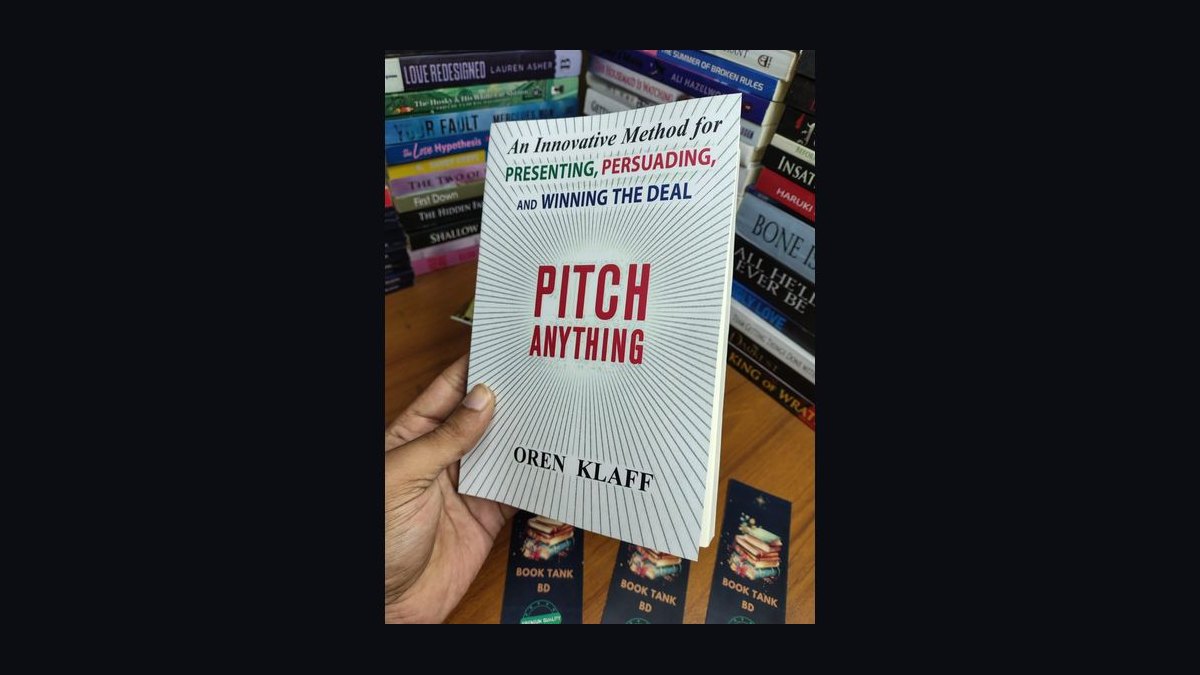
The most persuasive technique from *Pitch Anything* for investor pitches is Frame Control: deliberately setting and defending the mental frame of the meeting so you are the prize, not the supplicant. Oren Klaff argues every pitch is a contest of frames, and whoever holds the stronger frame — status, authority, or scarcity — controls the outcome.
The outcome you should expect
When Frame Control is executed well, the measurable outcome is a shift in the *conversation ownership* rather than a guaranteed check. In practical terms, founders who internalize this technique report that investor meetings stop feeling like auditions and start feeling like exploratory conversations between peers. The investor asks "how can I participate?" instead of "why should I care?" You should expect three concrete changes. First, the investor's first question changes from a challenge ("What's your traction?") to a curiosity probe ("How did you find this market?"). Second, the meeting runs on your agenda — you control the clock, the sequence, and the transitions. Third, the follow-up cadence flips: instead of you chasing the investor, the investor's associate emails you within 24-48 hours asking for the data room.
That said, the outcome is not instant conversion. Frame Control changes the *quality* of the interaction and the *velocity* of the next step, not the underlying investment merits. A weak business with a strong frame still fails diligence; a strong business with a weak frame often dies in the first meeting. The realistic expectation is that Frame Control moves you from "one of forty decks this week" to "the meeting they remember and want to continue." Klaff's own framing is that the pitch is not a presentation — it is a status negotiation that happens in the first 90 seconds and gets confirmed or reversed over the following 20 minutes.
For a founder, the practical payoff of this strategy is leverage. Leverage shows up as better terms, faster timelines, and warmer introductions. It also shows up internally: you stop over-preparing 40 slides and start rehearsing three or four frame transitions. The outcome you should track is not "did they invest" but "did the power dynamic shift in the room." If it did, the deal math usually follows.
What drives that outcome
The outcome is driven by four interlocking mechanisms that Klaff describes as the operating system of a pitch. Understanding each one lets you diagnose why a meeting went sideways and which lever to pull next time.
1. The crocodile brain filters first. Before the investor's analytical mind engages, their limbic system — the "crocodile brain" — decides whether you are a threat, a meal, or irrelevant. Dense slides, jargon, and long financial projections read as cognitive threat and trigger disengagement. Simple, visceral, concrete language reads as safe and interesting. This is why the first 60 seconds of a pitch must speak to instinct, not to the spreadsheet. If the crocodile brain rejects you, no amount of later data recovers the meeting.
2. Status is set, not earned. Investors walk in with a default frame: "I have capital, you want it, therefore I am the senior party." Klaff's core move is to *not accept that frame*. You enter with your own frame — "I have a rare asset and limited capacity, and I'm here to see whether you qualify." This is not arrogance; it is a deliberate repositioning that changes the investor's hormonal state from relaxed evaluation to attentive curiosity.
3. Attention runs on dopamine loops. The brain craves closure. A well-built pitch creates small knowledge gaps ("here's what everyone assumes — here's what actually happens") and then closes them. Each open-and-close cycle releases dopamine and buys you another 2-3 minutes of genuine attention. A linear pitch — problem, solution, market, team, ask — provides no gaps and therefore no dopamine, so attention decays within about 4 minutes.
4. Scarcity and social proof do the closing work. Once the frame is yours, the close is not a request. It is a qualified invitation: "We're taking two strategic investors this round, and we've had strong interest." This triggers loss aversion — the investor now fears missing the deal more than they fear losing money.
The diagram above is the decision tree every pitch follows. The fork happens early, and once the investor's frame wins, the meeting rarely recovers. This is why Klaff insists the first 90 seconds are the whole game.
Benchmarks and realistic ranges
Frame Control is a soft skill, but the inputs and outputs are measurable enough to benchmark. Use these ranges to calibrate your own pitch rather than to chase a magic number.
Time-to-frame-set: The frame is established in the first 60-90 seconds. If you have not explicitly taken control of the agenda by the 2-minute mark, you are operating inside the investor's frame for the rest of the meeting. Benchmark: state your time constraint and your intent within the first 45 seconds.
Pitch block length: Klaff recommends chunks of 2-4 minutes separated by a pattern interrupt. Anything longer than 4 minutes without a break lets the analytical brain take over and start hunting for flaws. Benchmark: 4-6 blocks in a 20-minute meeting, each ending with a question, a pause, or a story beat.
Talk-to-listen ratio: In a strong Frame Control pitch, the founder talks roughly 60-70% of the time early, then drops to 40-50% after the first frame break as the investor starts asking questions. If you are talking 90% of the time, you have not created engagement — you have created a monologue.
Pattern interrupts per meeting: 2-4 well-placed interrupts. Fewer than 2 means the pitch is linear and attention is decaying. More than 4 starts to feel gimmicky or evasive.
Silence after the ask: 3-5 seconds of deliberate silence. This is the single highest-yield micro-technique. Most founders fill the silence within 1 second, which signals anxiety and hands the frame back to the investor.
Follow-up velocity: With strong frame control, expect a substantive follow-up within 24-72 hours. If the investor's team goes quiet for more than a week after a warm meeting, the frame was likely lost at some point.
Conversion expectations: Frame Control does not turn a no into a yes on its own. Realistically, a well-framed pitch converts first meetings to second meetings at roughly 30-50% versus 10-20% for unframed pitches, depending on stage and sector. The gain is in the funnel, not in a single meeting.
Rehearsal time: Budget 3-5 hours of deliberate practice on frame transitions alone — not on the content of the deck. Most founders over-rehearse the slides and under-rehearse the interruptions.
Risks, edge cases, and failure modes
Frame Control is powerful precisely because it manipulates status and emotion, which means it fails loudly when misapplied. Here are the failure modes to watch for.
Failure mode 1: Arrogance mistaken for frame. The line between "I am the prize" and "I am dismissive" is thin. If your frame break comes across as contempt — interrupting the investor, refusing to answer direct questions, or dismissing legitimate concerns — you lose the room permanently. The test: your frame should make the investor feel *invited*, not *diminished*. If they look defensive rather than curious, you have overshot.
Failure mode 2: Frame without substance. Frame Control buys attention; it does not buy belief. If you set a dominant frame and then have no compelling answer for unit economics, market timing, or why-now, the investor feels manipulated. The frame amplifies whatever is underneath it. Amplified nothing is still nothing.
Failure mode 3: Cultural and personality mismatch. Direct frame-breaking plays differently across cultures and personalities. In some investor contexts — particularly institutional or late-stage funds — an aggressive frame break reads as inexperience. With analytical, skeptical investors, a quieter frame ("I'll take 15 minutes, and if it's not relevant after 5, tell me and I'll stop") often works better than a bold one. Read the room before you choose your frame.
Failure mode 4: Over-scripting. Frame breaks must feel spontaneous. If you deliver a rehearsed line with the timing of a stand-up set, the investor senses the manipulation and the frame collapses. Practice until the moves are reflexes, then let them emerge naturally from the conversation.
Failure mode 5: Losing composure under challenge. The moment you get defensive, flustered, or over-eager, the frame is gone. This is the hardest failure mode because it is emotional, not tactical. The fix is preparation: rehearse the three hardest questions you expect and practice answering each one briefly, calmly, and then pivoting back to your narrative.
Failure mode 6: Ignoring the analyst in the room. Many funds send an associate whose job is to stress-test the numbers. If you treat the associate as a junior and only work the partner, you lose the diligence layer. Frame Control applies to everyone in the room.
Edge case: The investor who enjoys the game. Some experienced investors recognize Frame Control immediately and enjoy it. They will test you by trying to break *your* frame. This is a good sign — it means they are engaged — but you must hold the frame without escalating into a status fight. The correct response is warmth plus firmness: acknowledge the challenge, then calmly redirect.
A practical rollout plan
Frame Control is a skill, not a slide. Roll it out over four weeks of deliberate practice before your next investor meeting.
Week 1 — Diagnose your current frame. Record yourself delivering your existing pitch. Watch for the tells of a weak frame: apologizing, over-explaining, filling silence, mirroring the investor's skeptical tone, discounting your valuation unprompted. Write down every instance. Most founders find 6-10 frame leaks in a 20-minute pitch.
Week 2 — Build your frame toolkit. Write three specific frame breaks you can deploy: one for time ("I have 15 minutes and I'll stop at 12"), one for authority (a question that reframes a skeptical challenge), and one for scarcity (a statement about limited capacity or existing interest). Rehearse each aloud 20 times until it sounds conversational, not scripted.
Week 3 — Restructure the pitch into dopamine loops. Break your deck into 4-6 blocks of 2-4 minutes. Between each block, insert a pattern interrupt: a question, a short story, a pause, or a physical move. Cut any slide that cannot be explained in 90 seconds. The goal is rhythm, not completeness.
Week 4 — Pressure-test with a hostile audience. Find a colleague, a mentor, or a peer founder who will play a skeptical investor. Have them interrupt, challenge your numbers, and try to take control of the meeting. Your job is to hold the frame without becoming defensive. Repeat until you can do it while staying warm and calm.
The loop matters: after every live pitch, debrief against the same diagnostic checklist from Week 1. Frame Control compounds with reps. Founders who run this cycle three or four times typically report that the meeting dynamic shifts noticeably — investors ask different questions, follow up faster, and negotiate from a more collaborative posture.
One final note on ethics: Frame Control is not deception. It is the honest presentation of your value in a format the investor's brain can actually receive. If your business is not genuinely scarce, qualified, or interesting, no frame will save it. The technique works because it clears away the cognitive noise that prevents good ideas from being heard.
Related questions
What is the single most important frame to control in an investor pitch?
The Power Frame. If you enter as a supplicant, every other technique is undermined. Establish early that you are choosing the investor as much as they are choosing you — through your time constraint, your selectivity language, and your calm refusal to over-explain.
How long should a Frame Control pitch actually last?
Aim for 15-20 minutes of structured content, regardless of the slot you are given. If the investor offers 30 minutes, use 15-18 and leave the rest for questions. Controlling the clock is itself a frame move — you end on your terms, not theirs.
Does Frame Control work in a virtual pitch over Zoom?
Yes, with adjustments. Physical pattern interrupts are unavailable, so lean harder on verbal ones: deliberate pauses, direct questions, and screen-share reveals timed for impact. Turn your camera on, keep your framing tight, and avoid reading from notes — all of these preserve the frame in a low-bandwidth medium.
Can you recover if you lose the frame mid-pitch?
Sometimes. The recovery move is a deliberate reset: pause, acknowledge the shift ("Let me step back for a second"), and re-anchor with a story or a provocative question. It works roughly half the time. Prevention is far cheaper than recovery.
Is Frame Control manipulative?
Klaff frames it as persuasion grounded in how brains actually process high-stakes decisions. If your intent is to inform and qualify rather than to deceive, Frame Control is a legitimate communication technique. The ethical line is whether the substance behind the frame holds up under diligence.
FAQ
**What exactly is a "frame" in *Pitch Anything*?** A frame is the unconscious mental structure that defines who holds power, who is the expert, and who is the prize in a conversation. Every meeting has one; the question is only who set it. Klaff's argument is that the person with the stronger frame wins the deal regardless of the underlying merits.
Why does the most persuasive technique involve status rather than data? Because investors decide emotionally in the first seconds and justify analytically afterward. Data cannot be processed until the crocodile brain has classified you as safe and interesting. Frame Control sets that classification first, which is what makes the data land later.
How is this different from just being confident? Confidence is a feeling; Frame Control is a set of specific, rehearsed moves — time constraints, pattern interrupts, scarcity statements, deliberate silence. Confidence without technique leaks under pressure. Technique gives confidence a structure to operate inside.
What's the fastest way to practice Frame Control before a real pitch? Record yourself, identify your frame leaks (apologizing, over-explaining, filling silence), then rehearse three specific frame breaks aloud 20 times each. Follow with one hostile roleplay session. That is roughly 4-6 hours of work and produces a visible change in meeting dynamics.
Do I need to be aggressive to hold a frame? No. Warmth plus firmness outperforms aggression. Aggression reads as insecurity and invites the investor to fight. Calm, unhurried certainty — especially in the face of a skeptical question — is the strongest frame signal available.
How does Frame Control interact with negotiation after the pitch? It carries over directly. Founders who held the frame in the pitch negotiate better terms because the investor already perceives them as a scarce, qualified counterparty. Founders who lost the frame often find themselves discounting valuation in the first negotiation call.
Sources
- https://pitchanything.com/
- https://hbr.org/
- https://www.gsb.stanford.edu/insights
- https://www.forbes.com/
- https://techcrunch.com/
- https://www.ycombinator.com/library
- https://www.inc.com/
- https://www.nber.org/
Related on PULSE
- What’s the most persuasive story structure from *Pitch Anything* for a product demo?
- How do you use *Pitch Anything* to frame pricing during a procurement call?
- What’s the key lesson from *Pitch Anything* about managing pre-pitch anxiety?
- How do you use *Pitch Anything* to keep an audience engaged during a virtual demo?
- What’s the most practical technique from *New Sales. Simplified.* for handling a “send me info” objection?
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 bsHow does *SNAP Selling* adapt to remote sales teams in 2027?
 bsHow do sales leaders build a repeatable outbound prospecting motion without a big SDR team in 2027?
 bsWhat’s the one principle from *How to Win Friends and Influence People* that works best for virtual meetings?
 pulse-booksWhat is the best way to approach Book Summaries in 2027?
 bsHow do you negotiate a complex enterprise contract when the buyer has more leverage than you in 2027?
 bsHow can *Fanatical Prospecting* help you maintain a full pipeline without burning out in 2027?
 bsHow does *Never Split the Difference* apply to salary negotiations in 2027?
 pulse-booksHow much do Book Summaries cost in 2027?
 bsHow do you run a sales compensation plan that keeps reps motivated without overpaying in 2027?
 bsWhat’s the main lesson from *Pitch Anything* for presenting to a skeptical board in 2027?