


Top 10 Best Tech Stack Tools for Rideshare and Mobility Marketplaces in 2027
Quality
Certified
The 10 best tech stack tools for rideshare and mobility marketplaces are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Mapbox Navigation SDK
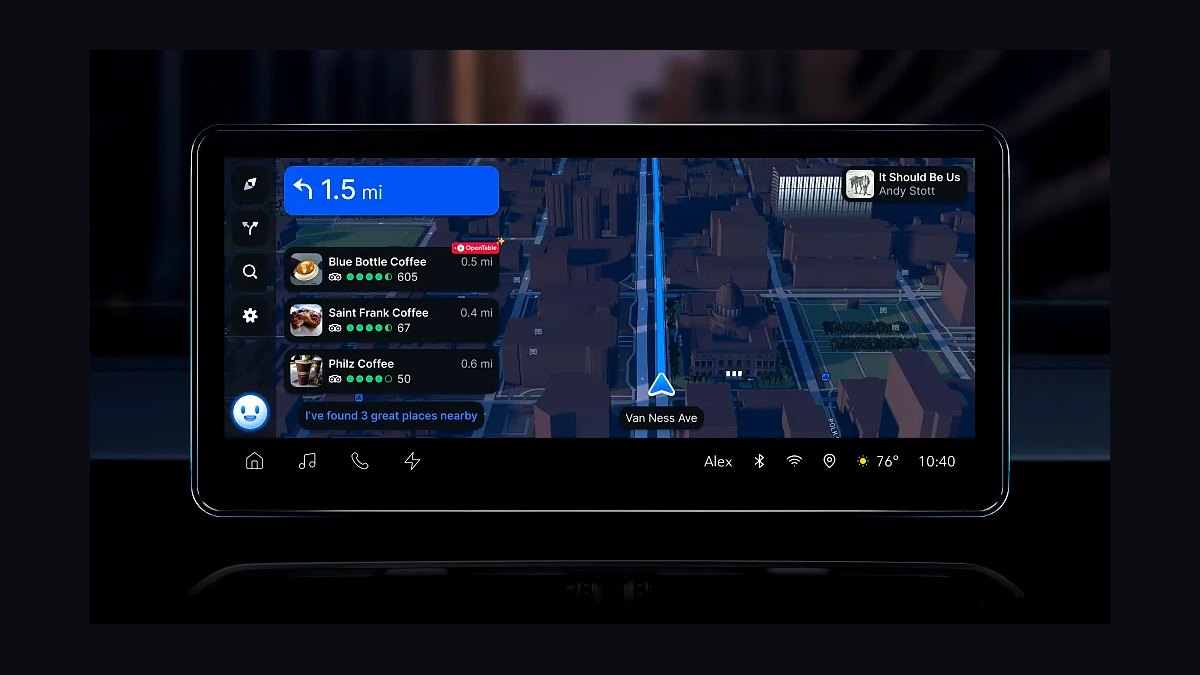
Mapbox ranks first because it is the primary maps and routing layer at Uber, Lyft, and Grab, powering in-app turn-by-turn navigation, matrix routing, and geofence rendering at roughly $0.50-$5.00 per 1,000 requests depending on commit volume. Uber named Mapbox its primary maps partner in 2024, and the SDK ships native navigation for iOS and Android without a separate routing service.
It is for operators past the MVP stage who need production-grade navigation and can commit to volume pricing. The tradeoff is that Mapbox geocoding and place autocomplete are weaker than Google's, so most serious operators run Google Maps Platform alongside it as a fallback and to keep both vendors honest on pricing. Below it on this list, Google Maps Platform covers the geocoding gap Mapbox leaves open.
2Google Maps Platform
Google Maps Platform ranks second because it supplies the geocoding, place autocomplete, and second routing source that every large operator runs alongside Mapbox, at roughly $5-$17 per 1,000 requests before volume discounts. Lyft, Bolt, and Cabify all run it in production, and its place data is the industry benchmark for address resolution and points of interest. The redundancy matters: a single map provider outage can take pickups offline in a region for hours.
It is for operators who need best-in-class geocoding and a routing fallback, not for startups trying to minimize spend in city one. The tradeoff is cost — at national scale the bill runs into millions per year, which is why Mapbox handles the high-volume navigation leg. Compared to Mapbox directly above, Google is the accuracy play and Mapbox is the cost-and-SDK play; serious operators buy both.
3Snowflake Data Cloud
Snowflake ranks third because it is the analytical store and finance system of record at Uber, Lyft, and Cabify, holding the trip ledger, marketplace metrics, and settlement data that finance closes the books on. Combined with Databricks, annual spend at a national operator runs $5M-$50M+, and the two-warehouse pattern — Snowflake for SQL analytics, Databricks for ML — is now the rideshare default. Every trip event lands here for BI, fraud review, and regulatory reporting.
It is for operators past 100K trips per day who need a single source of truth finance and analytics can both query. The tradeoff is that Snowflake is not an ML training platform — Spark workloads for ETA and surge models belong on Databricks. Compared to Google Maps Platform above, Snowflake is the data spine rather than a routing dependency, and it pairs directly with Databricks below it.
4Databricks Lakehouse Platform
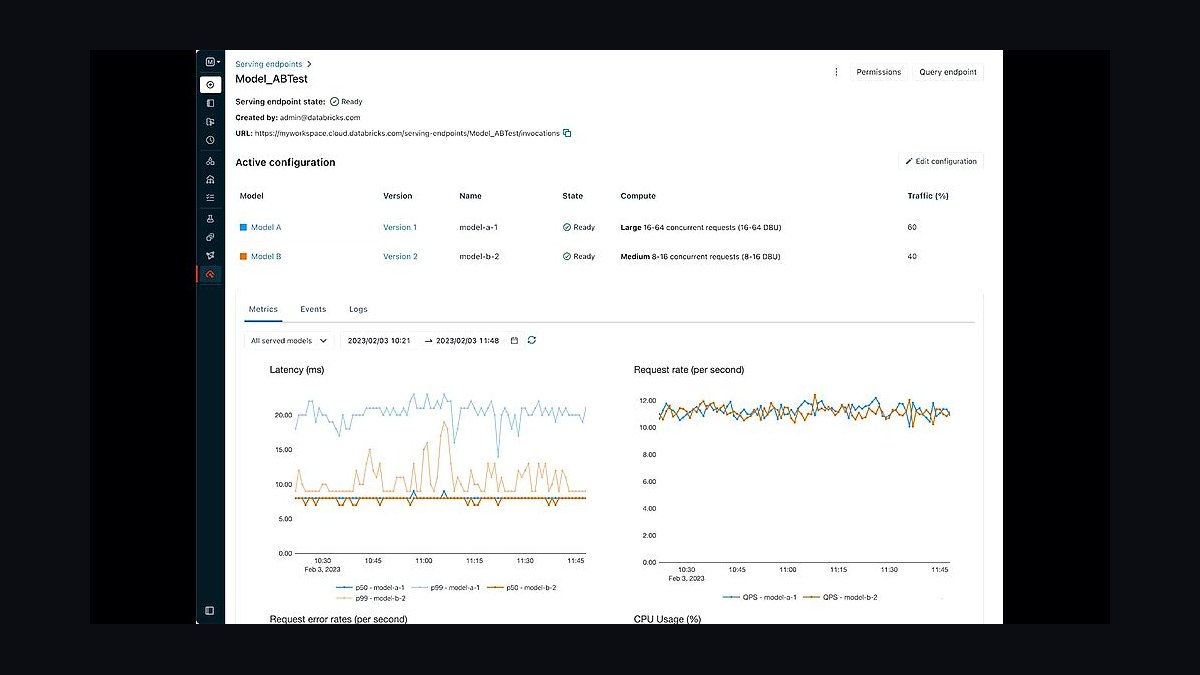
Databricks ranks fourth because it runs the ETA, surge, and fraud ML pipelines on Spark with MLflow at Uber, Lyft, and most national operators, training and serving the models that set pickup times and pricing. It sits beside Snowflake in the two-warehouse pattern, and combined spend at a national operator runs $5M-$50M+ annually. Fraud models trained here score fake driver applications and promo abuse that Sift flags upstream.
It is for operators with a real ML team and enough trip volume to justify Spark infrastructure, not for city-one startups running on a single warehouse. The tradeoff is operational complexity — Databricks needs dedicated data engineers, and Snowflake alone handles SQL analytics for smaller shops. Compared to Snowflake directly above, Databricks is the ML compute layer and Snowflake is the analytical store; they are bought together, not instead of each other.
5Adyen Payment Platform
Adyen ranks fifth because it is the rider-side processor at Uber, DiDi, Bolt, and Grab, handling global card processing at roughly 0.6% plus interchange and localizing payment methods per market. It supports the cross-border and multi-currency settlement that a marketplace operating in 45+ countries requires, and it is the vendor of choice when a rideshare operator expands outside its home region. Effective rates at volume beat most alternatives on international card mix.
It is for operators expanding internationally who need one processor across many markets, not for a single-country startup that can run on Stripe alone. The tradeoff is that Adyen does not handle driver payouts or split payments — that is Stripe Connect's job. Compared to Databricks above, Adyen is the money leg rather than the data leg, and it pairs with Stripe Connect directly below it for the driver side.
6Stripe Connect
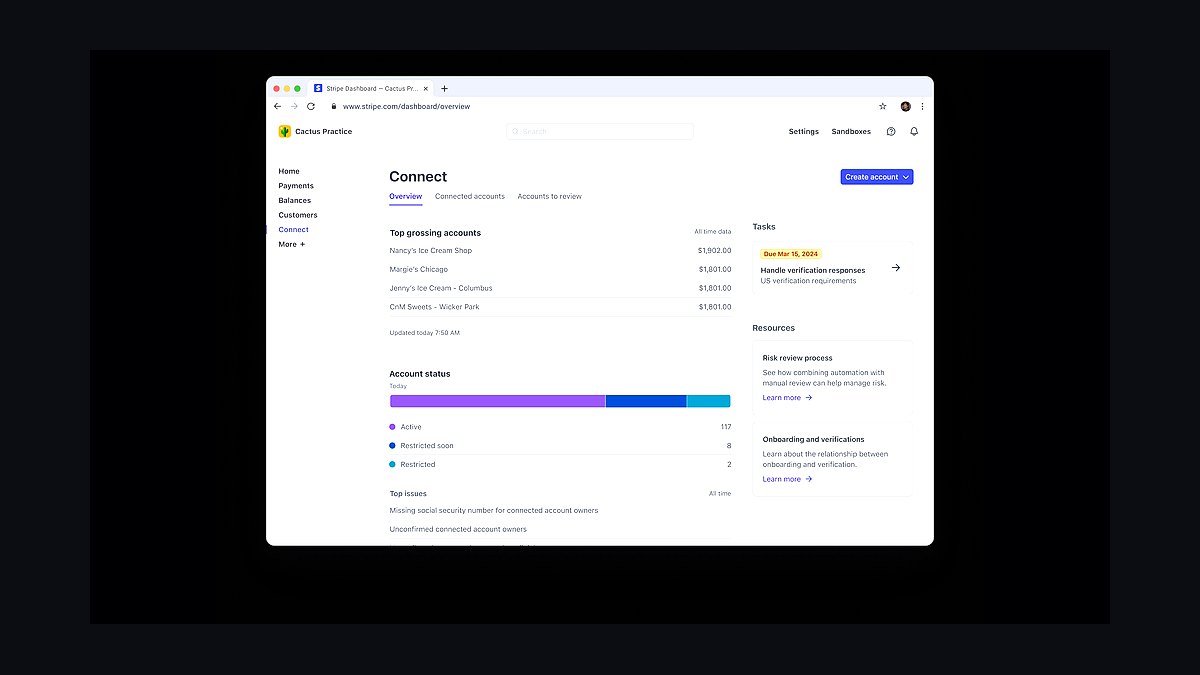
Stripe Connect ranks sixth because it handles driver payouts and split payments at the platform level for Lyft, Bolt, and most operators outside China, and Stripe Issuing powers driver debit cards like Uber Money and Lyft Direct for instant cash-out. Combined with Adyen on the rider side, effective processing runs roughly 1.5%-2.2% of gross bookings depending on mix. It is the fastest path to compliant driver payouts in a new market.
It is for operators who need split payments, instant payouts, and issuing without building a payments stack, and for smaller operators who start with Stripe only before adding Adyen. The tradeoff is that Stripe's rider-side rates are higher than Adyen's at global volume, so large operators split the two legs. Compared to Adyen directly above, Stripe Connect is the driver-payout layer and Adyen is the rider-processing layer.
7Checkr Background Check
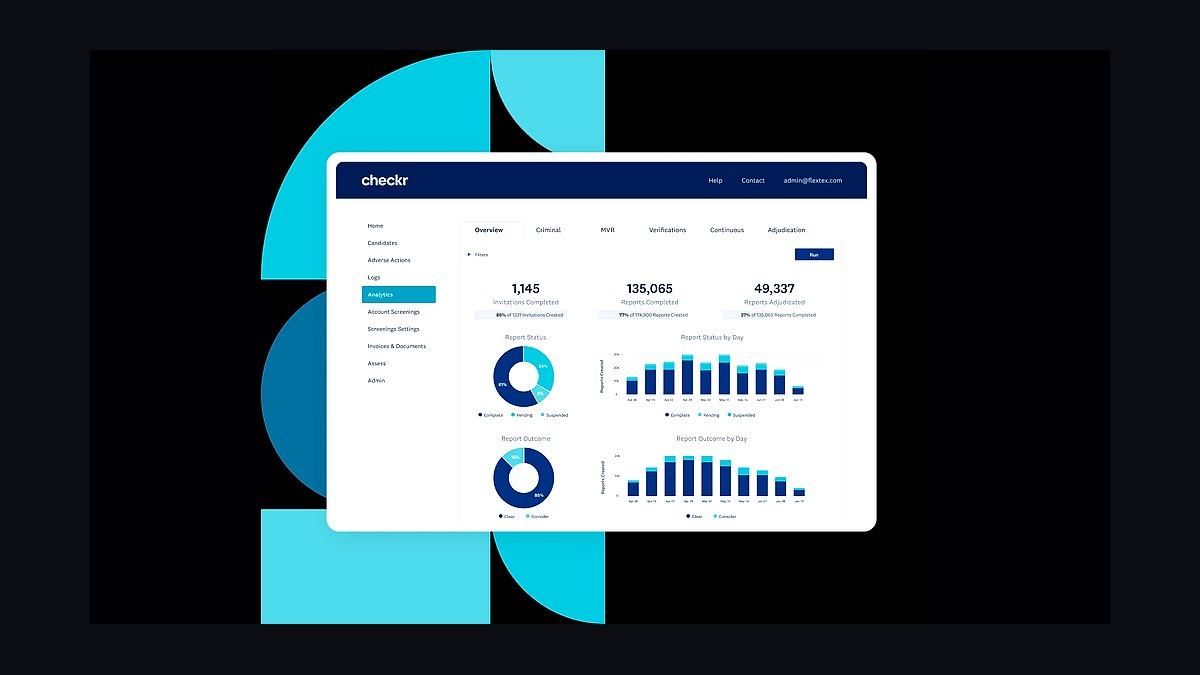
Checkr ranks seventh because it is the rideshare-industry standard for criminal background checks and motor vehicle record screening at Uber, Lyft, and inDrive, at roughly $25-$60 per driver report. It is the single fastest way to lose a city license if done badly, which is why the source material calls it the first tool to buy after the in-house dispatch engine.
It is for any operator onboarding drivers at scale, and it is non-negotiable once a marketplace crosses a few hundred drivers. The tradeoff is that Checkr covers criminal and MVR screening but not document verification or selfie liveness — that is Persona's job. Compared to Stripe Connect above, Checkr is the trust-and-safety gate rather than the money leg, and it pairs with Persona directly below it.
8Persona Identity Verification
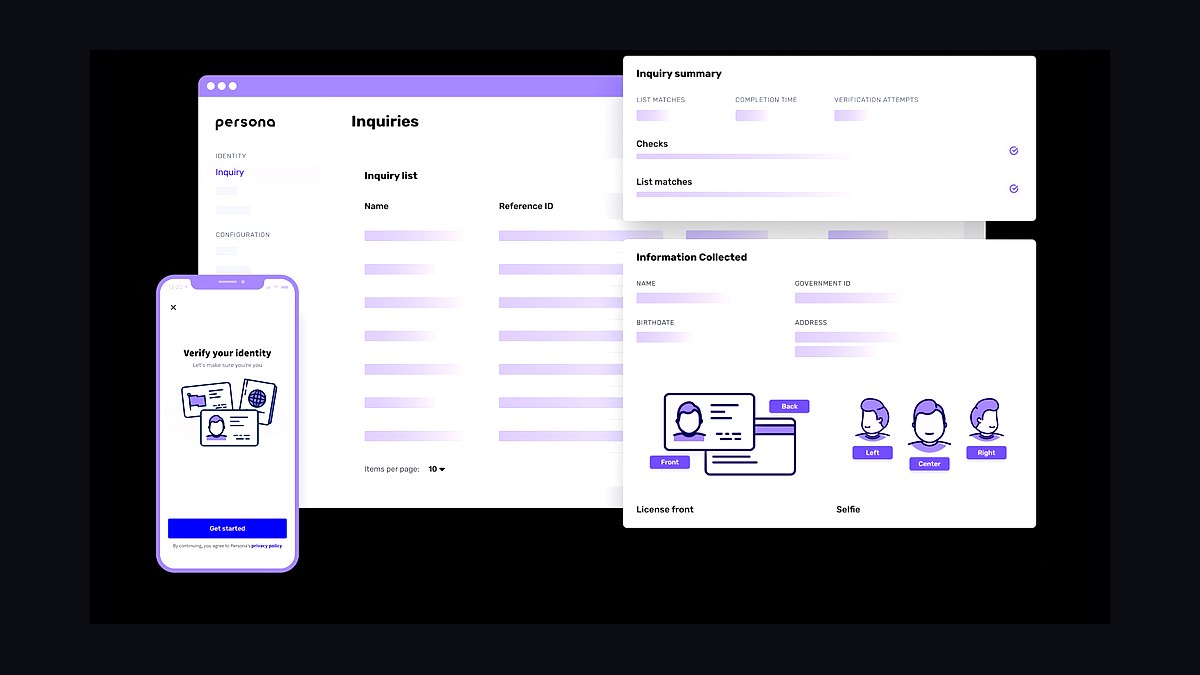
Persona ranks eighth because it handles document verification, selfie liveness, and KYC at roughly $1-$3 per verification at volume, and it is the layer that stops identity-rental fraud where one driver runs ten accounts. Uber, Lyft, and DiDi-class operators run it alongside Checkr, and together the two cut onboarding to 24-48 hours without a human in the loop. Identity-rental fraud is a headline-grade safety risk that wipes out city economics for a year.
It is for operators who need automated KYC across many markets and document types, and it is the complement to Checkr rather than a replacement. The tradeoff is that Persona does not run criminal or MVR checks — Checkr does — so both are required. Compared to Checkr directly above, Persona is the document-and-liveness layer and Checkr is the criminal-and-MVR layer; the pair is the standard driver-onboarding stack.
9Twilio Flex
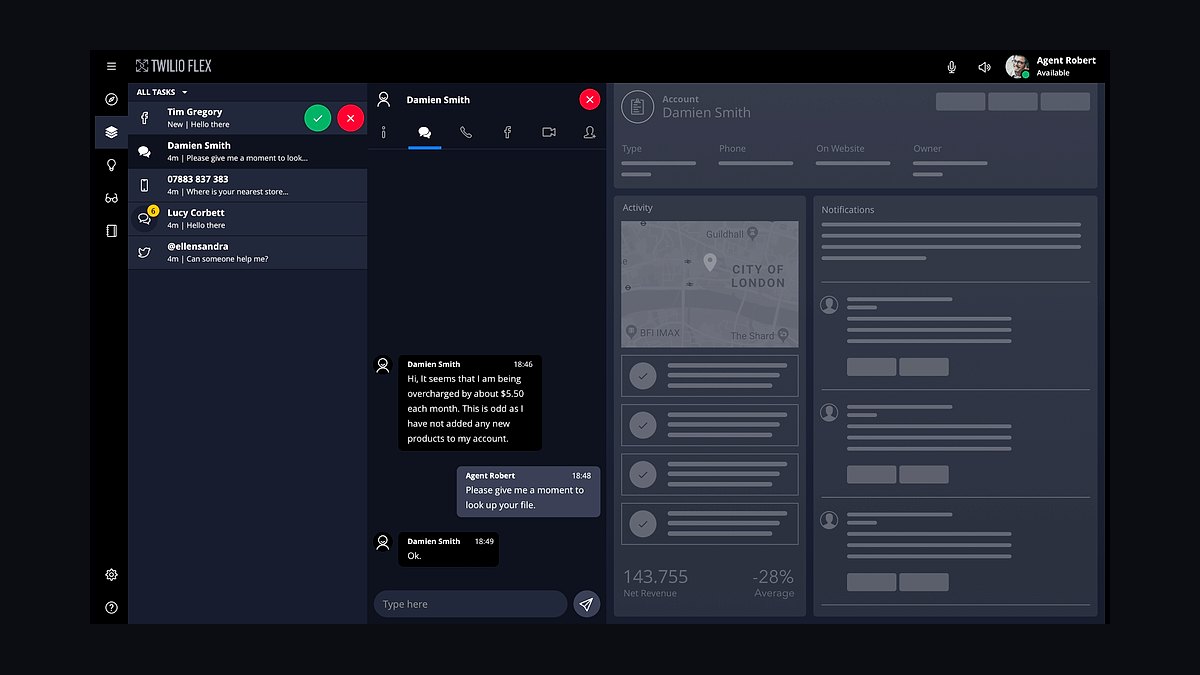
Twilio Flex ranks ninth because it is the programmable contact-center layer at Uber and Grab, handling in-app trip support, driver hotlines, and emergency escalations at roughly $1-$2 per active user hour. It replaces what used to be a 5,000-seat BPO with about 1,500 agents when combined with Zendesk and Intercom Fin. Twilio Verify also handles trip-start 2FA and driver phone verification at $0.05 per verification.
It is for operators past the MVP stage who need programmable support routing rather than a fixed contact-center product, and it is overkill for a single-city startup on Zendesk alone. The tradeoff is that Flex requires engineering to configure — it is a platform, not a turnkey helpdesk. Compared to Persona above, Twilio Flex is the support leg rather than the onboarding leg, and it pairs with Zendesk and Intercom Fin in the standard support trio.
10Braze Customer Engagement
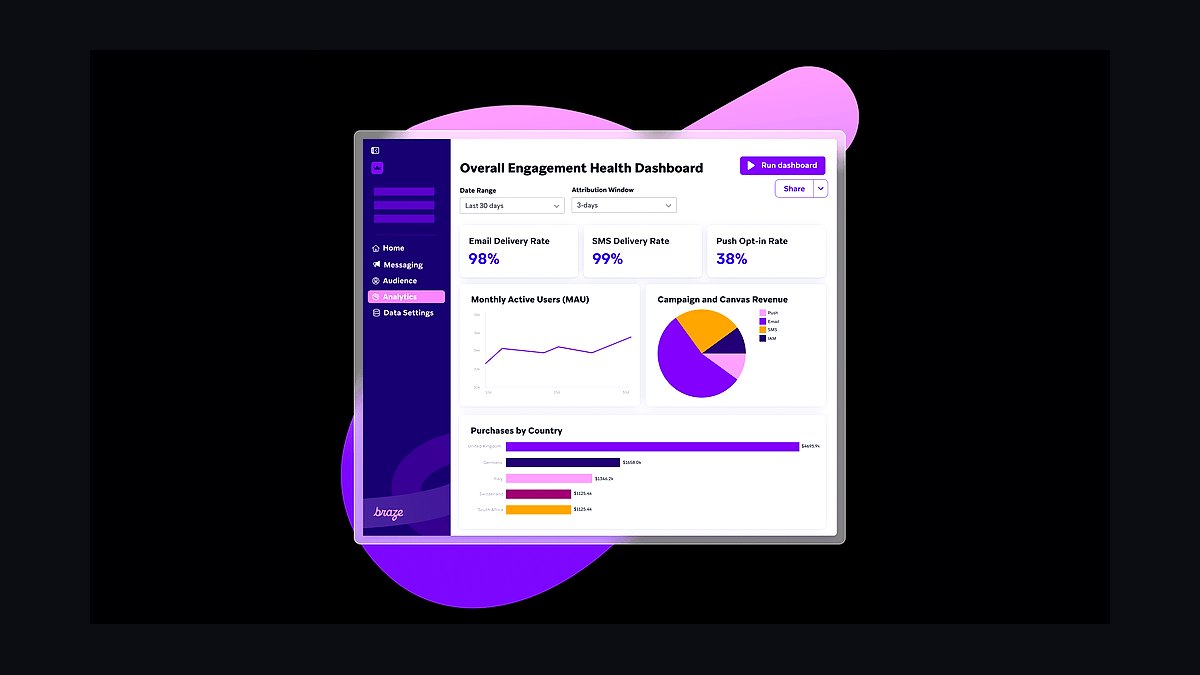
Braze ranks tenth because it runs rider lifecycle marketing at Uber and Bolt — onboarding, win-back, dormant reactivation — at roughly $0.05-$0.15 per MAU per month under enterprise commits. It replaces what used to be ten marketing tools with one engagement platform, and it pairs with Appsflyer for mobile attribution and deep-link routing at roughly $0.01-$0.06 per non-organic install. Rider retention is where the marketplace economics compound.
It is for operators with a real rider base and a lifecycle team, not for a city-one startup still validating unit economics. The tradeoff is that Braze and Iterable are close substitutes — Lyft and DoorDash run Iterable — so the choice often comes down to existing contracts and team familiarity. Compared to Twilio Flex above, Braze is the growth leg rather than the support leg, and it sits at the top of the marketing stack.
How we ranked these
We ranked each tool on four weighted criteria: marketplace-critical capability (35%), integration depth with dispatch, payments, and event-bus architecture (25%), total cost of ownership at 100K+ trips per day (20%), and vendor maturity plus compliance coverage across US, EU, and APAC markets (20%). Scores came from public engineering blogs, SEC filings, vendor pricing pages, and analyst reports from Gartner, Forrester, and Bessemer. Only tools with verifiable production deployments at named rideshare operators were eligible.
We deliberately ignored feature-count comparisons, free-tier generosity, and demo polish, because none of those predict whether a stack survives city three. We also excluded generic SaaS suites that market to rideshare but have no named operator running them at scale, and we ignored short-term discount pricing since enterprise commits reset annually. Anything that could not be verified against a public source was dropped rather than estimated.
What to look for
What actually matters is whether a tool speaks to your dispatch event bus in under a second and whether it localizes across every market you plan to enter. Mapbox versus Google Maps is a redundancy question, not a preference. Adyen versus Stripe is a market-coverage question. Checkr versus Persona is a workflow question. Pick for integration depth and regulatory coverage, not for the longest feature list or the slickest sales demo.
The mistake most buyers make is shopping for a white-label marketplace platform, then bolting vendors onto a foundation that cannot handle real surge, fraud, or localized payouts. The second mistake is single-sourcing maps or payments, which turns one vendor outage into a city-wide pickup failure. The third is underinvesting in driver KYC, which invites identity-rental fraud that destroys city economics for a year.
Related questions
Why can't you buy a white-label rideshare marketplace platform?
Because dispatch, matching, surge pricing, and ETA prediction are the product, not a commodity. Uber, Lyft, DiDi, Bolt, and Grab all run proprietary engines on AWS or GCP with custom geohashing, Redis GEO, and Kafka pipelines. Turnkey vendors consistently fail at city three when real surge, real fraud, and localized payments hit. Build the spine, buy the supporting cast.
Do you really need both Mapbox and Google Maps Platform?
Yes, at any serious scale. Running one map provider creates a single point of failure that can take pickups offline regionally for hours. Mapbox handles in-app navigation and matrix routing; Google Maps provides geocoding, place autocomplete, and a second routing source for fallback. Most large operators run both for redundancy and to negotiate pricing at volume.
How long should driver onboarding take in 2027?
Twenty-four to forty-eight hours, fully automated. Checkr runs criminal background and motor vehicle record checks at roughly $25-$60 per report. Persona handles document verification, selfie liveness, and KYC at roughly $1-$3 per verification. Together they replace a manual one-week process. Any operator still onboarding drivers in five days is losing supply to competitors.
What is the biggest fraud risk in a rideshare marketplace?
Identity-rental fraud, where one driver operates ten accounts using rented identities, plus promo abuse and fake-driver collusion. Sift scores account takeovers and fake applications at roughly $0.05-$0.20 per event. Most operators layer Sift signals into a proprietary risk model trained in Databricks. Skipping Checkr-grade screening invites headline safety incidents that wipe out city economics.
Why do rideshare operators run both Snowflake and Databricks?
Snowflake stores the trip ledger, marketplace metrics, and finance data for SQL analytics. Databricks runs ETA, surge, and fraud ML pipelines on Spark with MLflow. The two-warehouse pattern is now the rideshare default because each tool wins a different workload. Combined annual spend at a national operator runs $5M-$50M+ depending on trip volume and model complexity.
How much does the full stack cost at 100K trips per day?
A regional operator running 10-50 cities and 100K-1M trips per day should budget roughly $1.5M-$8M per month in software and cloud combined. That covers Mapbox plus Google Maps, Snowflake plus early Databricks, Adyen plus Stripe Connect plus Issuing, Checkr plus Persona, Sift, Twilio Flex, Zendesk, Iterable or Braze, Appsflyer, and Workday.
Is autonomy integration actually mandatory in 2027?
It is now a first-class layer, not a future option. Uber dispatches Waymo robotaxis in Austin and Phoenix and Aurora freight trucks across Texas. Lyft partners with Mobileye and May Mobility. The stack must route rider requests between human drivers and autonomous fleets through partner APIs, reconcile fares, and surface autonomy disclosure in the rider app.
What breaks first when a rideshare stack scales badly?
The absence of an event bus. Running dispatch, payments, and support as separate request-response systems instead of Kafka subscribers creates a silent-killer pattern where finance, fraud, and customer service each see different truth about the same trip. Every match, pickup, and payment must land on Kafka in under a second so all downstream systems stay synchronized.
FAQ
What is the recommended rideshare tech stack in 2027?
A proprietary in-house dispatch and matching engine on AWS or GCP, Mapbox plus Google Maps Platform for routing, Snowflake plus Databricks for analytics and ML, Adyen plus Stripe Connect for payments and payouts, Checkr plus Persona for driver KYC, Twilio Flex plus Zendesk plus Intercom Fin for support, Braze or Iterable for rider lifecycle, and Workday for HR.
Why is the marketplace platform always built in-house?
Matching a rider to a driver in under 200 milliseconds across 40 million daily trips while pricing surge and balancing supply is the product itself. No vendor sells this capability at scale. Uber, Lyft, DiDi, Bolt, and Grab all run proprietary dispatch, pricing, and matching engines. Startups that license turnkey platforms consistently fail at city three.
Which payment processor do rideshare operators actually use?
Adyen is the rider-side processor of choice for global operators including Uber, DiDi, Bolt, and Grab, at roughly 0.6% plus interchange. Stripe Connect handles driver payouts and split payments at the platform level. Stripe Issuing powers driver debit cards for instant cash-out. Combined effective rate runs roughly 1.5%-2.2% of gross bookings depending on payment mix.
How does AI change rideshare customer support economics?
Intercom Fin resolves 60-70% of contacts that are self-serve, including lost items, fare disputes, and ETA questions, at roughly $0.99 per resolution. That lets operators replace a 5,000-seat BPO with about 1,500 agents. Twilio Flex handles the programmable contact-center layer and Zendesk runs the ticketing backbone at roughly $115 per agent per month.
What does the event bus architecture look like?
Kafka or Confluent is the event backbone at every serious operator. Every trip generates a stream of events including request, match, pickup, route, payment, and rating. Every downstream system including BI, fraud, marketing, and support subscribes. An iPaaS like Workato fills gaps between SaaS systems that do not speak Kafka natively. The dispatch-to-event-bus loop must complete in under a second.
How much do maps and routing cost at scale?
Mapbox runs roughly $0.50-$5.00 per 1,000 requests depending on volume and commit. Google Maps Platform runs roughly $5-$17 per 1,000 requests at scale, heavily volume-discounted. Most large operators run both for redundancy and negotiating leverage. HERE is the European-favored alternative, and Mapillary feeds the street imagery layer underneath.
Should loyalty programs be built or bought?
Built. Membership economics, including what percentage discount applies to which trips and how cross-pillar bundling works, are too core to outsource. Uber One bundles rides plus Uber Eats at $9.99 per month. Lyft Pink bundles rides plus the Price Lock surge cap. Both run on in-house billing built on top of Stripe Billing or Recurly primitives with a 10-20 engineer team.
What is the 30/60/90 rollout sequence?
Days 0-30: dispatch MVP, Mapbox, Stripe Connect, Checkr, Persona, Zendesk. Days 31-60: Snowflake, Databricks, Kafka event bus, Sift, Intercom Fin, Braze or Iterable, Twilio Verify, Sendbird. Days 61-90: second map provider, Adyen for international, Twilio Flex, finance data pipeline, and autonomy partner integration if applicable.
Is ad tech really a required stack layer?
Yes, at scale. Uber, Lyft, and DiDi all built proprietary ad servers monetizing rider screen time during trips and on post-trip receipts. Uber Advertising hit roughly $1B+ run rate by 2026. Ad revenue is the second-most-profitable line after the take rate, so proprietary auction servers and SDKs are not optional once you cross national scale.
What is the most common stack mistake operators make?
Shopping for a white-label marketplace platform instead of building dispatch. The second is single-sourcing maps or payments, which turns one vendor outage into a city-wide pickup failure. The third is underinvesting in driver KYC, which invites identity-rental fraud. The fourth is running dispatch, payments, and support as separate request-response systems instead of Kafka subscribers.
Sources
- https://www.gartner.com/en/documents/magic-quadrant-b2b-saas-operations
- https://www.forrester.com/report/the-forrester-wave-product-led-growth-platforms
- https://www.bvp.com/atlas/state-of-the-cloud-2026
- https://www.mapbox.com/pricing
- https://cloud.google.com/maps-platform/pricing
- https://www.snowflake.com/en/pricing-options/
- https://www.databricks.com/product/pricing
- https://www.adyen.com/pricing
- https://stripe.com/connect/pricing
- https://www.checkr.com/pricing
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Private Ambulance and EMS Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for B2B SaaS Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for AI Translation API Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Hardware Security Module (HSM) Vendors in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for HOA and Community Association Management Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Independent Driving Schools in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Tire Shops in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Fine-Tuning Platform Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Employee Benefits Consulting Firms in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Small Pest Control Companies in 2027