


Top 10 Best Tech Stack Tools for Telecom Companies in 2027
Quality
Certified
The 10 best tech stack tools for telecom companies are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Amdocs BSS/OSS Suite
Amdocs ranks first because it is the most widely deployed end-to-end telecom BSS/OSS platform, covering billing, rating, CRM, and provisioning in one vendor relationship. It supports real-time charging and 5G monetization use cases, and its API-first modules let carriers integrate third-party analytics without replacing the core. For mid-sized carriers, Amdocs implementations commonly run 12-18 months to full cutover.
Amdocs suits carriers above roughly 200,000 subscribers that need proven scale and regulatory tax handling across multiple jurisdictions. It trades away flexibility: customizing a module often requires Amdocs professional services at their rate and timeline, which is the lock-in risk the source material names. Compared with Netcracker directly below, Amdocs has broader tier-1 references but a heavier services dependency.
2Netcracker Digital BSS/OSS
Netcracker ranks second on the strength of its cloud-native, microservices-based BSS/OSS stack, which the source material names alongside Amdocs as a leading specialist. It emphasizes open APIs and modular deployment, letting a carrier adopt billing or provisioning separately rather than committing to the whole suite at once. That modularity reduces the big-bang cutover risk the source flags as the top failure mode.
Netcracker fits regional carriers and MVNOs in the 20,000-200,000 subscriber band that want tier-1-grade software without a full suite contract. It trades away some of Amdocs's breadth in legacy integration tooling. Against CSG below, Netcracker leans more cloud-native and greenfield-friendly, while CSG has deeper roots in revenue management and wholesale settlement.
3CSG Revenue Management
CSG ranks third for revenue management and billing, a category where the source material lists it among the established BSS/OSS specialists. Its strengths are rating, invoicing, and revenue assurance, including the usage-to-billing reconciliation that the source says cuts revenue leakage into the low single-digit percentage of revenue. That makes it a direct answer to telecom's most-cited financial problem.
CSG suits carriers with complex rating needs, particularly those carrying wholesale or interconnect traffic where settlement rules exceed what retail billing engines model. It trades away being a single-vendor answer: most deployments pair CSG with a separate CRM. Against Optiva below, CSG is broader in revenue management but less focused on cloud-native charging for smaller operators.
4Optiva BSS Platform
Optiva ranks fourth as a cloud-native BSS platform focused on charging, billing, and policy for telecom operators. The source material names it among the modern BSS/OSS vendors leading with API-first architecture rather than treating integration as a footnote. Its public-cloud deployment model targets the per-subscriber SaaS pricing that small ISPs and WISPs use instead of large upfront licenses.
Optiva fits small and mid-sized operators, including MVNOs, that want cloud billing without tier-1 implementation timelines. It trades away the deep legacy migration tooling that Amdocs and Netcracker carry, so carriers with decades of grandfathered plans should validate data mapping carefully. Against Totogi below, Optiva is the more established vendor but less aggressive on AI-native charging.
5Totogi BSS Platform
Totogi ranks fifth as the cloud-native BSS entrant the source material names alongside Matrixx among newer API-first vendors. It runs on public cloud infrastructure and prices on a per-subscriber SaaS model, which maps directly to the low-to-mid five-figure annual spend the source cites for operators under 20,000 subscribers. Its architecture assumes real-time APIs rather than nightly batch exports.
Totogi fits greenfield MVNOs and small ISPs with no legacy billing system to migrate, where its cloud-native design is an advantage rather than a constraint. It trades away the migration experience that established vendors bring, so carriers with complex grandfathered pricing should weigh that gap. Against Optiva above, Totogi is newer and smaller but more explicitly built for cloud-first operators.
6Salesforce Communications Cloud
Salesforce ranks sixth as the CRM layer, which the source material explicitly endorses for telecom businesses because it integrates via API to telecom-specific billing and provisioning systems. That integration model matters more than any single feature list, per the source's core argument. Communications Cloud adds telecom data models on top of the standard platform.
Salesforce fits operators that want a general-purpose CRM with deep customization rather than a telecom-only tool, and it pairs cleanly with the billing platforms ranked above it. It trades away telecom-specific out-of-box workflows, which require configuration. Against HubSpot below, Salesforce scales to larger subscriber bases but costs more and demands more administration.
7HubSpot CRM
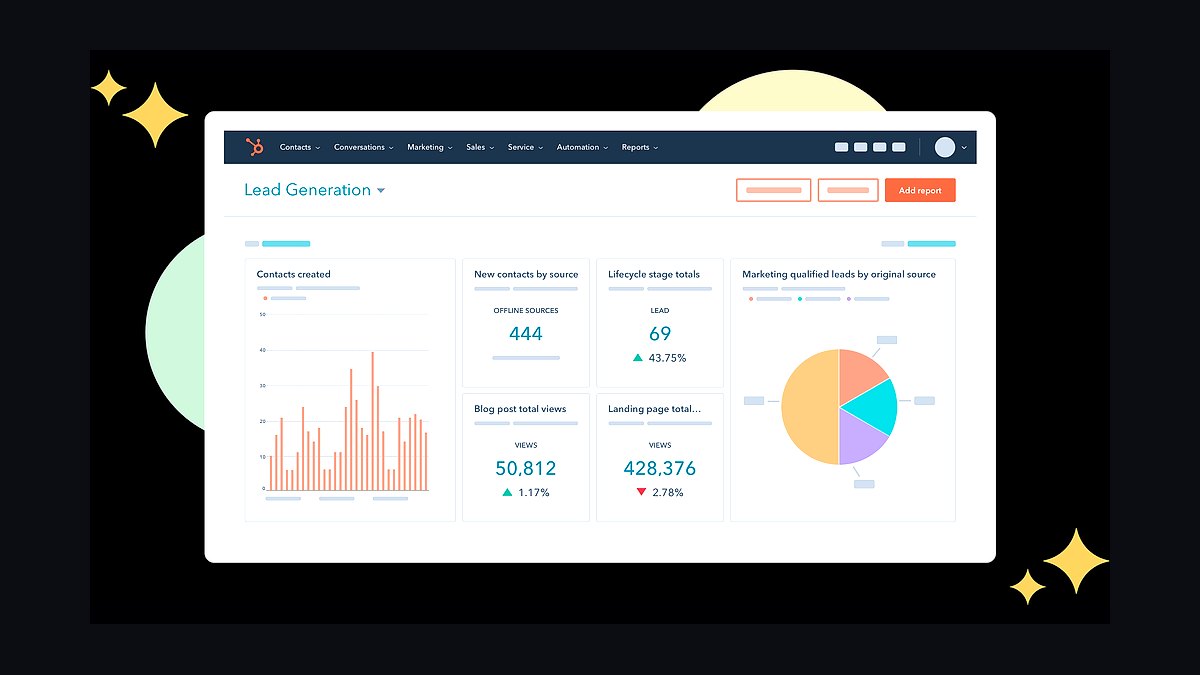
HubSpot ranks seventh as the lighter CRM option the source material names alongside Salesforce for telecom businesses. Its API-first integration to billing and provisioning systems lets a small operator avoid paying for telecom-specific CRM features it does not need, which the source calls out as a real advantage for smaller carriers. Setup is faster than enterprise CRM platforms.
HubSpot fits small ISPs and WISPs under 20,000 subscribers that need contact and account management without a dedicated CRM administrator. It trades away the deep customization and telecom data models that Salesforce Communications Cloud provides. Against Zendesk below, HubSpot covers sales and marketing while Zendesk focuses on support tickets, so many operators run both.
8Zendesk Support Suite
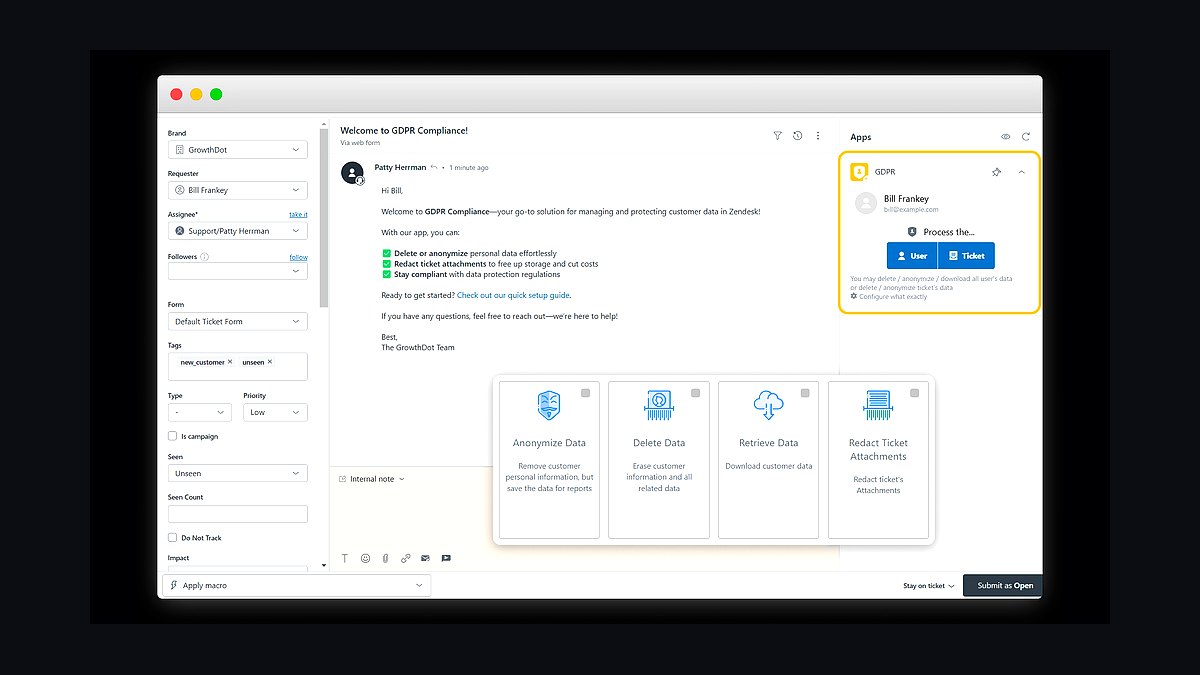
Zendesk ranks eighth as the support and ticketing layer, which the source material lists among the core stack components for telecom operators. Its value in an integrated stack is showing agents live usage, billing status, and network health on one screen instead of tabbing between a legacy billing terminal and a separate ticketing tool. That directly supports the 70-85% first-call resolution benchmark the source cites.
Zendesk fits operators that want fast agent onboarding and clean API connections to billing and CRM systems. It trades away deep telecom-specific fault management, which belongs in the network layer. Against ServiceNow below, Zendesk is simpler and cheaper to run but less suited to complex multi-team workflows.
9ServiceNow Telecom Operations
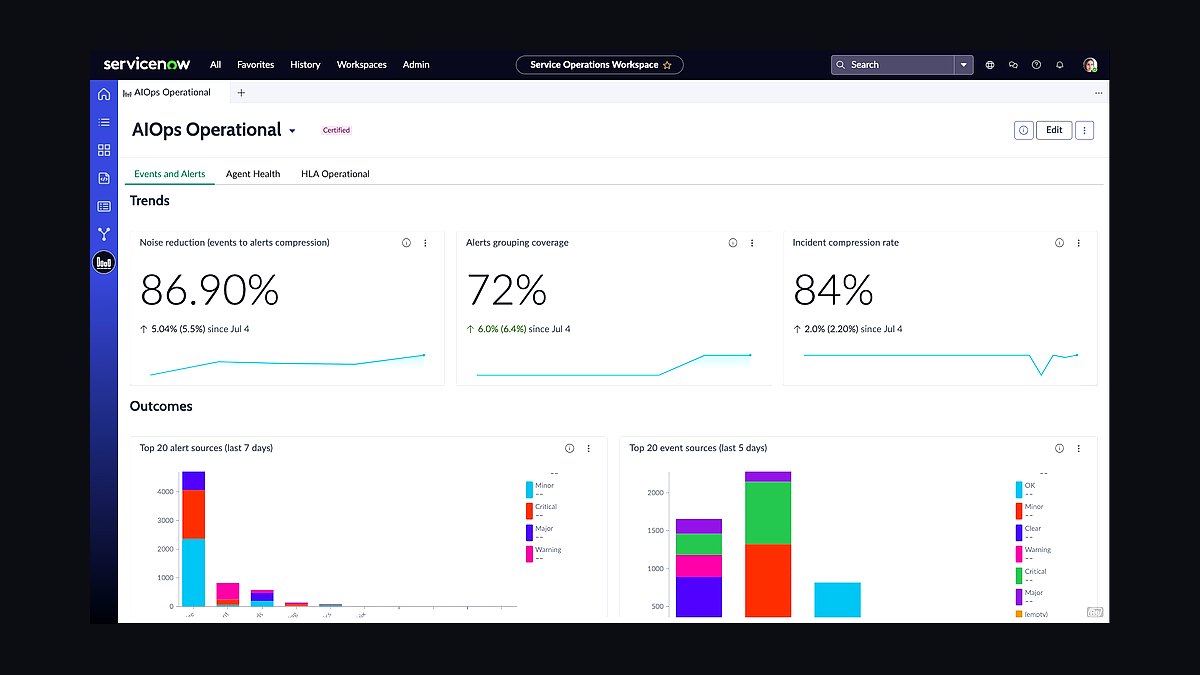
ServiceNow ranks ninth for telecom operations workflows, named in the source material's vendor list for support and ticketing. It connects ticketing to network fault management and change workflows in one platform, which matters for the alert-fatigue problem the source describes, where real outages get buried under false positives. Its workflow engine routes incidents by severity and ownership.
ServiceNow fits mid-sized carriers with multiple operations teams that need structured incident and change management, not just a support inbox. It trades away simplicity and cost: implementation and administration are heavier than Zendesk. Against Zendesk above, ServiceNow handles complex cross-team workflows better but is overkill for operators running a single support queue.
10Datadog Network Monitoring
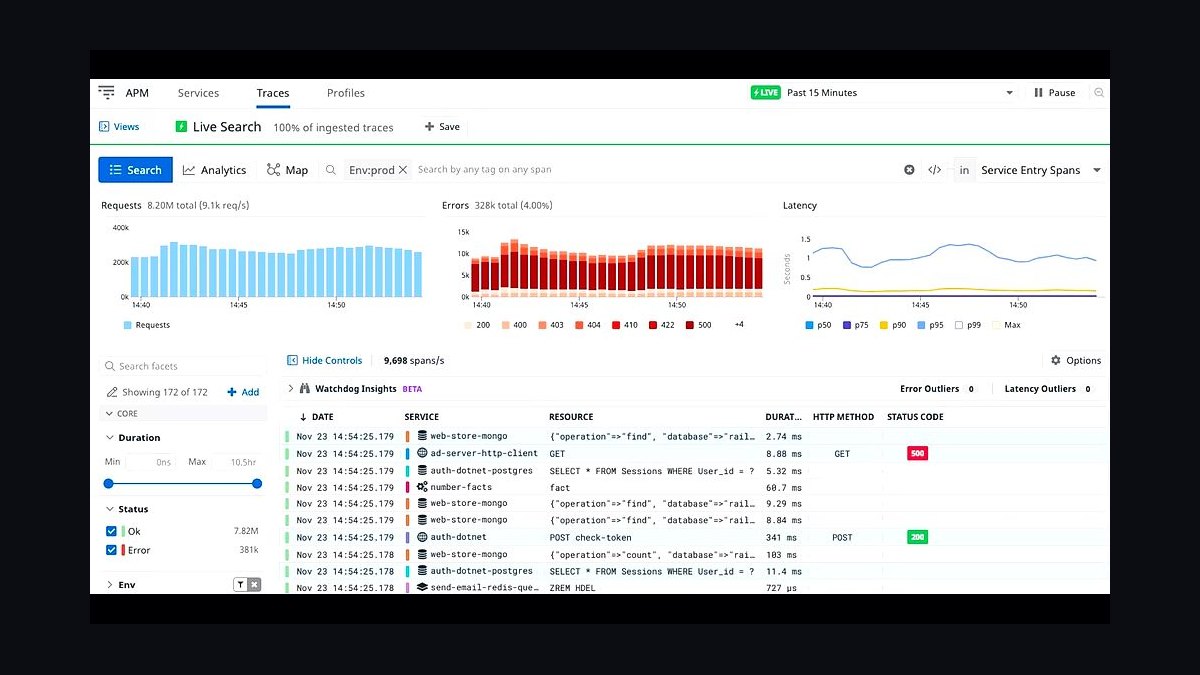
Datadog ranks tenth as the network and performance monitoring layer, the component the source material recommends rolling out first because it carries the least customer-facing risk if something goes wrong. It ingests network equipment telemetry and lets operations teams tune alert thresholds against real traffic before anything customer-facing depends on it. That tuning is the fix for the alert-fatigue failure mode the source names.
Datadog fits operators that want a mature observability platform with broad integrations rather than a telecom-only fault management tool. It trades away telecom-specific fault correlation, which specialized OSS tools handle better. Against ServiceNow above, Datadog watches the network while ServiceNow manages the incident workflow, so the two are complementary rather than competing.
How we ranked these
We ranked tools on five weighted criteria: real-time API integration depth (30%), BSS/OSS functional coverage across billing, rating, and provisioning (25%), total cost of ownership including integration labor (20%), network-layer assurance capability (15%), and compliance support for telecom taxation and CDR retention (10%). Scores came from vendor documentation, published pricing models, and operator case studies.
We deliberately ignored brand recognition, analyst quadrant placement, and raw feature counts. A platform with hundreds of features nobody uses scores no higher than a lean one. We also excluded vendor-reported uptime claims and demo-environment performance, since neither reflects production behavior under real subscriber load, mixed legacy data, or peak-hour rating traffic.
What to look for
What matters most is the integration model, not the feature list. A billing platform with a mediocre interface but an open, documented API that connects cleanly to CRM and network systems will outperform a feature-rich platform that only exports nightly CSV batches. Ask vendors to demonstrate a live API call during evaluation, not a slide.
The mistake most buyers make is choosing an all-in-one suite for convenience, then discovering that customizing any single module requires the vendor's professional services team at their timeline and rate. All-in-one reduces integration risk but trades away flexibility. Best-of-breed increases integration work but keeps your roadmap. Decide based on whether you have in-house engineering capacity.
Related questions
How much should a small telecom operator budget for software?
Plan for roughly 3-8% of revenue at steady state, with small operators often at the higher end because fixed platform fees spread across fewer subscribers. Under 20,000 subscribers, expect low-to-mid five figures annually for core billing and CRM, plus implementation costs that frequently match or exceed the first year of licensing.
Should a Telecom business build custom billing software or buy a platform?
Buying is almost always right unless the business has genuinely unusual billing logic, such as complex wholesale settlement or highly custom bundling, plus dedicated engineering capacity to maintain it. Custom billing carries ongoing compliance, taxation, and maintenance burden that most telecom operators underestimate badly.
How long does BSS/OSS migration typically take?
Six to eighteen months from vendor selection to full cutover for a mid-sized carrier. The long pole is data migration and parallel-run validation, not software configuration. Subscriber records, billing history, grandfathered plans, and active service configurations all need auditing before they map cleanly to a new data model.
What's the biggest hidden cost in a telecom software stack?
Integration and data migration, not licensing. Professional services and in-house engineering time to connect billing, CRM, and network systems often exceeds first-year software fees. Budget for at least one integration engineer and a data analyst even when buying SaaS, or the handoff points will stall.
Does a Telecom business need a separate fraud detection tool?
Yes, once past a small subscriber base. Usage-based billing and SIM or account fraud losses typically justify a dedicated fraud and revenue assurance layer separate from general analytics. It also catches revenue leakage that general reporting misses, since it reconciles network usage records against billed charges automatically.
Can a Telecom business use general-purpose CRM instead of telecom-specific CRM?
Yes, and many smaller operators do. Salesforce or HubSpot integrate well via API to telecom-specific billing and provisioning systems, and they avoid paying for telecom CRM features the business does not need. The trade-off is building those integrations yourself rather than buying them pre-built.
How important is API access when choosing telecom software?
It is often the single biggest differentiator in real-world outcomes. A billing platform with a mediocre interface but an open, documented API beats a feature-rich one that only exports nightly CSV batches. Integration model matters more than any standalone feature list during evaluation.
What role does AI play in a 2027 telecom software stack?
Mostly in customer support chat and ticket triage, network anomaly detection, and churn prediction from usage and billing data. These are incremental additions to the core stack, not replacements for billing, CRM, or provisioning systems. Treat AI features as add-ons, not selection criteria.
FAQ
What's the minimum viable software stack for a very small Telecom business?
A cloud billing and CRM combo platform, a network monitoring tool, and a support ticketing system, often three vendors instead of five to eight. That is enough to launch. Add specialized layers like fraud detection and advanced analytics only as subscriber count and revenue justify the added integration work.
Can a Telecom business use Salesforce or HubSpot instead of telecom-specific CRM?
Yes, and many do, especially smaller operators. General CRM platforms integrate well via API to telecom-specific billing and provisioning systems, and they avoid paying for telecom CRM features the business does not need. The trade-off is building and maintaining those integrations in-house.
How important is API access when choosing telecom software?
Very important. It is often the single biggest differentiator in real-world outcomes, since a stack's usefulness depends on how well its systems share data, not on any one platform's standalone feature set. A well-documented API beats a longer feature list every time.
Should legacy on-premise billing systems be replaced entirely or integrated?
It depends on age and vendor support status. A well-supported legacy system can often be integrated via middleware rather than replaced outright, which is cheaper and lower-risk than a full rip-and-replace if it still meets compliance and performance needs. Replace only when support ends.
What role does AI play in a 2027 telecom software stack?
Mostly in customer support chat and ticket triage, network anomaly detection, and churn prediction from usage and billing data. These are incremental additions to the core stack above, not replacements for billing, CRM, or provisioning systems. Treat AI as an add-on layer, not a foundation.
How does a Telecom business avoid vendor lock-in when choosing a stack?
Prioritize platforms with open, documented APIs and standard data export formats, and negotiate data portability terms into contracts upfront. Lock-in risk comes from proprietary data formats and closed integration models, not from the vendor relationship itself. Read the exit clause before signing.
What is the most common failure mode in a telecom stack replacement?
Treating it as a big bang cutover. Migrating billing, provisioning, and CRM simultaneously without a parallel-run period means any data mapping error surfaces directly in customer bills or service interruptions. That is the worst possible place to discover a bug, damaging trust and triggering regulatory exposure at once.
How do you reduce alert fatigue in network monitoring tools?
Tune thresholds after go-live against real traffic, not just before. Poorly tuned monitoring generates so many low-priority alerts that real outages get lost in noise. This is a configuration problem, not a software selection problem, but it shows up in evaluations as the tool failing to catch outages.
What compliance requirements should drive telecom software selection?
Jurisdiction-specific taxation such as USF fees, state and local telecom taxes, and E911 surcharges, plus data retention and privacy rules around call detail records and subscriber data. A system that handles one region well may need significant custom configuration elsewhere. Validate before signing, not during an audit.
Does a Telecom business need wholesale and interconnect billing capability?
Only if it carries wholesale traffic. Wholesale and interconnect billing follows settlement rules that retail billing engines often cannot model without customization. Validate that capability during vendor evaluation rather than discovering the gap after signing, when remediation means expensive professional services work on the vendor's timeline.
Sources
- https://www.tmforum.org
- https://www.gartner.com
- https://www.gsma.com
- https://www.amdocs.com
- https://www.csgi.com
- https://www.salesforce.com
- https://www.zendesk.com
- https://www.servicenow.com
- https://aws.amazon.com/telecom
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Employee Benefits Consulting Firms in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for AI Translation API Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Tree Services in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Medical Billing and RCM Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Email Security Vendors in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Private Ambulance and EMS Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Plumbing Contractors in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Threat Intelligence Vendors in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Appliance Repair Services in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Home Inspection Companies in 2027