
Top 10 Sales KPIs for Cannabis Retail Dispensary in 2027
 Curated byKory White · Fractional CRO · Maryland
 PULSEKNOWLEDGE LIBRARY
Quality
Certified
The 10 best sales kpis for cannabis retail dispensary are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1. Cannabis Retail Revenue Per Square Foot
Revenue per square foot ranks first because it is the only KPI that tests whether the dispensary box itself is productive enough to carry 280E-impaired cash flow. Strong mature-market stores clear $1,500–$2,500 per square foot annually, the broad adult-use median sits near $900–$1,500, and distressed oversupplied stores fall under $600. A high-performing conventional grocer runs roughly $1,200, so a well-run dispensary is genuinely dense retail.
It is for CFOs and real estate decision-makers weighing store buildout, relocation, or closure, not for budtenders. It trades away day-to-day actionability, since square footage changes only through remodels or lease decisions. Compared with average basket size directly below it, revenue per square foot captures traffic, ticket, and footprint together, while basket isolates the counter interaction alone.
2. Cannabis Dispensary Average Basket Size
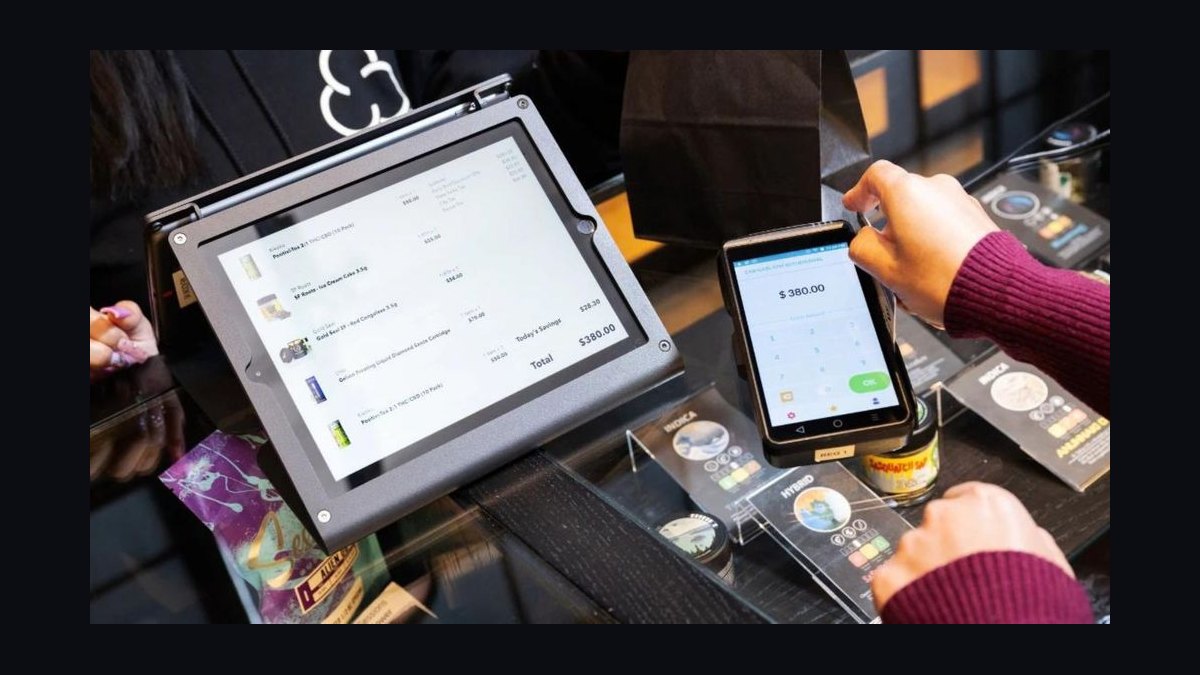
Average basket size ranks second because it is the fastest-moving revenue lever a store manager can actually steer tomorrow through attach rate and merchandising. National adult-use baskets generally sit in the $40–$60 range, medical baskets run 25–35% higher on larger authorized quantities, premium urban stores clear $80, and value markets run $30–$40 at several times the transaction count. It must be reported net of discount.
It is for store managers and merchandising leads optimizing menu layout and budtender scripts. It trades away traffic context, so a rising basket can mask falling customer count. Compared with revenue per square foot above it, basket is narrower and more actionable; compared with customer count below it, basket measures depth while count measures breadth.
3. Cannabis Dispensary Daily Customer Count
Daily customer count ranks third because it moves before revenue does, making it the cleanest early-warning metric on the dispensary scorecard. Healthy adult-use stores commonly run 250–400 transactions daily, high-volume value markets exceed 600, and limited-license medical stores run 120–200 on much larger tickets. Paired with staffing hours it produces transactions per labor hour.
It is for general managers diagnosing whether a queue problem is demand or scheduling. It trades away basket and margin context, so promotions inflate it while quietly eroding net basket and repeat rate. Compared with average basket size above it, customer count is the breadth half of the revenue equation; compared with repeat-customer rate below it, count measures today while repeat rate measures durability.
4. Cannabis Dispensary Repeat Customer Rate
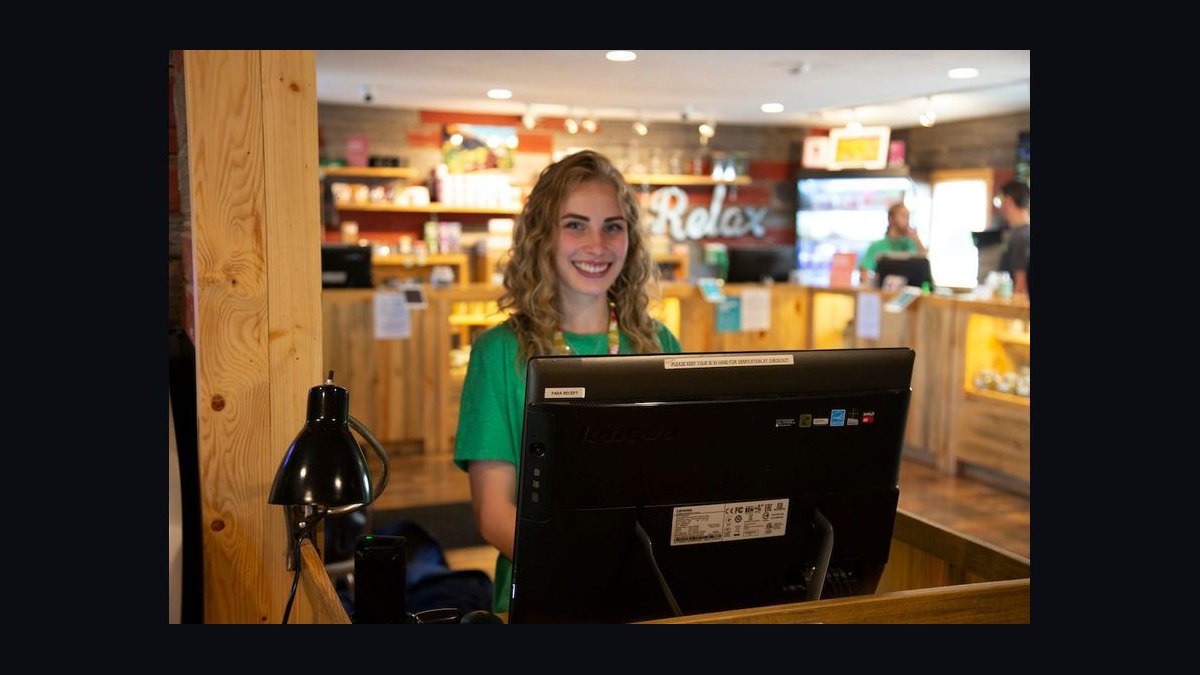
Repeat-customer rate ranks fourth because it degrades before revenue does and is the single best early predictor of dispensary failure. Cannabis is a habitual-purchase category, and mature stores routinely see 65–75% of revenue from identified returning customers; below 50% signals a discount-driven or tourist base, and 60% is the durable-economics floor. It typically shows up first as elevated first-visit share on promotional days.
It is for operators deciding whether a growth strategy is building a franchise or renting one. It trades away immediacy, since a base shifting toward deal-seekers still produces acceptable weekly sales for a quarter or two. Compared with daily customer count above it, repeat rate measures quality of traffic rather than volume; compared with category mix below it, repeat rate is about who returns, not what they buy.
5. Cannabis Dispensary Product Category Mix
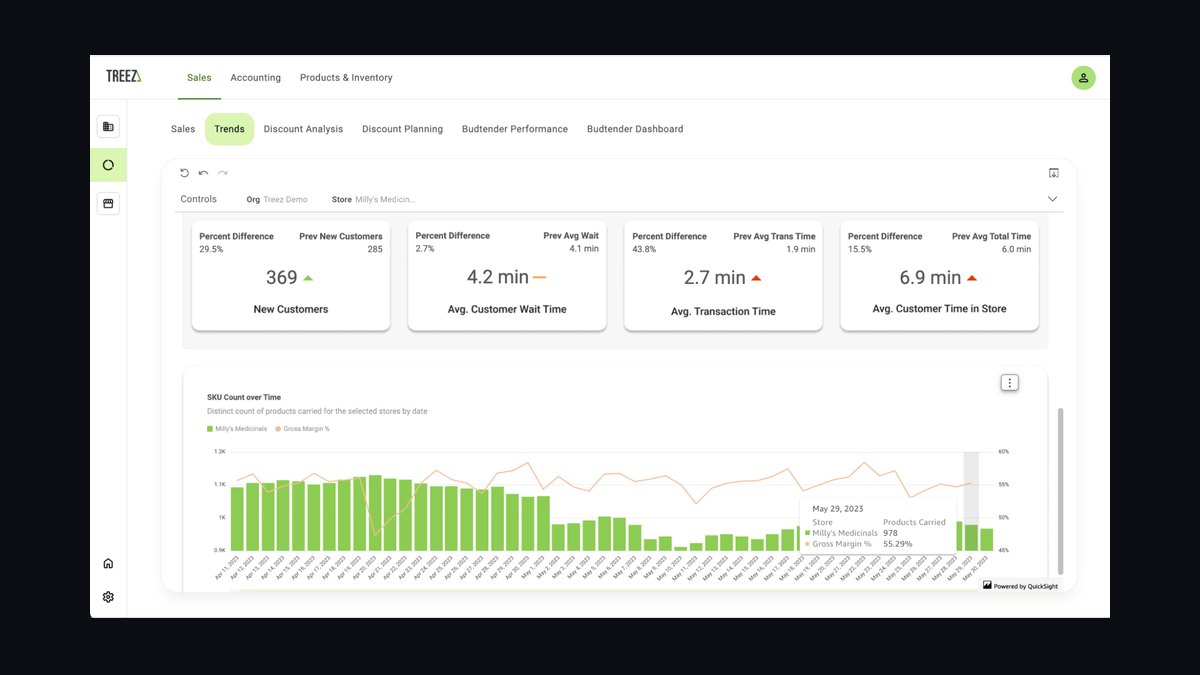
Product-category mix ranks fifth because blended margin in a dispensary is mostly a mix outcome, not a pricing outcome. Industry tracking consistently shows flower as the largest share at roughly 40%, vape near the mid-20s, edibles in the mid-teens, and pre-rolls in the low-to-mid teens and rising. Flower share drifts down a point or two yearly while pre-rolls and edibles take share with better attach rates.
It is for merchandising and buying teams steering shelf allocation and menu placement. It trades away simplicity, since mix requires clean POS category tagging across every SKU. Compared with repeat-customer rate above it, category mix is about what returning customers purchase; compared with house-brand penetration below it, mix measures the whole shelf while penetration measures only owned SKUs.
6. Cannabis Dispensary House Brand Penetration
House-brand penetration ranks sixth because owned SKUs carry meaningfully higher gross margin than comparable third-party products, commonly eight to fifteen percentage points, and internally produced inventory pushes more cost into the only deductible category under 280E. Vertically integrated operators target 40–55%, leading MSOs report owned-brand mix near half of retail revenue, and sustained penetration below 30% signals a failing wholesale strategy on the easiest shelf in the country.
It is for vertically integrated operators who built cultivation and manufacturing capacity and must justify it at retail. It trades away relevance for third-party-only retailers who have no owned brands to push. Compared with product-category mix above it, house-brand penetration is a subset of shelf strategy; compared with gross margin below it, penetration is a controllable input while margin is the resulting output.
7. Cannabis Dispensary Gross Margin
Gross margin ranks seventh because it converts traffic and mix into actual dollars, though management steers it indirectly through mix and house-brand share rather than through price. Top public operators generally run 45–58% blended depending on state mix and integration depth, with flower typically the thinnest category, vape and concentrates the richest, and edibles in between. The low end reflects third-party-heavy sourcing in compressed markets.
It is for finance leaders judging whether store-level performance survives state wholesale deflation. It trades away direct actionability, since cutting flower price to defend share moves the thinnest category and rarely recovers on volume. Compared with house-brand penetration above it, margin is the outcome rather than the lever; compared with compliance audit pass rate below it, margin is economic while compliance is existential.
8. Cannabis Dispensary Compliance Audit Pass Rate
Compliance audit pass rate ranks eighth because it is a veto rather than a step in the sequence, covering seed-to-sale reconciliation, security and video retention, ID verification, packaging, and inventory variance. Anything under 95% is an existential exposure, and serious operators target 100% with every finding closed inside the state's cure window. Inventory variance percentage and open findings by age are the leading indicators.
It is for store managers and compliance officers whose compensation should be tied to results. It trades away revenue upside entirely, since a 30-day suspension deletes a month of contribution from an asset still owing rent and debt service. Compared with gross margin above it, compliance outranks every revenue metric when failing; compared with effective 280E tax burden below it, compliance protects the license while 280E determines what the license earns.
9. Cannabis Dispensary 280E Tax Burden
Effective 280E tax burden ranks ninth because it determines whether retail performance converts to cash, with operator ranges running roughly 65% to above 90% of pre-tax book income. IRC Section 280E bars plant-touching businesses from deducting rent, marketing, salaries, utilities, and most G&A federally, leaving only Cost of Goods Sold deductible. Public filers from Trulieve to Green Thumb to Curaleaf have disclosed large 280E liabilities.
It is for CFOs and tax teams modeling store-level viability and COGS allocation defensibility. It trades away operational immediacy, since the number moves mainly through accounting treatment rather than store behavior. Compared with compliance audit pass rate above it, 280E is a cash-conversion metric rather than a license-risk metric; compared with state-by-state P&L segmentation below it, 280E is the federal overlay that reshapes every state result.
10. Cannabis Dispensary State License Segmentation
State license segmentation ranks tenth because every other KPI on this page is meaningless without it, yet it is a reporting discipline rather than a single number. Florida caps stores per license under a historically medical-only vertically integrated model, Massachusetts caps stores per operator, and Colorado and Oklahoma ran effectively uncapped, producing multi-year price deflation. Michigan wholesale flower collapsed from roughly $3,200 per pound in 2022 to well under $1,000 by 2025.
It is for multi-state operators and boards reviewing portfolio concentration and store rankings. It trades away simplicity, since national averages must be abandoned and every metric reported within state and license class first. Compared with effective 280E tax burden above it, segmentation is the structural context that makes 280E modeling accurate per jurisdiction rather than blended into a number no operator can act on.
How we ranked these
We ranked the nine cannabis retail sales KPIs by how directly each one moves cash in a 280E-constrained dispensary, weighting revenue per square foot, basket size, traffic, repeat rate, category mix, house-brand penetration, gross margin, compliance pass rate, and effective 280E burden. Weighting favored metrics with clear owners, weekly actionability, and measurable dollar impact inside a single state and license class.
We deliberately ignored national averages, cross-state basket comparisons, and vanity metrics like total loyalty signups or social reach. Those blend incompatible license structures and price regimes, producing numbers no operator can act on. We also excluded pre-tax contribution margin, because 280E makes pre-tax store economics flattering and misleading when judging whether a marginal location is actually cash-positive.
What to look for
When choosing between these KPIs, prioritize the ones tied to your binding constraint. A traffic-starved store needs customer count and queue-time data before basket work; a vertically integrated operator needs house-brand penetration and COGS allocation depth; a limited-license medical store should weight basket and repeat rate over raw traffic. Match the metric set to your license class and integration model, not to a generic retail template.
The mistake most buyers make is purchasing a dashboard that reports every metric at national rollup, then discovering the numbers cannot be segmented by state, license class, or store. Insist on state-level segmentation, written definitions for sellable square footage and transaction counts, and a COGS allocation model that ties to the 280E exposure calculation. Without those, the scorecard looks complete but drives no decisions.
Related questions
What is a good revenue per square foot for a dispensary?
Strong mature-market stores clear $1,500 per square foot annually, the broad adult-use median sits near $900–$1,500, and distressed stores in oversupplied markets fall under $600. Limited-license medical footprints can exceed the top of that band on patient lock-in. Always confirm whether sellable square footage excludes vault, intake, and secure storage before comparing stores.
How do I calculate average basket size correctly?
Divide net revenue by transaction count, then compute it again before discount so promotional erosion is visible. Segment by daypart, medical versus adult-use, and new versus returning customer. National adult-use baskets generally run $40–$60, medical runs 25–35% higher in the same state, and premium urban stores clear $80 while value markets sit at $30–$40.
Why does repeat-customer rate matter more than traffic?
Repeat rate degrades before revenue does. A base shifting toward discount-driven first-time buyers still produces acceptable weekly sales for a quarter or two before margin damage shows in the P&L. Mature stores see 65–75% of revenue from repeats; below 50% signals a tourist or deal-seeking base that will not survive a price increase.
What house-brand penetration should a vertically integrated dispensary target?
Vertically integrated operators commonly target 40–55% of retail revenue from owned brands, and leading MSOs have reported owned-brand mix near half of retail sales. Sustained penetration below 30% means the wholesale strategy is failing on the easiest shelf in the country to win. Owned brands typically carry eight to fifteen percentage points more gross margin than comparable third-party SKUs.
How does 280E change which KPIs matter?
Because plant-touching businesses cannot deduct ordinary operating expenses, only COGS qualifies against federal taxable income, pushing effective rates to roughly 65–95% of pre-tax book income. Every operating decision routes through whether a cost can be legitimately allocated into COGS. That makes COGS allocation depth, gross margin, and effective 280E burden core operating metrics rather than tax-footnote items.
What compliance pass rate is acceptable for a dispensary?
95% is the floor, not the goal. The target is 100% with every finding closed inside the state's cure window. A seed-to-sale reconciliation gap, video retention lapse, underage ID failure, or inventory variance can trigger fines, suspension, or license revocation. A 30-day suspension deletes a month of contribution from an asset that still owes rent and debt service.
How long does it take to instrument this scorecard?
A realistic build runs about 90 days for a single-state operator with a clean POS deployment, and closer to two quarters for a multi-state operator running mixed POS and seed-to-sale platforms. The first 30 days go almost entirely to reconciliation. The slow part is agreeing on definitions across store operations, finance, and compliance, each of whom already trusts a different number.
Should basket size be compared across states?
No. A $35 basket in Michigan can be a healthy store while a $90 basket in a Florida medical location is unremarkable. License caps, medical versus adult-use structure, and wholesale price deflation differ so widely that benchmarks are only meaningful inside a state and license class. Any dashboard averaging basket size nationally produces a number no operator can act on.
FAQ
What are the most important sales KPIs for a cannabis dispensary in 2027?
Nine metrics anchor the scorecard: revenue per square foot, average basket size, daily customer count, repeat-customer rate, category mix, house-brand penetration, gross margin, compliance audit pass rate, and effective 280E tax burden. Together they show whether traffic, ticket, mix, and margin survive federal taxation. Compliance acts as a veto because a suspended license makes every other metric moot.
How often should a dispensary review these KPIs?
Daily for transactions, basket, discount rate, and seed-to-sale sync status. Weekly for revenue per square foot, category mix, house-brand penetration, and repeat rate. Monthly for margin by category, promotional lift, and audit findings. Quarterly for state-by-state P&L, the refreshed 280E exposure model, and store-level CapEx or closure decisions. Each layer has a different owner and action threshold.
Which single metric predicts dispensary failure earliest?
Repeat-customer rate. It degrades before revenue does, because a base shifting toward discount-driven first-time buyers still produces acceptable weekly sales for a quarter or two before margin damage becomes visible. Below 50% repeat revenue usually signals a tourist or promotional base that will not survive a price increase, and it typically shows first as heavy first-visit transactions on promo days.
Can these benchmarks be compared across states?
No. License caps, medical versus adult-use structure, and wholesale price deflation differ so widely that a $35 Michigan basket can be healthy while a $90 Florida medical basket is unremarkable. Michigan wholesale flower collapsed from roughly $3,200 per pound in 2022 to well under $1,000 by 2025. Report every metric within state and license class first.
What is a realistic gross margin range for a dispensary?
Top public operators have generally run 45–58% blended gross margin depending on state mix and integration depth. The low end reflects third-party-heavy sourcing in a compressed wholesale market; the high end reflects deep vertical integration in a limited-license state. Inside the store, flower is typically the thinnest margin category while vape and concentrates are the richest.
How do I fix a low average basket size?
Basket work is the fastest-returning intervention because the customer is already at the counter. Look at units per transaction, whether budtenders attach a pre-roll or edible to flower purchases, and whether menu layout buries higher-ticket categories. Attach rate by individual budtender for owned SKUs is one of the highest-leverage store metrics available and is directly coachable.
What does effective 280E tax burden measure?
It is federal income tax expense divided by pre-tax book income. Operator ranges have run from roughly 65% to above 90%, making it the single largest variable in cash conversion. It belongs on the weekly or monthly KPI page rather than buried in the tax footnote, because it tells you whether a marginal store is actually cash-positive after federal tax.
Why is customer count per day an early-warning metric?
Traffic moves before revenue does, so it flags demand problems while there is still time to react. Healthy adult-use stores commonly run 250–400 transactions daily, high-volume value markets exceed 600, and limited-license medical stores may run 120–200 on much larger tickets. Pair it with staffing hours to get transactions per labor hour and separate demand problems from scheduling problems.
How should house-brand penetration be managed?
Set a target band, commonly 40–55% for vertically integrated operators, and track attach rate by budtender and by store. Below 30% means the operator built cultivation and manufacturing capacity and then gave the shelf away to third parties. This is a merchandising and budtender-education problem, and it is measurable at the individual staff level, which makes it directly coachable.
What is the biggest mistake operators make with these KPIs?
Averaging across states. A national basket-size average blends a $35 Michigan market with a $90 Florida medical market and produces a number that describes nothing. The second most common mistake is chasing traffic with discounts, which lifts customer count immediately while lowering net basket, repeat rate, and margin, making the dashboard look healthy for a quarter.
Sources
- https://www.sec.gov/cgi-bin/browse-edgar?action=getcompany&company=trulieve&type=10-K
- https://www.sec.gov/cgi-bin/browse-edgar?action=getcompany&company=green+thumb+industries&type=10-K
- https://www.sec.gov/cgi-bin/browse-edgar?action=getcompany&company=curaleaf&type=10-K
- https://www.irs.gov/newsroom/irs-issues-guidance-on-280e
- https://www.cannabisbusinesstimes.com/
- https://www.mjbizdaily.com/
- https://www.headset.io/insights
- https://www.bdsanalytics.com/
- https://www.metric.com/
- https://www.biotrack.com/
Related on PULSE
- [More sales kpis for cannabis retail dispensary rankings and buying guides](/knowledge)
- [PULSE Tools and calculators](/tools)
- [Everything on PULSE RevOps](/)
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
 pulse-industry-kpisTop 10 Sales KPIs for Beauty and Cosmetics Brand in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial EV Fleet Telematics & Charging Management in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Print and Copy Services in 2027
 pulse-industry-kpisTop 10 Sales KPIs for AI Document Intelligence in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Crane and Rigging Services in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Vector Database in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Convenience Store in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Computer Vision API in 2027
 pulse-industry-kpisTop 10 Sales KPIs for Commercial Sanitation & Cleaning Equipment Distribution in 2027
 pulse-industry-kpisTop 10 Sales KPIs for AI Recruiting in 2027