

What do CRO compensation benchmarks actually look like by company stage in 2027?
 Curated byKory White · Fractional CRO · Maryland
Quality
Certified
By 2027, CRO compensation benchmarks track company stage tightly: pre-seed and seed CROs typically land $200K–$350K OTE with 1.5–3.0% equity, Series A sits at $300K–$450K OTE with 0.75–1.5%, Series B at $400K–$600K with 0.5–1.0%, Series C at $500K–$800K with 0.25–0.6%, and public-company CROs clear $650K–$1.2M cash plus $3M–$8M in annual RSU and PSU grants. The mix shifts from equity-heavy to cash-heavy as the company scales.
The two structural models: OTE-anchored versus equity-anchored packages
Most CRO compensation conversations collapse into a false binary. Either you negotiate the headline OTE — the base salary plus target variable that recruiters quote — or you negotiate the equity grant as the real economic engine. The truth is that these are two different packages wearing the same title, and the right choice depends almost entirely on company stage.
The OTE-anchored model dominates at Series C and beyond. Here, base salary and target variable together represent 60–75% of expected realized value over a three-year tour. The equity grant is real but secondary — typically 0.25–0.6% at Series C, dropping to 0.10–0.3% pre-IPO and further at public companies where annual RSU refreshes replace the big upfront grant. This model suits CROs who want predictable cash, who are optimizing for a shorter tenure (the median CRO tour runs 18–19 months per Heidrick & Struggles' Route to the Top research), or who are joining a company where the equity upside is already priced in by late-stage investors.
The equity-anchored model dominates from pre-seed through Series B. At these stages, the OTE is often a fiction — a Series A company promising a $400K OTE may have only raised enough to cover 18 months of runway, and the variable component depends on hitting a quota that assumes a sales team the CRO hasn't hired yet. The real compensation is the equity grant: 1.5–3.0% at pre-seed, 0.75–1.5% at Series A, 0.5–1.0% at Series B. A CRO who takes a $50K OTE discount to gain an extra 0.25% at Series A is making a rational bet if the company reaches a $500M+ outcome — that 0.25% is worth $1.25M at a $500M exit, versus the $150K in foregone cash over three years.
The practical mistake is treating these as interchangeable. A CRO recruited to a Series B company who negotiates hard on OTE but accepts the standard 0.5% equity grant has optimized the smaller line item. A CRO at a public company who fights for a bigger equity percentage but ignores the annual RSU refresh cadence has done the same thing in reverse. The stage determines which lever actually moves lifetime compensation.
The compensation structure also interacts with the RevOps function in ways that aren't obvious at signing. A CRO whose package is heavily variable-weighted will push for aggressive quota-setting and accelerator design that flows down to every rep's comp plan. A CRO whose package is equity-heavy will tolerate a more conservative variable structure because the cash upside matters less. The downstream effects on the revenue organization's compensation philosophy — and therefore on RevOps plan administration — start with the CRO's own package.
How to decide between the two models
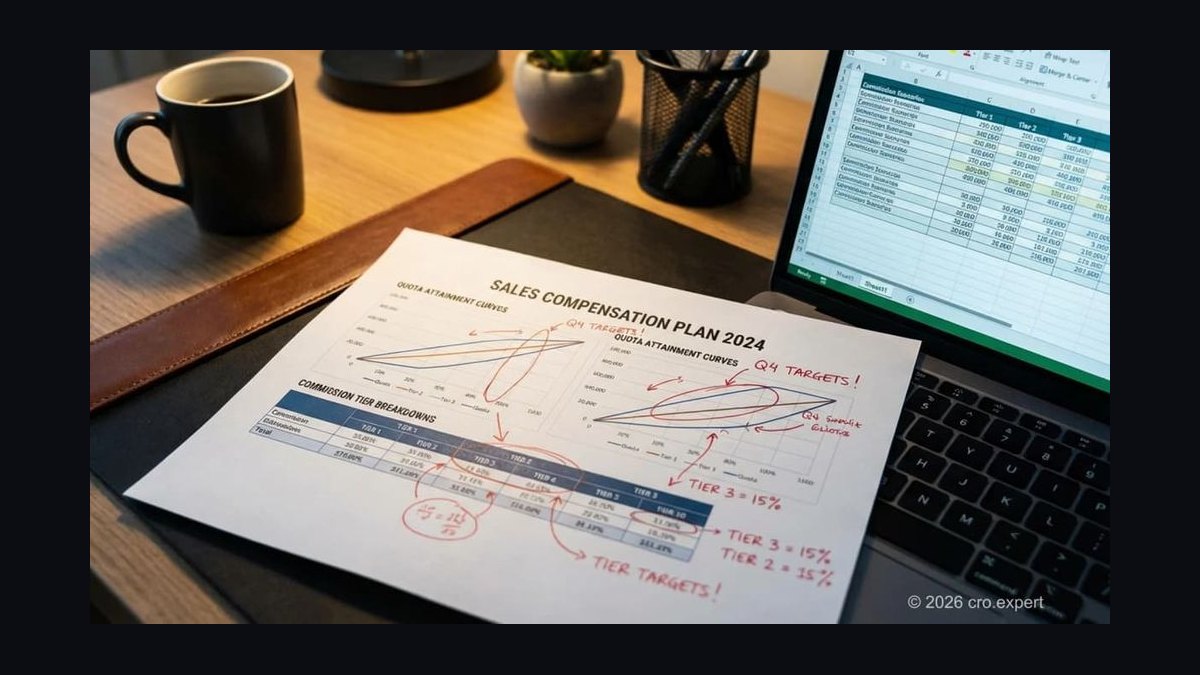
The decision tree is not about which model is "better" in the abstract. It's about matching the model to the company's stage, the CRO's risk tolerance, and the realistic exit timeline.
The critical branch is the second one: at Series A and B, the CRO's decision hinges on whether a liquidity event is realistically within three years. If the company is on a credible path to acquisition or IPO within that window, the equity-anchored model wins — the percentage matters more than the cash because the cash is capped but the equity is not. If the exit horizon is longer than three years, the CRO should blend: negotiate a defensible OTE floor to cover living expenses and a meaningful equity grant to capture the upside.
At Series C and beyond, the OTE-anchored model is almost always correct. The equity percentage is too small to move the needle on a per-point basis, and the cash is real. The negotiation shifts from "how much equity" to "what refresh policy, what severance, what acceleration terms." These are the levers that protect the CRO against the 18-month median tenure reality.
Public-company CROs operate under a third model entirely: the annual RSU refresh cycle. The initial grant matters less than the cadence and size of annual refreshes, which are set by the compensation committee and benchmarked against a peer group. A public CRO who negotiates a strong initial grant but no commitment to refresh cadence has optimized the wrong variable.
Concrete numbers behind each option
The stage-by-stage bands are the starting point for any negotiation, but the numbers only become actionable when you understand what each line item actually delivers in realized compensation.
At pre-seed and seed, the OTE band runs $200K–$350K, but the cash component is often $150K–$200K base with a variable target the company may not be able to fund. The equity grant of 1.5–3.0% is the real compensation. A 2.0% grant at a $10M post-money valuation dilutes to roughly 0.4–0.6% by Series C and 0.2–0.3% by IPO, but on a $1B exit that remaining stake is still worth $2M–$3M. The trade-off is stark: the CRO is taking a venture bet, not a salary.
Series A packages look more conventional. Base runs $175K–$250K, variable $125K–$200K, OTE $300K–$450K, equity 0.75–1.5% on a four-year vest with a one-year cliff. The 50/50 base-to-variable split is the canonical structure — roughly 70% of Series A CRO packages use it, according to Alexander Group's sales compensation survey data. The variable is paid against an annual quota typically set at 4–6x OTE, meaning a $400K OTE CRO carries a $1.6M–$2.4M personal quota on top of managing team quota. Sign-on bonuses run $25K–$100K with a 12-month clawback on voluntary departure.
Series B is the inflection point. Base $225K–$325K, variable $175K–$275K, OTE $400K–$600K, equity 0.5–1.0%. The equity percentage shrinks but the dollar value of the grant often increases because the post-money valuation has grown 3–5x. A 0.75% grant at a $300M post-money is $2.25M in paper equity; the same percentage at a $100M Series A would have been $750K. Sign-on bonuses move to $50K–$150K, and refresh policy starts to matter — the Carta and Pave benchmarks show a 25%-of-original-grant annual refresh as the standard retention mechanism.
Series C packages are where the OTE-anchored model takes over. Base $275K–$425K, variable $225K–$375K, OTE $500K–$800K, equity 0.25–0.6%. The variable mix may shift to 60/40 base-heavy as the role becomes more about org-building than deal-closing. Quota multipliers compress to 5–7x OTE because the organizational quota is larger and the yard is harder. MBO bonuses tied to strategic objectives — international expansion, product attach rate, partner channel revenue — layer on top of the variable at 10–25% of the variable total.
Series D and pre-IPO packages push OTE to $600K–$1.0M with equity of 0.15–0.4%. The equity is typically a mix of options on an updated 409A and RSUs that vest on a double trigger combining time-vesting with a liquidity event. Sign-on bonuses can reach $250K. The critical negotiation at this stage is the post-IPO transition language: a one-time pre-IPO refresh (25–50% of the original grant), a defined post-IPO RSU refresh cadence, and a PSU framework if the company is moving to a public-company compensation structure.
Public-company CRO compensation is disclosed in DEF 14A proxy statements filed with the SEC, making it the most reliable benchmark in the industry. The structure standardizes around base salary of $400K–$650K, target annual cash bonus of 75–150% of base, annual RSU grants, and annual PSU grants tied to multi-year revenue, ARR, or total shareholder return targets. Total annual compensation for public SaaS CROs typically runs $3M–$8M in equity value plus $650K–$1.2M in cash. The exact figures change annually as companies refresh their named executive officers and as equity vests at different prices, but the structural pattern is stable.
The variable structure itself is where the accelerator math matters most. The dominant design in 2027, per Xactly Insights and CaptivateIQ benchmark data across thousands of SaaS comp plans, is 1.5x marginal payout at 100–115% attainment and 2.0x above 115%. A CRO with a $250K variable target who hits 120% of quota realizes roughly $250K plus (20% × 1.5 × $250K) = $325K, depending on the exact accelerator schedule. The single highest-leverage negotiation at the variable layer is uncapped accelerators above 150% attainment — a clause that costs the company nothing if the CRO doesn't outperform but pays 2–4x extra in the years they do.
Equity refresh policy is the second-most-negotiated equity term and the one most CROs leave undefined. The standard, per Carta and Pave, is 25% of the original grant annually starting at month 18–24, designed to maintain a rolling four-year vest. A CRO who doesn't negotiate explicit refresh policy in the offer letter is accepting whatever the compensation committee discretionarily decides at year two — and committees in tight cap tables often deliver less than the benchmark.
Change-of-control acceleration is the most economically important equity term and the one most CROs underweight. The Cooley GO data on executive employment agreements shows three common structures: no acceleration (the CRO loses unvested equity if acquired and terminated), single-trigger acceleration (acceleration at the moment of acquisition regardless of termination), and double-trigger acceleration (acceleration only if the company is acquired and the CRO is terminated without cause within a defined window, typically 12–18 months). Double-trigger on 100% of unvested equity is the senior-executive standard at Series B and beyond. The difference between having it and not having it can be $500K or more on a single acquisition outcome.
Implementation details and sequencing
Negotiating a CRO package is a sequencing problem. The order in which terms are discussed, the documents that get signed, and the timing relative to the company's fundraising calendar all affect the outcome.
The first step is establishing the band. Pull the Pavilion Revenue Compensation Report, the Alexander Group Sales Compensation Trends Survey, the Heidrick & Struggles Route to the Top data, and the Carta and Pave benchmarks for the company's stage and sector. These are the anchors. The candidate's current compensation is data, not a benchmark — a CRO coming from a public company will have a higher cash number and a lower equity percentage than the stage band suggests, and the negotiation should reset to the band rather than anchoring on the prior package.
The second step is separating the compensation package from the compensation plan. The package is the executive employment agreement: base, equity, sign-on, severance, change-of-control, refresh policy. The plan is the annual sales compensation plan: quota, variable structure, accelerators, SPIFs, MBOs, territory and credit rules. These are different documents negotiated at different times, and the CRO must see the plan template — or at least the structural terms — before signing the offer letter. A CRO with a $400K variable target who is then handed a plan with a $30M organizational quota and capped accelerators has effectively had the variable line redefined after signing.
The third step is locking the protection terms. Severance, change-of-control acceleration, and the definitions of "cause" and "good reason" are the insurance policy against the 18-month median tenure. The standard severance at Series B is 6–9 months base plus COBRA plus 12 months of continued vesting on involuntary termination without cause. At Series C it moves to 9–12 months base plus 12 months COBRA plus 12–18 months continued vesting. The "cause" definition should be narrow — fraud, material breach, conviction of a felony related to the job — with a written notice requirement and a 30-day cure period. A broad "cause" definition that includes poor performance or "loss of confidence" gives the CEO the ability to terminate for any reason without paying severance.
The fourth step is pulling in own counsel. Cooley, Gunderson Dettmer, Wilson Sonsini, Latham, Orrick, and Morrison Foerster all have executive compensation specialists who routinely represent CRO candidates against company counsel. The cost is typically $8K–$25K for a comprehensive package review and red-line, and it returns 10–50x on a Series B or later package. The CRO who signs without counsel is accepting whatever language the company's lawyers drafted.
The fifth step, often overlooked, is the handoff to RevOps. Once the CRO is in seat, the compensation plan they negotiated becomes the template for the entire revenue organization's variable compensation. The quota multiplier, accelerator schedule, kicker thresholds, and cap policy flow down to every rep. A CRO who negotiated uncapped accelerators for themselves but accepts capped accelerators for the team has created a two-tier system that will surface in retention data within two quarters. The RevOps leader who administers the plan needs to understand the CRO's package because it sets the philosophical ceiling for what the organization will tolerate in plan design.
The sixth step is the annual review cadence. The compensation committee at a Series B or later company typically meets in Q1 to set base, target bonus, and equity refresh for the fiscal year. Special meetings happen around acquisition discussions, IPO pricing, and major strategic shifts. The CRO who builds direct relationships with the compensation committee chair and the independent directors — separate from the CEO relationship — has a meaningfully better outcome at refresh time. This is not political maneuvering; it's the structural reality of how compensation decisions get made at venture-backed and public companies.
The final implementation detail is the realized-comp calculation. The CRO should model the package against the realistic distribution of outcomes: 80–90% variable attainment on average, 30–50% equity dilution from grant to exit, 18-month median tenure, and the tax drag from ISO exercise (AMT exposure), NSO exercise (ordinary income), and RSU vesting (income tax at the vest-date price). Realized compensation at the end of a CRO tour is typically 40–70% of the headline package value. A CRO who negotiates on OTE alone but evaluates the offer on realized-comp expectation captures more value than one who optimizes only the headline number.
Related questions
How does CRO compensation differ between SaaS and non-SaaS companies?
SaaS CRO packages typically run 5–15% above the general technology band because the recurring revenue model demands a revenue leader who understands net revenue retention, expansion revenue, and multi-product attach. Non-SaaS companies with transactional revenue models often pay more in variable and less in equity because the revenue is more predictable.
What is the typical equity vesting schedule for a CRO?
The standard is a four-year vest with a one-year cliff, monthly vesting thereafter. Some late-stage and public companies use a three-year vest for RSU grants. The cliff is the critical term — a CRO terminated at month 11 with no acceleration walks away with nothing.
How does a CRO's compensation change after an IPO?
Post-IPO, the CRO's compensation shifts from a large upfront option grant to an annual RSU refresh cycle. Base salary typically increases 10–20% to reflect public-company norms, the variable target may increase, and the equity component becomes an annual grant benchmarked against a peer group rather than a one-time negotiation.
Can a CRO negotiate compensation after joining the company?
Yes, but the leverage is different. The annual review cycle is the natural point for renegotiation, and a CRO who has outperformed has significant leverage. Mid-year renegotiations typically happen around a competing offer, a major strategic shift, or a promotion to a broader role. The comp committee is the decision-maker, not the CEO alone.
What happens to CRO equity if the company is acquired for less than the last valuation?
In a down-round acquisition, common stock may be underwater and preferred stockholders get paid first. The CRO's options may be worthless, but the change-of-control acceleration and severance terms still apply. Some packages include a "liquidation preference protection" clause that guarantees a minimum payout, but this is rare and typically only negotiated by CROs with significant leverage.
FAQ
What is the single most important term in a CRO compensation package?
Change-of-control acceleration. The difference between double-trigger 100% acceleration and no acceleration on a $750K unvested equity grant is $750K in a single acquisition outcome. The CRO who negotiates this term correctly captures more value than one who negotiates a higher OTE but accepts no acceleration.
How does company stage affect the base-to-variable split?
Early-stage companies (pre-seed through Series B) typically use a 50/50 split. Series C and D companies shift toward 60/40 base-heavy as the role becomes more about org-building. Public companies often use 50/50 but with a larger total cash component. The split is moderately negotiable — a 10–25% swing is common.
What is the typical CRO tenure and how does it affect package design?
The median CRO tenure is 18–19 months, per Heidrick & Struggles' Route to the Top research. This means the package must be designed assuming the CRO will not vest a full four-year grant. Acceleration provisions, severance, and refresh policy are more economically important than the headline OTE because the median tour ends before the original grant fully vests.
How do accelerators work in a CRO compensation plan?
Accelerators typically pay 1.5x marginal on attainment between 100% and 115% of quota, then 2.0x above 115%. A CRO with a $250K variable target who hits 120% of quota realizes roughly $325K. The highest-leverage negotiation is uncapped accelerators above 150% attainment — a clause that costs the company nothing if the CRO doesn't outperform.
What is the difference between a compensation package and a compensation plan?
The package is the executive employment agreement: base, equity, sign-on, severance, change-of-control, refresh policy. The plan is the annual sales compensation plan: quota, variable structure, accelerators, SPIFs, MBOs, territory and credit rules. The package is negotiated at hiring; the plan is negotiated annually. The CRO must see the plan template before signing the package.
How much does it cost to have a lawyer review a CRO compensation package?
Executive compensation counsel at firms like Cooley, Gunderson Dettmer, Wilson Sonsini, Latham, Orrick, or Morrison Foerster typically charges $8K–$25K for a comprehensive package review and red-line. The return on that investment is 10–50x on a Series B or later package because the terms negotiated — acceleration, severance, refresh policy — are worth multiples of the legal fee.
Sources
- Heidrick & Struggles — Route to the Top and executive compensation research: https://www.heidrick.com
- Crist Kolder Associates — Volatility Report on executive turnover: https://www.cristkolder.com
- Alexander Group — Annual Sales Compensation Trends Survey: https://www.alexandergroup.com
- Pavilion — Annual Revenue Compensation Report: https://www.joinpavilion.com
- Equilar — Executive compensation database and peer-group benchmarking: https://www.equilar.com
- Pave — Real-time compensation benchmarks: https://www.pave.com
- Carta — Compensation and equity grant benchmarks: https://www.carta.com
- Cooley GO — Executive employment agreement templates and change-of-control guidance: https://www.cooleygo.com
- Gunderson Dettmer — Venture capital and executive compensation practice: https://www.gunder.com
- SEC EDGAR — DEF 14A proxy statements for public-company compensation data: https://www.sec.gov
Related on PULSE
- What does a fractional CRO actually do in the first 90 days?
- How do you build a RevOps compensation plan that scales from Series A to Series C?
- What are the benchmarks for sales rep quota attainment in B2B SaaS?
- How do you structure a CRO and CMO partnership for revenue alignment?
- What does a VP of Revenue Operations compensation package look like in 2027?
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 revopsWhat's the median pay mix for a VP Sales at Series B SaaS in 2027?
 revopsWhat's the typical CRO base salary in NYC vs SF vs remote in 2026?
 revopsWhat is the 2027 typical AE accelerator design (above-quota commission rates)?
 revopsWhat accelerator multiples are typical past 100% of quota for SaaS AEs in 2027?
 compWhat's a fair OTE for an enterprise AE selling $100k+ ACV deals in 2026?
 compensationHow do we design commission accelerators that actually change rep behavior without blowing the cap in 2027?
 revopsWhat is the 2027 typical SDR comp plan structure with AI agent context?
 croHow does a CRO partner with the CFO on bookings, ARR, and revenue translation in 2027?
 croWhat are the must-have skill sets for a Chief Revenue Officer in 2027?
 croHow does a Chief Revenue Officer build a board update that doesn't get them fired in 2027?