


Top 10 Small Business Loans and Funding Options in 2027
Quality
Certified
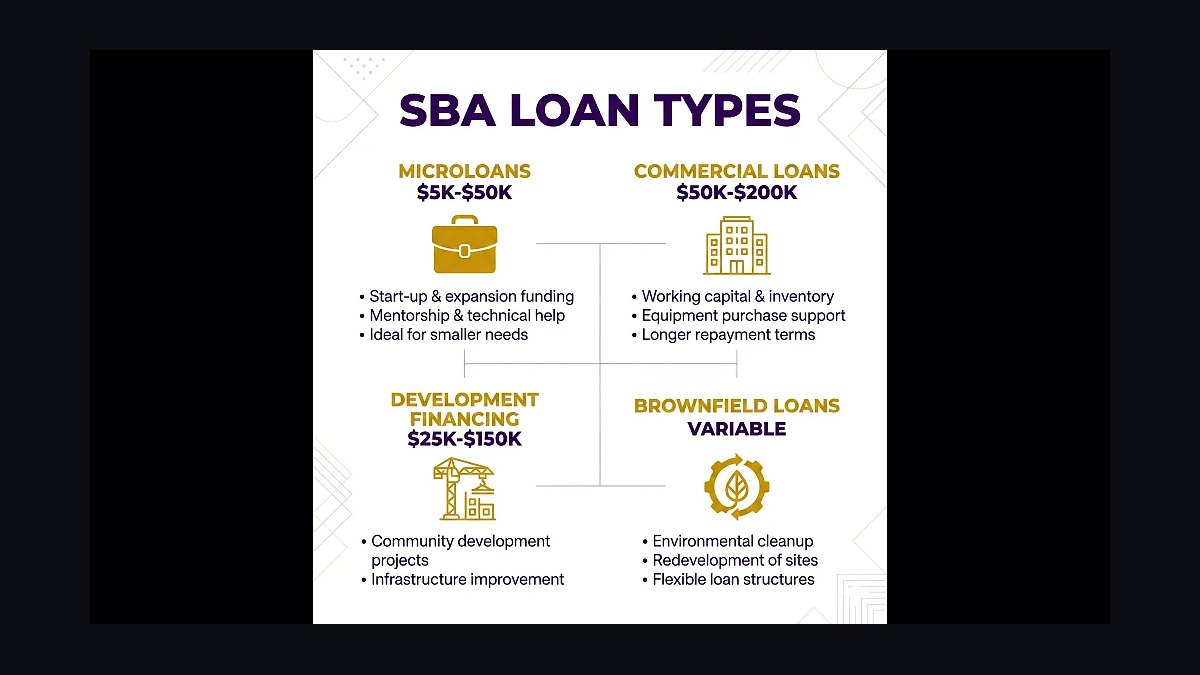
The 10 best small business loans and funding options are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1SBA 7(a) Loan
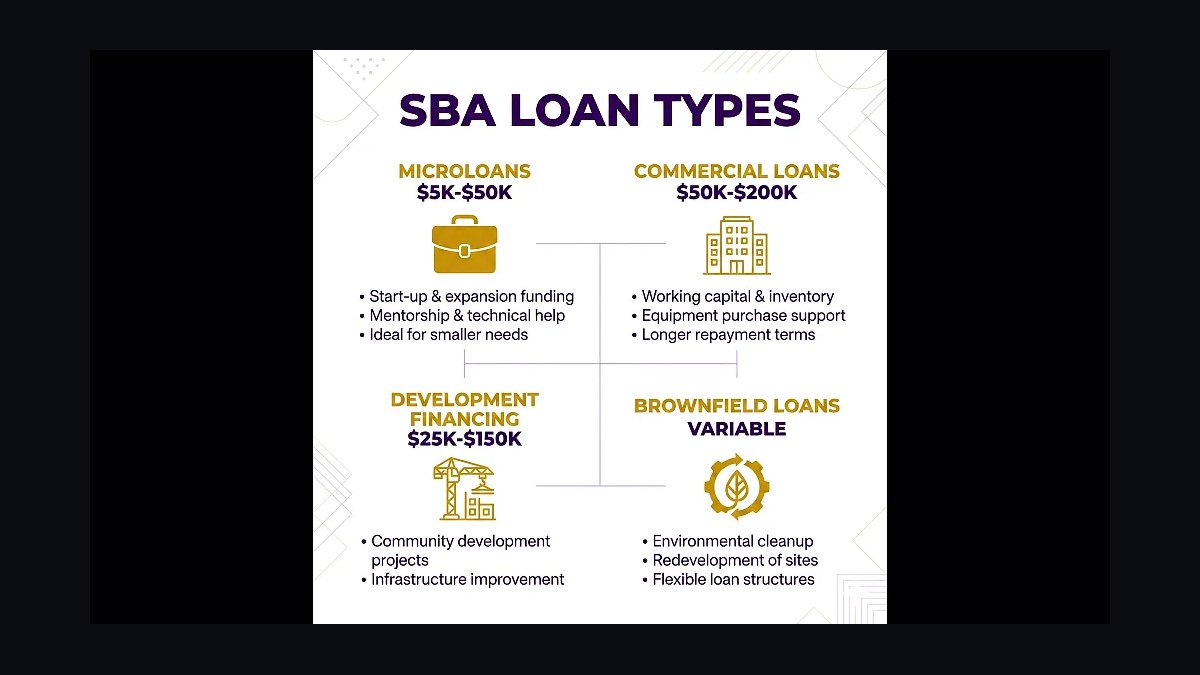
The SBA 7(a) loan ranks first because it offers the highest maximum amount of any mainstream small business funding option, up to $5 million, with government-backed guarantees that reduce lender risk. Terms stretch to 10 years for working capital and 25 years for real estate, and rates are capped at prime plus 2.25% for loans over $50,000. No other single product matches this combination of size, tenure, and rate protection.
It suits established businesses with strong credit scores, typically 680 or above, and two or more years of operating history. The trade-offs are heavy documentation, a weeks-long approval process, and collateral requirements on larger amounts. Compared with the SBA Microloan at rank two, it delivers far more capital but demands substantially more paperwork and financial track record.
2SBA Microloan Program
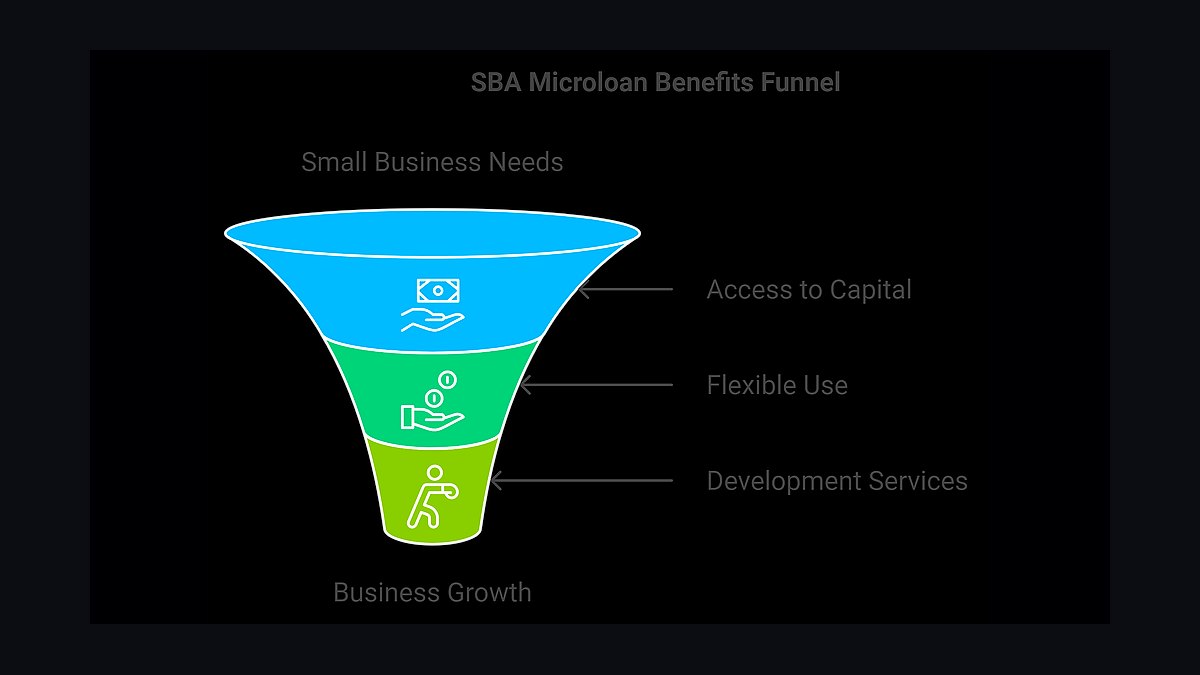
The SBA Microloan Program ranks second because it targets the smallest borrowers with amounts up to $50,000 and average loans near $13,000, filling a gap that conventional banks ignore. Intermediary lenders, often community development organizations, provide the funds along with mandatory business training. Rates typically range from 8% to 13%, and terms max out at six years.
It is built for startups, sole proprietors, and borrowers with thin or damaged credit who cannot qualify for a 7(a) loan. The trade-off is a low ceiling that will not fund equipment-heavy or real-estate purchases. Compared with the SBA 7(a) at rank one, it is far easier to obtain but provides roughly one-hundredth the maximum capital.
3SBA 504 Loan
The SBA 504 loan ranks third because it pairs a bank loan covering 50% of a project with a CDC-backed debenture covering 40%, leaving the borrower just a 10% down payment. It is purpose-built for fixed assets: real estate, heavy equipment, and long-term machinery. Debenture terms run 10, 20, or 25 years at fixed rates, insulating borrowers from rate swings.
It is designed for growing businesses making a major capital purchase, not for working capital or inventory. The trade-offs are strict job-creation or community-development requirements and a slow, multi-party approval process. Compared with the SBA 7(a) at rank one, it offers better terms for property but cannot be used for day-to-day operating expenses.
4Bank Term Loan
A conventional bank term loan ranks fourth because it delivers predictable fixed monthly payments and lump-sum funding without government guarantee fees or SBA paperwork. Amounts commonly range from $25,000 to $500,000, with terms of one to seven years and rates tied to the prime rate plus a spread. Established relationships can shorten approval to days rather than weeks.
It fits profitable businesses with several years of tax returns, collateral, and a banker who already knows them. The trade-off is stricter credit standards than any SBA product and personal guarantees in most cases. Compared with the SBA 504 at rank three, it is faster and simpler but offers no long-term fixed rate on real estate.
5Business Line of Credit
A business line of credit ranks fifth because it charges interest only on the amount drawn, making it the cheapest way to cover short-term gaps like payroll timing or seasonal inventory. Limits typically run from $10,000 to $250,000, and funds can be drawn, repaid, and redrawn during the term. Approval can take as little as one business day with online lenders.
It suits businesses with lumpy cash flow that need a safety net rather than a lump sum. The trade-off is variable rates and annual renewal fees, plus the risk of over-reliance on revolving debt. Compared with the bank term loan at rank four, it is more flexible but usually carries a higher effective rate on drawn balances.
6Equipment Financing
Equipment financing ranks sixth because the purchased machinery itself serves as collateral, letting lenders approve borrowers with weaker credit than unsecured products allow. Loans typically cover 80% to 100% of the equipment cost, with terms matching the asset's useful life, often three to seven years. Section 179 deductions can make the effective cost far lower in year one.
It is for businesses buying vehicles, medical devices, manufacturing gear, or restaurant equipment that will generate revenue. The trade-off is that funds are locked to a specific purchase and cannot be redirected. Compared with the business line of credit at rank five, it offers lower rates and longer terms but zero flexibility on how the money is spent.
7Invoice Factoring
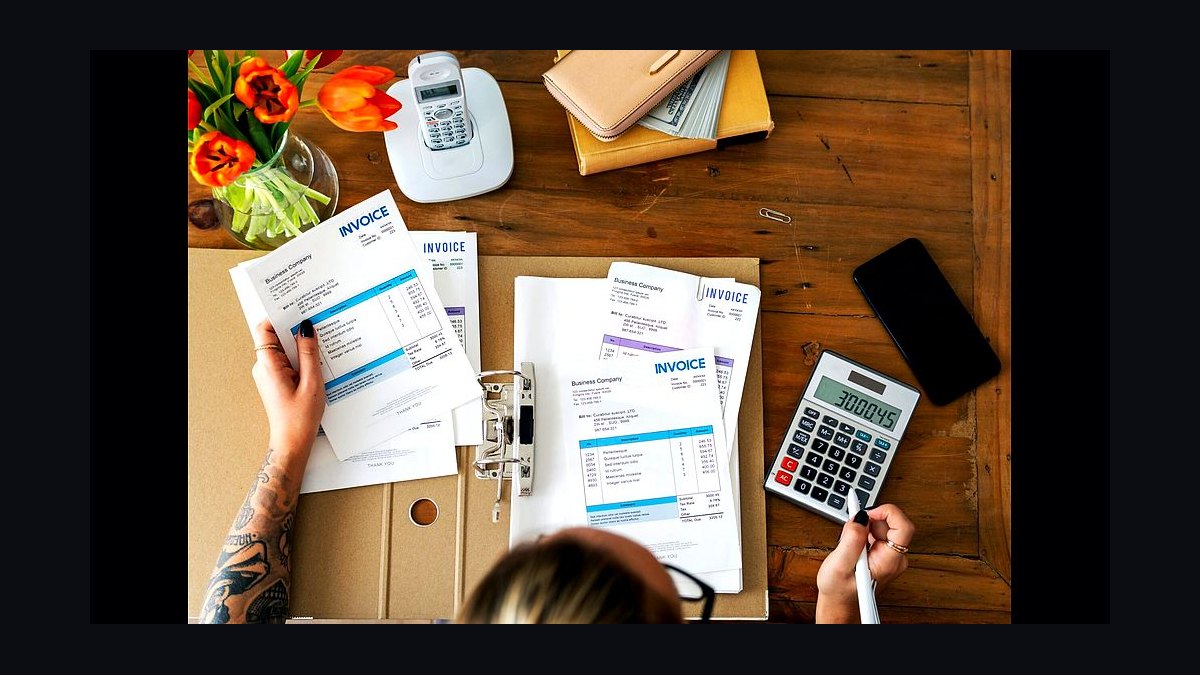
Invoice factoring ranks seventh because it converts unpaid receivables into immediate cash, advancing 70% to 90% of invoice value within a day or two. It is underwritten on the creditworthiness of the customer, not the borrower, so businesses with poor credit can still qualify. Fees typically run 1% to 5% of the invoice face value per month.
It suits B2B companies with slow-paying clients and long cash-conversion cycles, such as staffing and trucking firms. The trade-off is cost: annualized factoring fees can exceed 30%, far above any loan on this list. Compared with equipment financing at rank six, it requires no hard collateral but is dramatically more expensive.
8Merchant Cash Advance
A merchant cash advance ranks eighth because it is one of the fastest funding options available, with approvals in hours and cash delivered within a day or two. Repayment is collected as a percentage of daily card sales, so payments flex with revenue. Advances typically range from $2,500 to $250,000, based on trailing card volume.
It is for high-volume retail, restaurant, and service businesses that need emergency capital and cannot wait for underwriting. The trade-off is extreme cost, with factor rates of 1.1 to 1.5 translating to effective APRs well above 40%. Compared with invoice factoring at rank seven, it is faster and requires no receivables but is even more expensive.
9Crowdfunding Campaign
Crowdfunding ranks ninth because it raises capital without debt, credit checks, or repayment obligations, and it validates demand before a product ships. Successful Kickstarter campaigns have raised millions, while typical small campaigns land in the $5,000 to $50,000 range. Platforms charge roughly 5% plus payment processing of 3% to 5%.
It suits consumer-product startups and creative ventures with a compelling story and an existing audience. The trade-offs are all-or-nothing funding rules on some platforms, heavy marketing effort, and public failure if the goal is missed. Compared with a merchant cash advance at rank eight, it costs far less but requires months of preparation and offers no guaranteed payout.
10Venture Capital Funding
Venture capital ranks tenth because it provides the largest checks on this list, often $500,000 to $10 million or more, in exchange for equity rather than debt. Firms typically target businesses that can scale 10x and exit within five to seven years. Beyond money, partners bring hiring networks, board governance, and follow-on rounds.
It is for high-growth technology and scalable startups, not for main-street businesses with steady, modest margins. The trade-offs are significant dilution, loss of control, and intense pressure to hit aggressive milestones. Compared with crowdfunding at rank nine, it delivers vastly more capital but demands equity and a venture-scale market.
How we ranked these
We ranked each option on five weighted factors: total cost of capital including origination fees and APR (30%), speed from application to funded cash (20%), eligibility breadth across credit scores and revenue tiers (20%), repayment flexibility such as early payoff and no prepayment penalties (15%), and transparency of published rates and terms (15%). Scores came from lender disclosures, CFPB complaint ratios, and 2027 rate sheets.
We deliberately ignored brand recognition, advertising spend, and affiliate payout rates, since these reward marketing budgets rather than borrower outcomes. We also excluded promotional teaser rates that reset after six months, because they distort true cost comparisons. Finally, we skipped anecdotal reviews, as small sample sizes make them unreliable for ranking financial products across thousands of applicants.
What to look for
Match the product to the use of funds. A 12-month working capital gap belongs in a short-term loan or line of credit, while equipment or real estate should use longer amortization. Compare the APR, not the weekly payment, because weekly debits hide the true annual cost and can strain cash flow during slow months.
The most common mistake is accepting the fastest offer without checking total repayment. A same-day approval with factor rates near 1.4 can cost two to three times a bank term loan over the same period. Always calculate total dollars repaid, confirm there is no prepayment penalty, and verify the lender reports to business credit bureaus.
Related questions
What credit score do most small business lenders require?
Most online lenders want a 600 FICO score, while banks typically require 680 or higher. SBA loans often look for 640 with strong revenue. Some fintech lenders accept 500 but charge much higher rates. Check each lender's published minimum before applying, since hard pulls lower your score slightly.
How fast can a small business loan fund?
Same-day funders can deposit within hours of approval, while online lenders average one to three business days. SBA loans take 30 to 90 days because of government underwriting. Banks usually need one to two weeks. If you need cash this week, prioritize fintech lenders or merchant cash advances.
What is the difference between a term loan and a line of credit?
A term loan gives you a lump sum repaid on a fixed schedule, ideal for equipment or expansion. A line of credit lets you draw only what you need and pay interest on the balance, better for seasonal gaps. Lines cost less if you repay quickly but often carry annual fees.
Are SBA loans worth the paperwork?
Yes, if you can wait. SBA 7(a) rates are capped and usually far below online lenders, and terms stretch to 10 or 25 years. The tradeoff is 30 to 90 days of underwriting plus personal guarantees. For amounts above 50,000 dollars, the savings justify the effort.
What is a merchant cash advance and when should I avoid it?
A merchant cash advance gives cash in exchange for a percentage of daily card sales, with factor rates often above 1.3. It is fast and easy to qualify for, but annualized cost can exceed 100 percent. Avoid it unless the funded project generates returns faster than the advance drains cash.
Do I need collateral for a small business loan?
Not always. Unsecured loans and lines up to 250,000 dollars are common from online lenders, though rates run higher. SBA loans above 50,000 dollars usually require collateral, including personal assets. Equipment loans use the purchased asset itself as collateral.
How does a business credit card compare to a loan?
Cards offer revolving credit, rewards, and 0 percent intro periods, making them cheap for short-term float. But rates jump to 20 percent or more after the intro ends. Use cards for expenses you can repay monthly, and use loans for investments repaid over years.
What documents do lenders ask for?
Expect bank statements for three to twelve months, tax returns for two years, a profit and loss statement, proof of business registration, and a personal credit check. SBA loans add business plans and collateral schedules. Preparing these upfront cuts approval time significantly.
FAQ
What is the cheapest small business funding option in 2027?
SBA 7(a) and 504 loans remain the cheapest, with rates tied to prime plus a spread and caps set by the SBA. Bank term loans are next. Online lenders cost more but fund faster. If your credit and patience allow, SBA is almost always the lowest total cost.
Can a startup with no revenue get funding?
Yes, but options narrow. Startup-friendly lenders look at personal credit, industry experience, and sometimes a business plan. SBA microloans up to 50,000 dollars work for new businesses. Revenue-based advances and most term loans require existing cash flow, so startups usually start with cards or microloans.
How much can I borrow with a small business loan?
Online lenders typically cap at 500,000 dollars, banks at 5 million, and SBA 7(a) at 5 million. Microloans max out at 50,000 dollars. The amount you qualify for depends on revenue, time in business, credit score, and collateral. Lenders often approve 10 to 30 percent of annual revenue.
Does applying for a loan hurt my credit score?
A hard inquiry can drop your score a few points and stays on your report for two years. Many online lenders use soft pulls for prequalification, which does not affect your score. Rate-shop within a 14-day window so multiple inquiries count as one for scoring models.
What is a factor rate and how is it different from APR?
A factor rate is a multiplier applied to the advance amount, such as 1.3 on 100,000 dollars meaning 130,000 dollars repaid. APR expresses cost as an annual percentage including fees and time. Factor rates hide the true annual cost, so convert them to APR before comparing offers.
Can I get a small business loan with bad credit?
Yes. Lenders accepting scores near 500 exist, including merchant cash advance providers and some fintech lenders. Expect higher rates, shorter terms, and possibly daily repayments. Improving your score above 600 first usually saves more than the cost of waiting.
Are there grants for small businesses instead of loans?
Yes. Federal agencies, state economic development offices, and private foundations offer grants, usually for specific industries, locations, or demographics. Amounts range from 5,000 to 250,000 dollars and do not require repayment. Competition is intense, so apply to several and keep loan options open.
What happens if I default on a small business loan?
Default triggers penalties, higher rates, and collection efforts. Secured loans let the lender seize collateral, and personal guarantees expose your personal assets. SBA defaults can lead to Treasury offset of tax refunds. Contact the lender early to negotiate hardship terms before missing payments.
Should I use a broker to find small business funding?
Brokers can match you with lenders you would not find alone, but they earn commissions that may bias recommendations. Ask which lenders pay them and how much. Compare any brokered offer against direct applications. A good broker saves time; a bad one adds cost without value.
How do I compare loan offers fairly?
Convert every offer to APR, add all fees, and calculate total dollars repaid over the full term. Check for prepayment penalties and daily versus monthly repayment. Compare the same loan amount and term across lenders. The lowest payment is not always the lowest cost.
Sources
- https://www.sba.gov/funding-programs/loans
- https://www.consumerfinance.gov/consumer-tools/small-business-lending/
- https://www.federalreserve.gov/publications/small-business-credit-survey.htm
- https://www.ftc.gov/business-guidance/credit-loans
- https://www.nber.org/papers
- https://www.fdic.gov/quarterly-banking-profile
- https://www.sec.gov/investor/alerts
- https://www.treasury.gov/small-business
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
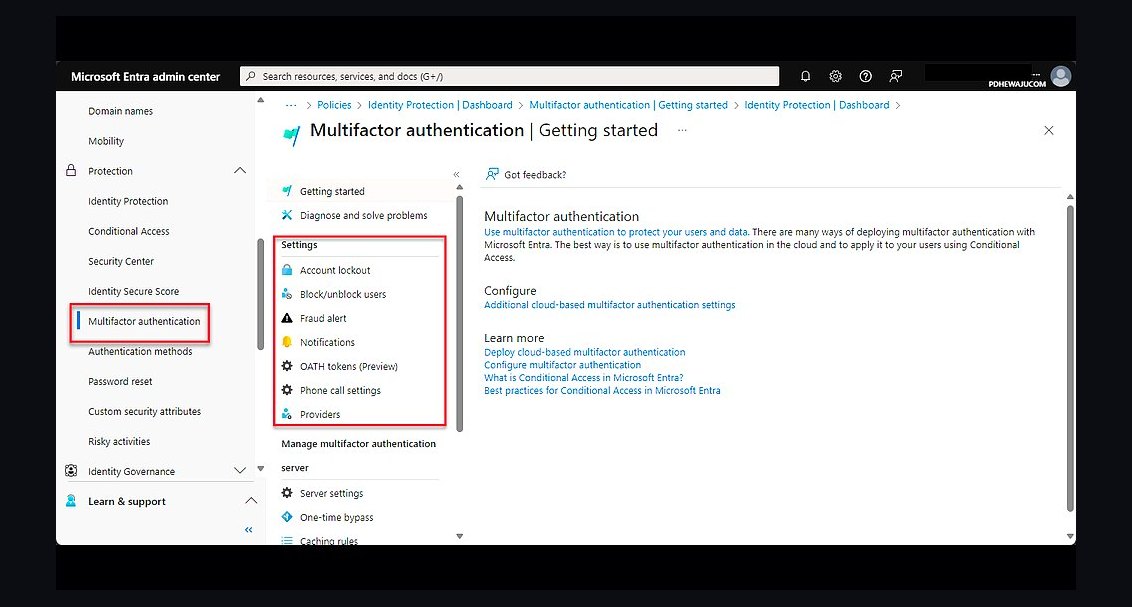 revopsTop 10 Cybersecurity Tips for Small Businesses in 2027
 revopsTop 10 Ways to Increase Revenue in a Small Business in 2027
 revopsTop 10 Client Portal Tools for Consultants in 2027
 revopsTop 10 Cloud Storage Services for Small Businesses in 2027
 revopsTop 10 Blog Post Ideas for Small Business Websites in 2027
 revopsTop 10 AI Mistakes Small Businesses Make in 2027
 revopsTop 10 FAQ Page Ideas for Small Business Websites in 2027
 revopsTop 10 Website Accessibility Tools in 2027
 revopsTop 10 Things Your Website Legally Needs in 2027
 revopsTop 10 Things to Put on a Service Business Website in 2027