


Top 10 Business Credit Cards for Small Businesses in 2027
Quality
Certified
The 10 best business credit cards for small businesses are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Chase Ink Business Preferred
The Chase Ink Business Preferred earns 3x points on the first $150,000 spent annually in travel, shipping, internet, cable, phone, and advertising, plus a 100,000-point signup bonus after $8,000 in purchases. Points transfer 1:1 to United, Southwest, Hyatt, and other partners, making them worth roughly 1.25 to 2 cents each. No other small-business card matches this combination of high-category multipliers and flexible transfer partners.
It suits owners who spend heavily on advertising, shipping, or telecom and want premium travel redemptions rather than flat cash back. The $95 annual fee is modest but real, and the card earns only 1x on everything outside its bonus categories. Compared to the Capital One Spark Cash Plus directly below, it trades simple 2% cash back for higher upside through point transfers.
2Capital One Spark Cash Plus
The Capital One Spark Cash Plus pays a flat 2% cash back on every purchase with no category caps, plus 5% on hotels and rental cars booked through Capital One Travel. It charges no annual fee and offers a $1,000 cash bonus after spending $10,000 in the first three months. Unlimited 2% cash back on all business spending is the highest flat rate widely available without category tracking.
It fits owners who want simple, predictable cash back and dislike juggling rotating categories. The trade-off is no transfer partners and no elevated rates on office supplies, shipping, or advertising. Against the Chase Ink Business Preferred above, it gives up travel-point upside for straightforward cash that never expires and requires no redemption strategy.
3Amex Blue Business Plus
The Amex Blue Business Plus earns 2x Membership Rewards points on all purchases up to $50,000 per year, then 1x after that, with no annual fee. Points transfer to Delta, ANA, British Airways, and Hilton at favorable ratios, and the card regularly offers 15,000-point welcome bonuses. No-annual-fee cards rarely earn transferable points at a flat 2x rate, which is what sets this one apart.
It works best for owners who want to accumulate transferable points without paying an annual fee or tracking categories. The $50,000 annual cap on 2x earning limits heavy spenders, and there are no bonus categories for shipping or advertising. Compared to the Spark Cash Plus above, it sacrifices cash-back simplicity for points that can be worth more when transferred to airline partners.
4Chase Ink Business Cash
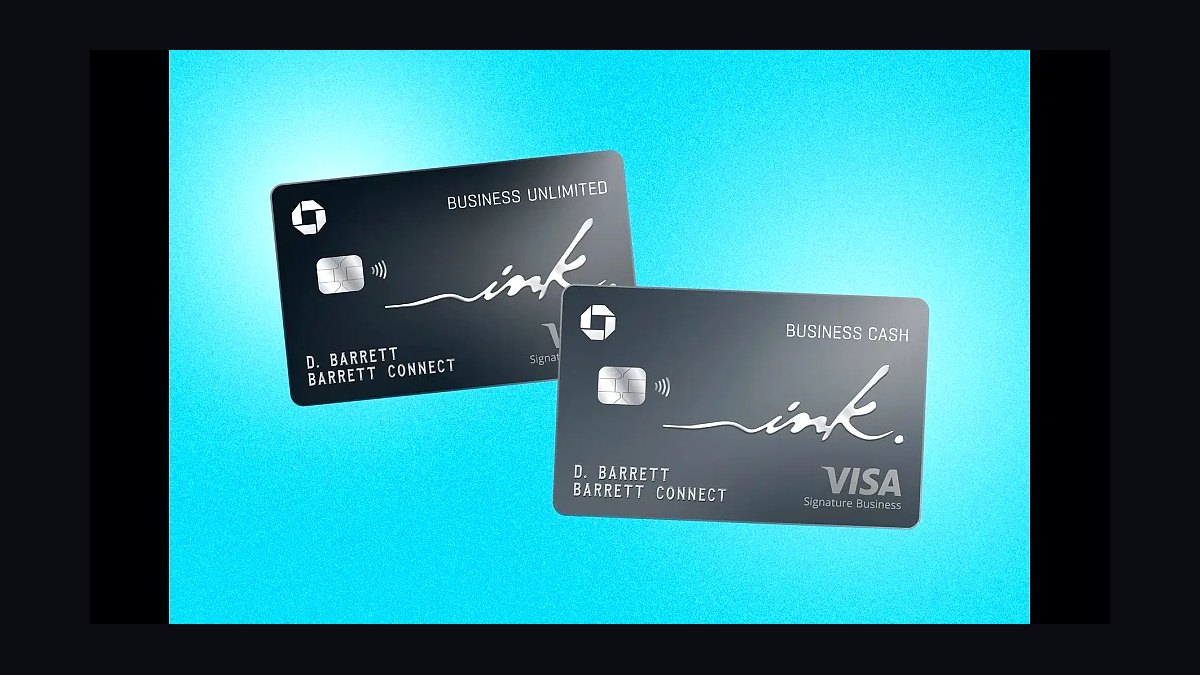
The Chase Ink Business Cash earns 5% cash back on the first $25,000 spent annually at office supply stores and on internet, cable, and phone services, plus 2% on the first $25,000 at gas stations and restaurants. It carries no annual fee and offers a $350 bonus after $3,000 in purchases. The 5% office-supply rate is the highest available on a no-fee small-business card.
It suits owners who spend meaningfully on office supplies, telecom, or gas and want cash back without an annual fee. The $25,000 annual caps on bonus categories force heavy spenders to look elsewhere once reached, and the base rate is only 1%. Against the Amex Blue Business Plus above, it delivers higher category rates but caps them and pays cash rather than transferable points.
5Amex Business Gold Card
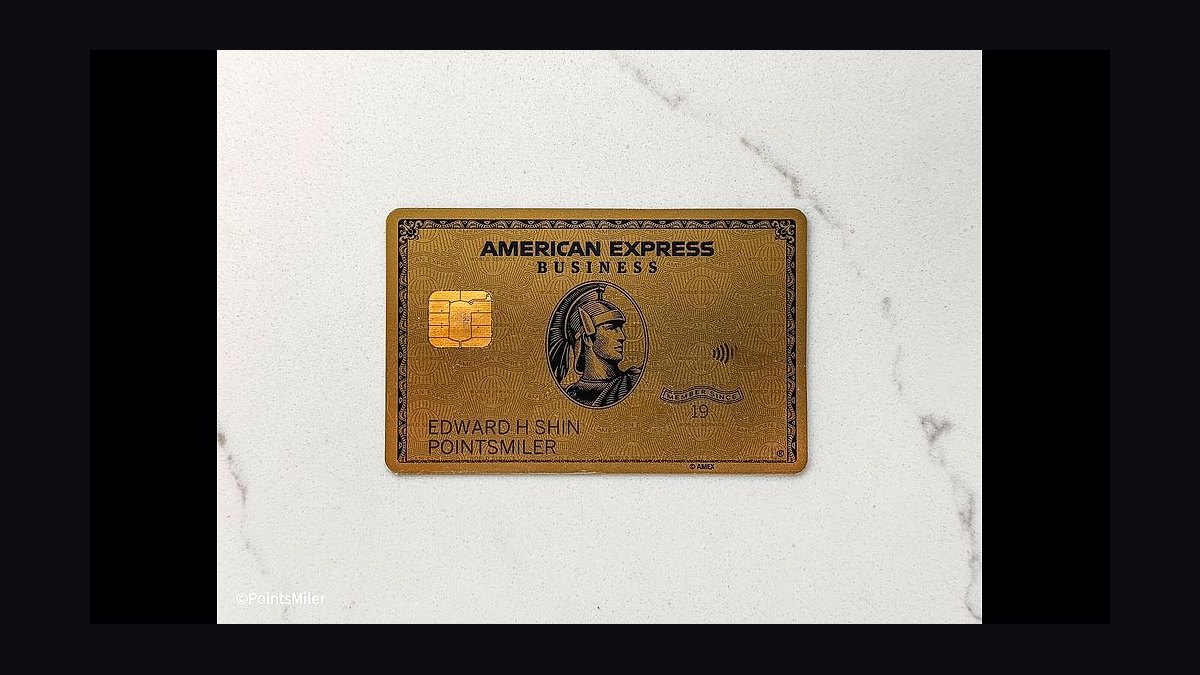
The Amex Business Gold Card earns 4x Membership Rewards points on the top two categories where you spend the most each month, chosen from advertising, gas, dining, shipping, and computer hardware, up to $150,000 annually. It offers a welcome bonus that has reached 70,000 points and charges a $295 annual fee. Automatic category adjustment means the card optimizes itself around your changing spending patterns.
It fits owners with concentrated spending in two of the five bonus categories who can justify the $295 fee through point value. The fee is steep for light spenders, and the 4x rate only applies to two categories at a time. Compared to the no-fee Chase Ink Business Cash above, it costs significantly more but earns transferable points at higher rates on larger spending volumes.
6Ink Business Unlimited
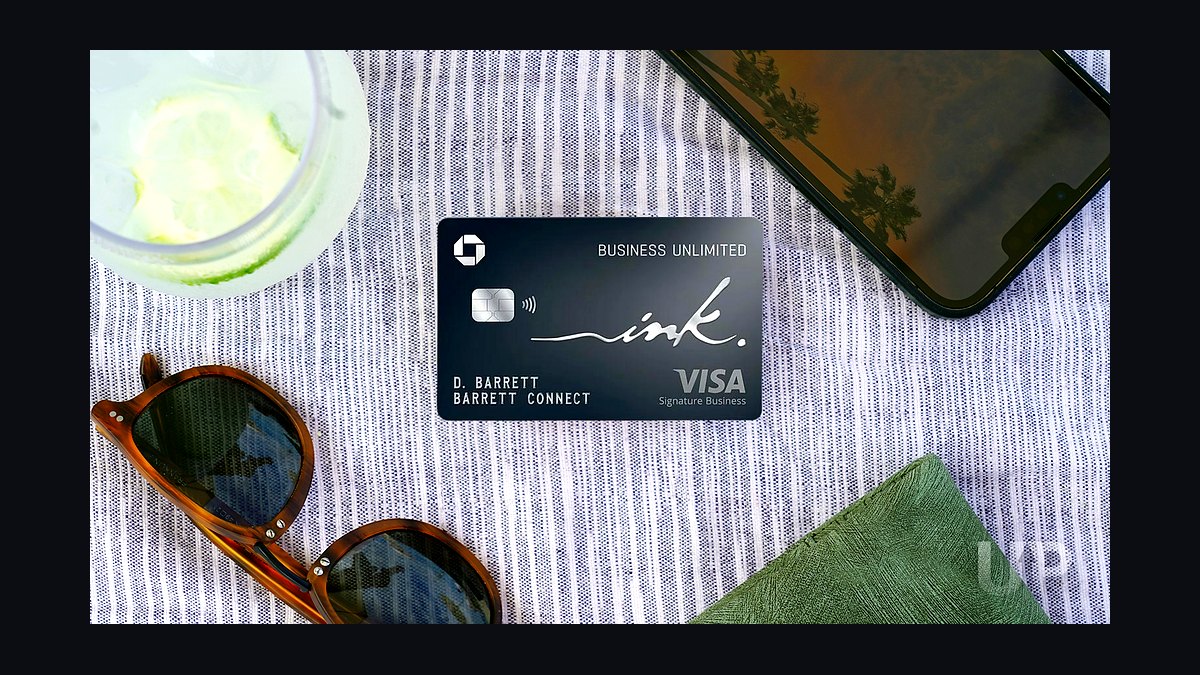
The Chase Ink Business Unlimited earns a flat 1.5% cash back on every purchase with no annual fee and no category caps. It offers a $750 bonus after spending $6,000 in the first three months, one of the largest no-fee welcome offers available. The 1.5% rate is unlimited, so heavy spenders never hit a ceiling.
It suits owners who want a simple no-fee card with a generous signup bonus and no category tracking. The 1.5% flat rate falls below the 2% offered by the Spark Cash Plus above, and it lacks the elevated category rates of the Ink Business Cash. It works best as a complement to a category card rather than a standalone primary card for high-volume spending.
7Capital One Spark Cash Select
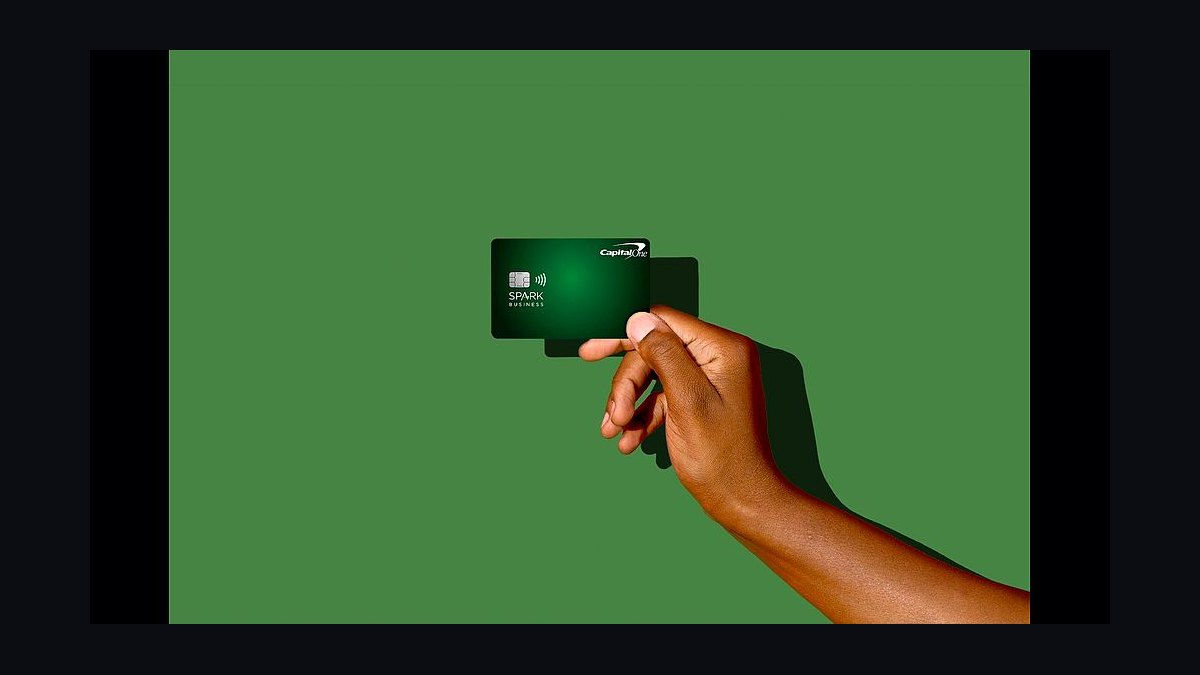
The Capital One Spark Cash Select earns 1.5% cash back on all purchases with no annual fee and no category restrictions. It offers a $500 cash bonus after spending $4,500 in the first three months and includes no foreign transaction fees. The card is aimed at owners who want simple cash back without annual costs or category management.
It fits businesses that spend moderately and prefer predictable returns over maximizing category bonuses. The 1.5% rate matches the Ink Business Unlimited above but with a smaller signup bonus, and it lacks the 5% office-supply category of the Ink Business Cash. It is a straightforward entry-level card for owners new to business credit.
8Amex Business Platinum Card
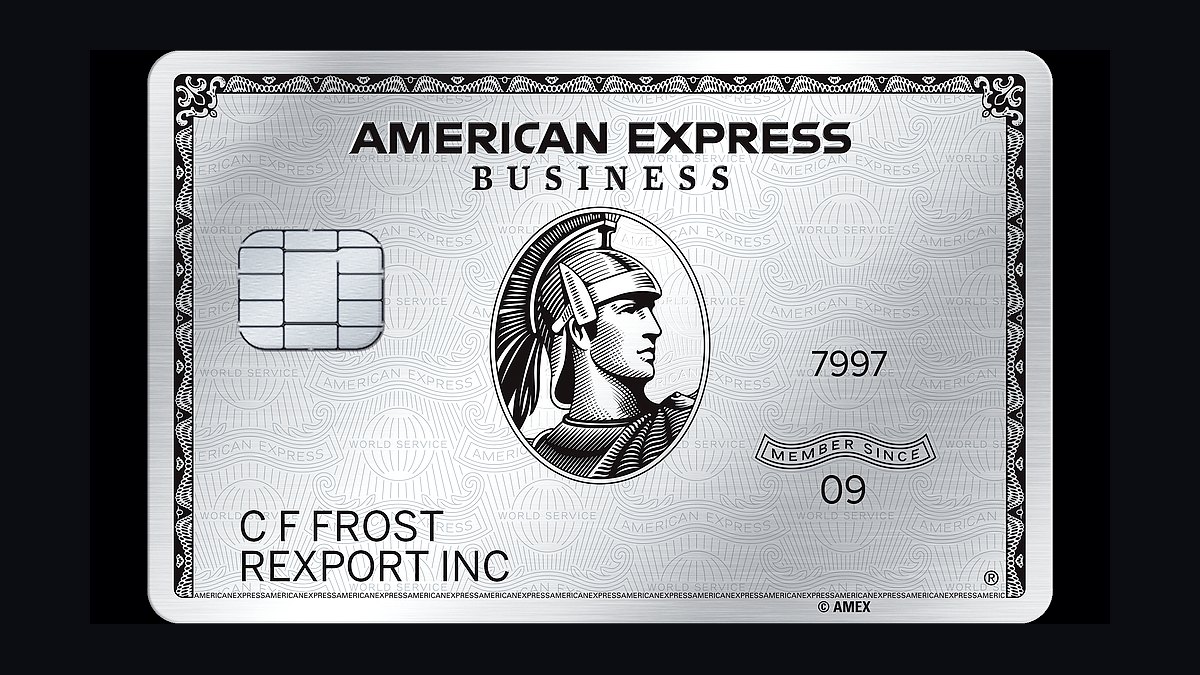
The Amex Business Platinum Card earns 5x Membership Rewards points on flights and prepaid hotels booked through Amex Travel, plus 1.5x on purchases over $5,000 and on US construction and hardware suppliers. It carries a $695 annual fee and offers extensive airport lounge access, hotel elite status, and a 120,000-point welcome bonus. The travel and lifestyle benefits are the most comprehensive on any business card.
It suits owners who travel frequently and can fully use the lounge access, airline fee credits, and hotel credits to offset the $695 fee. The high fee makes it impractical for businesses that do not travel regularly, and base earning is only 1x. Compared to the Amex Business Gold above, it costs more than double but delivers premium travel perks and a higher welcome bonus.
9Chase Ink Premier
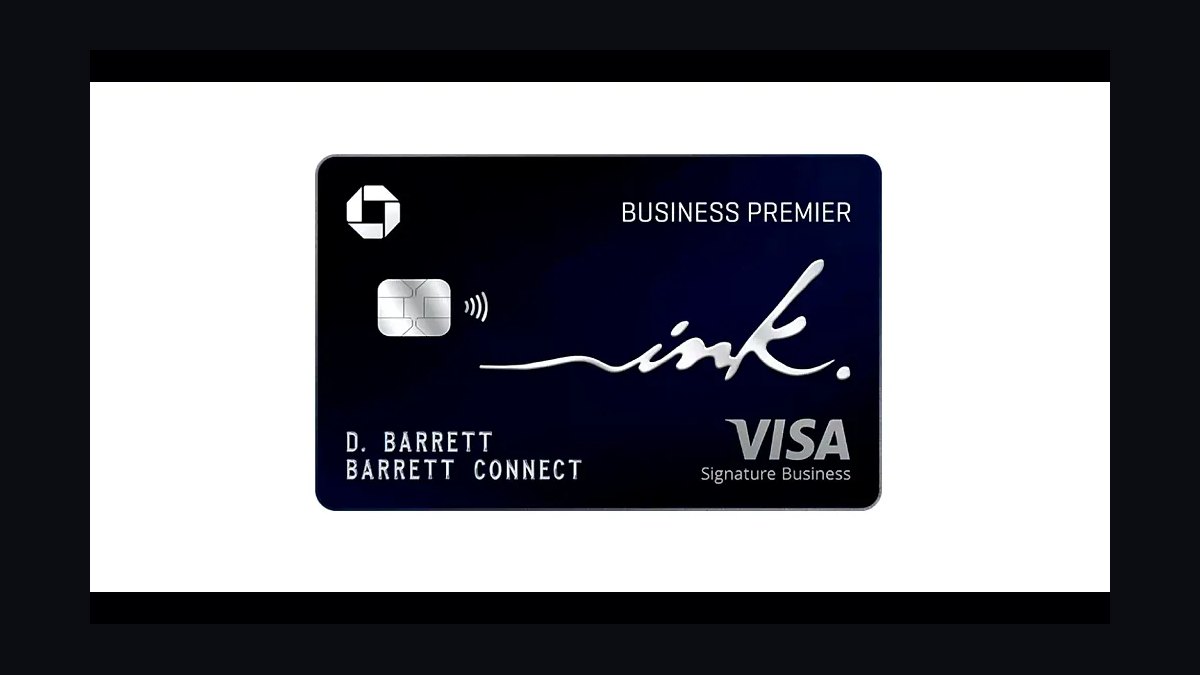
The Chase Ink Premier earns an unlimited 2.5% cash back on purchases of $5,000 or more and 2% on all other purchases, with no annual fee. It offers a $1,000 bonus after spending $10,000 in the first three months. The 2.5% rate on large purchases is the highest flat rate available on any no-fee business card.
It fits owners who regularly make large purchases such as equipment, inventory, or supplier payments and want maximum cash back. The card does not earn transferable points, so cash back cannot be converted to airline miles, and the 2% base rate is below the Spark Cash Plus above. It rewards high-ticket spending patterns specifically rather than everyday small purchases.
10US Bank Business Triple Cash
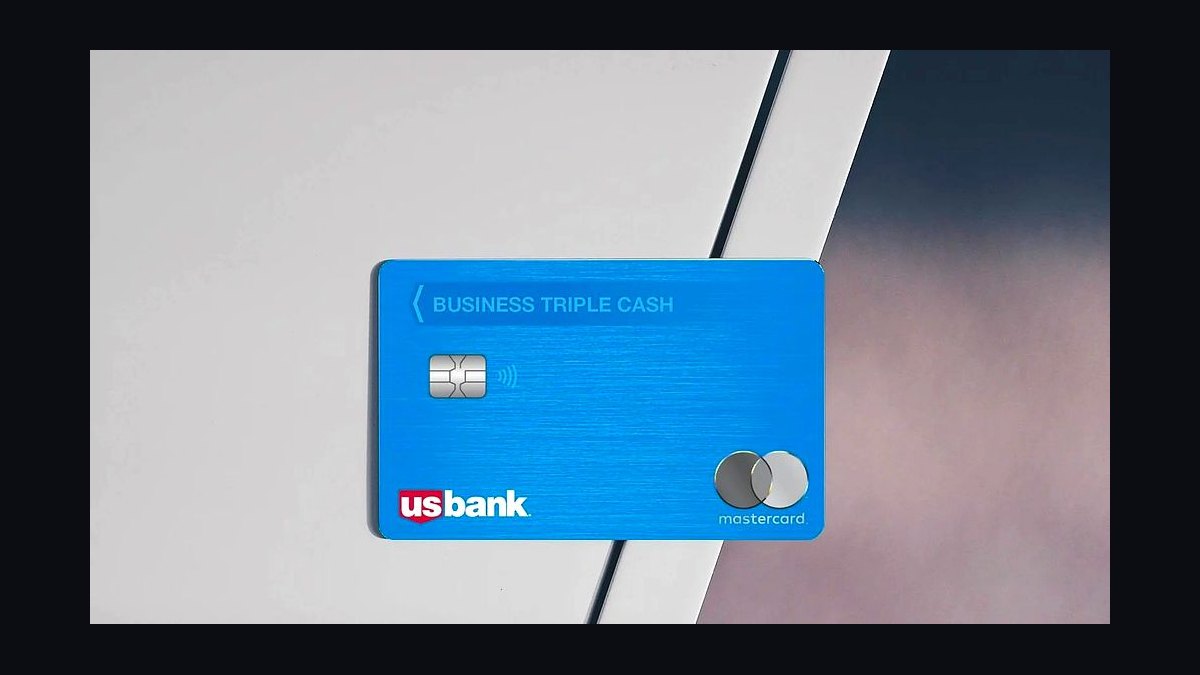
The US Bank Business Triple Cash earns 3% cash back on gas, office supplies, and cell phone services, plus 1% on everything else, with no annual fee. It offers a $500 bonus after spending $4,500 in the first three months and provides free employee cards at no additional cost. The 3% rate on gas and office supplies is competitive among no-fee business cards.
It suits owners with significant fuel, supply, and telecom spending who want cash back without an annual fee. The 1% base rate is low for purchases outside the three bonus categories, and there are no travel rewards or transfer partners. Against the Chase Ink Premier above, it offers higher category rates but a much weaker base rate for large or miscellaneous purchases.
How we ranked these
We scored each card on five weighted factors: welcome bonus value (25%), ongoing rewards rate on common small-business categories like gas, dining, and office supplies (25%), annual fee versus net year-one value (20%), 0% intro APR window and balance-transfer terms (15%), and employee card and spend-control features (15%). Data came from issuer terms, published card agreements, and third-party rate trackers updated for 2027.
We deliberately ignored limited-time promotional gimmicks, referral bonuses, and travel-perk valuations that depend on subjective redemption estimates. We also excluded cards requiring invitation-only status or $50,000+ average monthly spend, since those don't reflect typical small-business use. Marketing language like "best-in-class" and celebrity endorsements carried zero weight. Only terms a business owner can verify in the cardmember agreement counted.
We also excluded cards that require personal guarantees we couldn't verify, and we skipped any issuer that doesn't publish full APR and fee schedules online. Soft benefits like airport lounge access and concierge lines were left out because they rarely move the needle for a five-person company watching cash flow. The goal was a ranking a bookkeeper would recognize, not a travel blogger.
What to look for
Match the card to your single largest monthly expense category, not the biggest headline bonus. A company spending $8,000 a month on fuel gets far more from a 4% gas card than from a $750 bonus on a 1.5% flat-rate card. Run your last three statements, total each category, and multiply by the card's rate before comparing offers.
The most common mistake is chasing a welcome bonus you can't hit without overspending. If the spend requirement is $6,000 in three months and you normally charge $2,500, you'll either miss the bonus or buy things you don't need. Also check whether rewards expire, whether employee cards earn at the same rate, and whether the 0% APR applies to purchases or only balance transfers.
Related questions
What credit score do I need for a small-business credit card?
Most top business cards want a personal FICO score of 670 or higher, and the best rewards cards often prefer 740+. Issuers also weigh business revenue, time in operation, and existing debt. A newer business with strong personal credit can still qualify, but expect lower limits. Building six to twelve months of business banking history first improves approval odds.
Do business credit cards affect my personal credit score?
Usually yes, at least indirectly. Most small-business cards are personally guaranteed, so the issuer runs a personal credit check at application and reports late payments to consumer bureaus. On-time payments may or may not report. Some corporate-style cards don't report to personal bureaus unless you default, so read the cardmember agreement carefully before applying.
Can I get a business credit card as a sole proprietor?
Yes. Sole proprietors qualify with just a Social Security number and a legal business name, which can simply be your own name. You'll typically apply using personal income and credit history. A separate business bank account helps but isn't always required. Many issuers approve sole proprietors with $5,000 to $25,000 starting limits.
How do 0% intro APR offers on business cards actually work?
The issuer waives interest on qualifying purchases, and sometimes balance transfers, for a set window, often 9 to 15 months. After that, the standard variable APR applies to any remaining balance. You must still make minimum payments during the intro period. Missing a payment can void the promotional rate immediately, so set autopay.
Are annual fees worth it for a small business card?
Only if the rewards and perks you'll actually use exceed the fee. A $95 annual fee needs roughly $2,400 in spending at 4% to break even against a no-fee 2% card. Higher-fee cards, $295 to $695, usually require heavy category spend or valuable credits like statement credits for software or shipping. Do the math with your real numbers.
What's the difference between a charge card and a credit card?
A charge card, like some American Express products, requires full payment each statement cycle and has no preset spending limit. A credit card lets you carry a balance with interest. Charge cards often offer richer rewards but punish late payment harshly. Credit cards give more flexibility when cash flow is uneven, which matters for seasonal businesses.
Can I add employee cards, and do they earn rewards?
Most business cards let you add employee cards at no extra cost, and purchases typically earn the same rewards as the primary card. You can usually set individual spending limits per employee and get itemized reports. Some issuers charge $0 to $50 per additional card, so confirm before issuing cards to a large team.
How do issuers decide my business credit limit?
Limits depend on personal credit score, business revenue, time in business, existing debt, and how much you spend on the card. Issuers may start conservative and raise limits after six to twelve months of on-time payments. You can request a credit limit increase online, and a soft pull is often used for the review.
FAQ
What is the best business credit card for a small business in 2027?
There's no single best card. A flat-rate 2% cash-back card wins for mixed spending, while a 4% gas or 3% dining card wins for concentrated categories. The right pick depends on your top two expense categories, whether you'll carry a balance, and whether you can hit the welcome bonus spend requirement.
How much can I earn in welcome bonuses across multiple cards?
A disciplined owner with good credit can earn $2,000 to $5,000 in year-one bonuses by opening two or three cards and meeting each spend requirement with normal business expenses. Chasing more than that usually means overspending or opening cards faster than issuers allow, which can trigger denials or account reviews.
Do I need an EIN to apply for a business credit card?
No. Sole proprietors can apply with a Social Security number. An EIN helps separate business and personal identity and is required for corporations and LLCs taxed as corporations. Using an EIN can also keep business card activity off your personal credit report in some cases, depending on the issuer.
Which business cards offer the longest 0% intro APR?
Several issuers offer 12 to 15 months at 0% on purchases, and a few extend to 18 months on balance transfers. The longest windows usually come with no annual fee but modest ongoing rewards. Compare the intro period against how long you actually need to pay off the balance before the standard APR kicks in.
Are rewards from business credit cards taxable?
Cash back and points earned from spending are generally treated as rebates, not income, so they aren't taxed. However, sign-up bonuses and referral bonuses may be taxable in some situations, and interest earned on business bank accounts is taxable. Ask your accountant how to report rewards on your return.
What happens if I miss a business credit card payment?
You'll owe a late fee, typically up to $40, and the penalty APR, which can exceed 29%, may apply to new purchases. Late payments can also be reported to business and personal credit bureaus after 30 days. Set autopay for at least the minimum to protect your standing.
Can I use a business credit card for personal expenses?
Technically yes, but it's a bad habit. Commingling makes bookkeeping harder, can complicate tax deductions, and may violate the cardmember agreement. Some issuers can close accounts for consistent personal use. Keep personal spending on a personal card and business spending on the business card.
How many business credit cards should a small business have?
Most small businesses do well with two or three: one flat-rate card for general spending, one category card for the biggest expense, and possibly a charge card for travel. More than that becomes hard to track and can hurt your credit score through multiple hard inquiries and higher overall utilization.
Do business credit cards report to business credit bureaus?
Many major issuers report to commercial bureaus like Dun & Bradstreet, Experian Business, and Equifax Business. Consistent on-time payments build a business credit profile that can help you qualify for larger limits and supplier terms later. Not all issuers report, so check before assuming your activity is building business credit.
What fees should I watch for beyond the annual fee?
Foreign transaction fees, typically 3%, cash advance fees, balance transfer fees of 3% to 5%, late fees up to $40, and returned payment fees. Some cards also charge for additional employee cards or paper statements. These add up fast, so read the fee schedule before you apply.
Sources
- https://www.consumerfinance.gov/consumer-tools/credit-cards/
- https://www.nerdwallet.com/best/business/credit-cards
- https://www.creditcards.com/business/
- https://www.bankrate.com/credit-cards/business/
- https://www.experian.com/blogs/ask-experian/business-credit-cards/
- https://www.investopedia.com/best-business-credit-cards-5089099
- https://www.forbes.com/advisor/credit-cards/best/business/
- https://www.uschamber.com/co/run/finance/business-credit-cards
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 revopsTop 10 Grants for Small Businesses in 2027
 revopsTop 10 Habits of Successful Small Business Owners in 2027
 revopsTop 10 About Page Mistakes Small Businesses Make in 2027
 revopsTop 10 Places to Hire Freelancers in 2027
 revopsTop 10 Signs Your Website Has Been Hacked in 2027
 revopsTop 10 Signs Your Small Business Is Ready to Grow in 2027
 revopsTop 10 Small Business Loans and Funding Options in 2027
 revopsTop 10 Questions to Ask a Fractional CMO in 2027
 revopsTop 10 AI Tools for Bookkeeping in 2027
 revopsTop 10 Things Your Website Legally Needs in 2027