


Top 10 Best Tech Stack Tools for Telehealth Platforms in 2027
Quality
Certified
The 10 best tech stack tools for telehealth platforms are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Salesforce Health Cloud
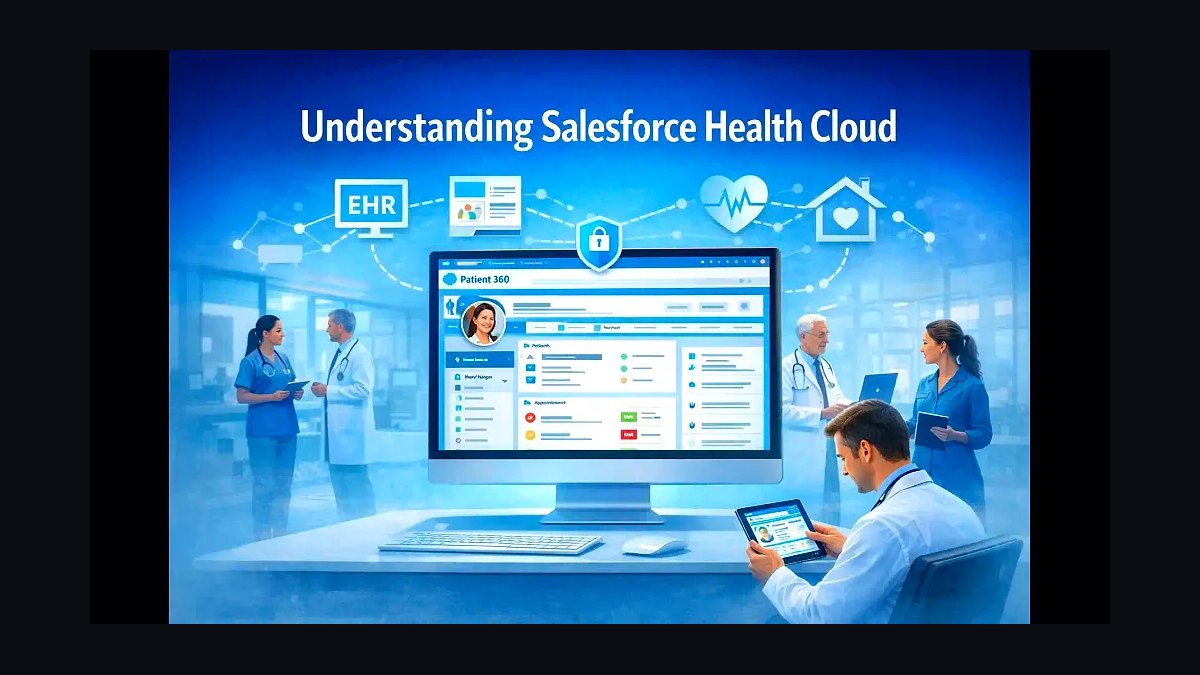
Salesforce Health Cloud ranks first because it anchors the 2027 telehealth stack as the central CRM, unifying patient acquisition, provider management, and revenue tracking in one platform. Einstein GPT auto-generates patient summaries, Revenue Cloud handles per-visit, per-member, and subscription billing, and MuleSoft connects natively to Epic, Clari, and Gong.
It suits enterprise telehealth organizations with complex, multi-stakeholder sales cycles of 8–14 months and dedicated RevOps teams. The trade-off is cost and implementation weight: licensing plus MuleSoft integration typically exceeds smaller platforms' entire budgets, and configuration requires certified admins. Compared to Epic's MyChart below it, Salesforce owns the commercial and revenue layer rather than the clinical portal, so most stacks run both side by side rather than choosing one.
2Epic MyChart
Epic MyChart ranks second because it remains the dominant patient portal in 2027, and telehealth platforms must offer native Epic integration via FHIR APIs to avoid manual data entry. Without it, clinical orchestration breaks: scheduling, intake, and visit documentation all degrade. Epic's FHIR API layer lets third-party telehealth tools read and write chart data, which is the single most-cited decision criterion in MEDDPICC scorecards, alongside AI scribe accuracy and compliance certifications.
It is built for health systems and telehealth providers whose patients and clinicians already live inside Epic, not for standalone digital-first startups with no hospital affiliation. The trade-off is rigidity: Epic controls the roadmap, integration timelines run long, and smaller vendors often wait quarters for API access. Compared to Salesforce Health Cloud above it, MyChart owns the clinical record while Salesforce owns the commercial pipeline, which is why enterprise stacks integrate both instead of replacing either.
3Nuance DAX Copilot
Nuance DAX Copilot ranks third because AI scribes became mandatory in the 2027 stack, and DAX Copilot is the benchmark competitors are measured against. It listens to visits and auto-generates SOAP notes, cutting clinician documentation time by 30–50% and enabling more billable visits per day. Improved coding accuracy also reduces claim denials and accelerates reimbursement, which directly feeds the ROI models buying committees demand before signing.
It fits large provider groups and health systems with high visit volumes where documentation burden drives clinician burnout and turnover. The trade-off is price and workflow dependence: it works best inside Microsoft and Epic environments, and accuracy varies by specialty and accent. Compared to Suki directly below it, DAX Copilot carries deeper enterprise integrations but less flexibility for smaller or mixed-EHR practices, so specialty clinics sometimes choose the lighter option.
4Suki AI Scribe
Suki AI Scribe ranks fourth because it delivers the same core documentation relief as larger rivals with faster deployment and broader EHR compatibility. It generates notes in real time across specialties, integrates with major EHRs without requiring the full Microsoft or Epic ecosystem, and consistently reduces documentation time enough to add billable visit capacity. For telehealth platforms evaluating AI scribe error rates on buying-committee scorecards, Suki is a frequent head-to-head finalist.
It suits independent practices, specialty clinics, and digital-first telehealth groups that want scribe benefits without enterprise procurement overhead. The trade-off is depth: it lacks the bundled Microsoft infrastructure and some of the largest health-system integrations that DAX Copilot carries. Compared to Nuance DAX Copilot above it, Suki wins on speed and flexibility but loses on entrenched enterprise footprint, so the choice usually comes down to existing EHR and cloud commitments.
5Amwell
Amwell ranks fifth because it has evolved into a comprehensive clinical orchestration ecosystem bundling video visits, remote patient monitoring, and asynchronous messaging in one platform. That bundling directly supports the 2027 vendor consolidation trend, where the average stack dropped from 12 tools to 7. For telehealth platforms, Amwell reduces integration complexity and total cost of ownership while covering the middle layer where virtual care actually happens.
It fits payers, health systems, and large telehealth operators that need broad clinical coverage rather than a single point solution. The trade-off is depth versus breadth: bundled suites rarely match best-of-breed tools in any one category, and pricing reflects enterprise scale.
6Teladoc Health
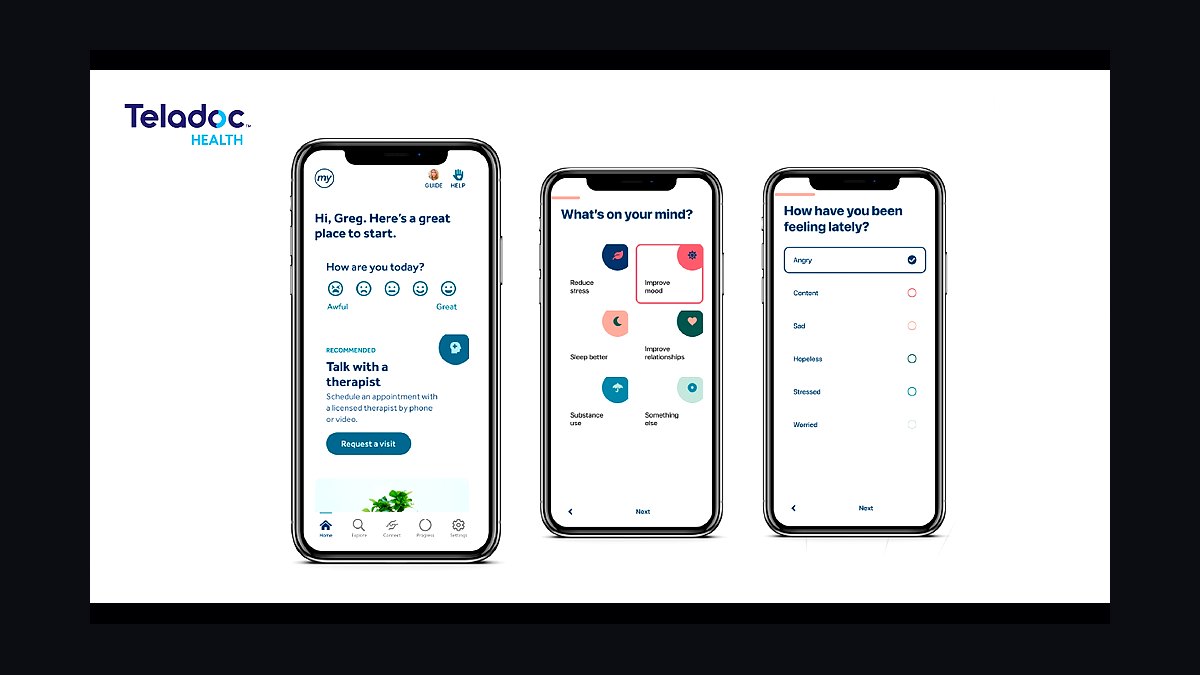
Teladoc Health ranks sixth because it remains one of the most recognized virtual care ecosystems, bundling video, remote patient monitoring, and asynchronous messaging at national scale. Its direct-to-consumer brand and payer relationships give telehealth platforms immediate access to established patient volume and proven clinical workflows. For organizations evaluating build-versus-buy in the clinical orchestration layer, Teladoc is the most common buy-side benchmark.
It suits employers, payers, and health systems that want proven virtual care delivery without building clinical operations from scratch. The trade-off is customization: platform depth and integration flexibility are limited compared to assembling best-of-breed components, and long-term economics favor the vendor. Compared to Amwell above it, Teladoc skews toward care delivery and consumer reach rather than infrastructure, so platforms needing white-label orchestration often evaluate both before deciding.
7Clari Revenue Intelligence
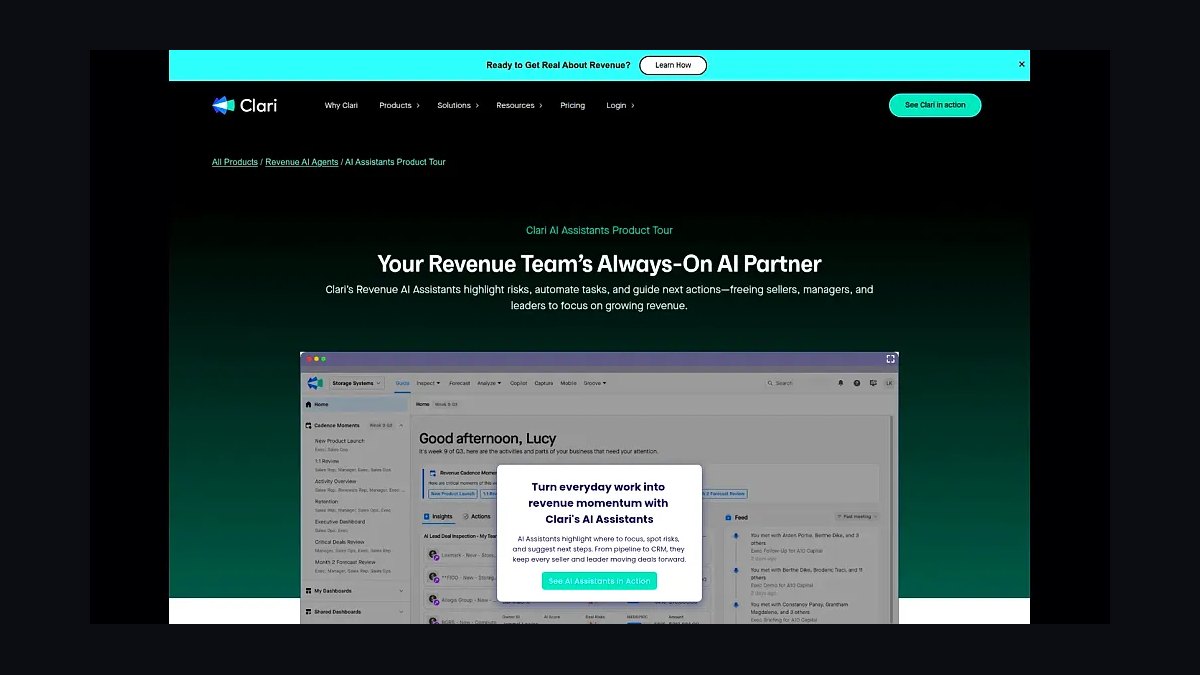
Clari ranks seventh because longer 8–14 month sales cycles made AI revenue forecasting essential in the 2027 telehealth stack. Clari predicts deal slippage with roughly 85% accuracy using signals like email response times and meeting attendance, and forecasts both subscription MRR and transactional per-visit revenue. For RevOps teams managing buying committees of 4–7 stakeholders, that predictive layer directly protects quarterly numbers.
It fits telehealth revenue operations teams with enough deal volume to train meaningful forecast models, typically mid-market and enterprise vendors. The trade-off is dependency: forecast quality collapses if CRM data hygiene is poor, and the platform adds another license to an already consolidated stack. Compared to Gong directly below it, Clari focuses on forecasting and pipeline analytics, while Gong centers on conversation intelligence and coaching, so many enterprise teams run both.
8Gong
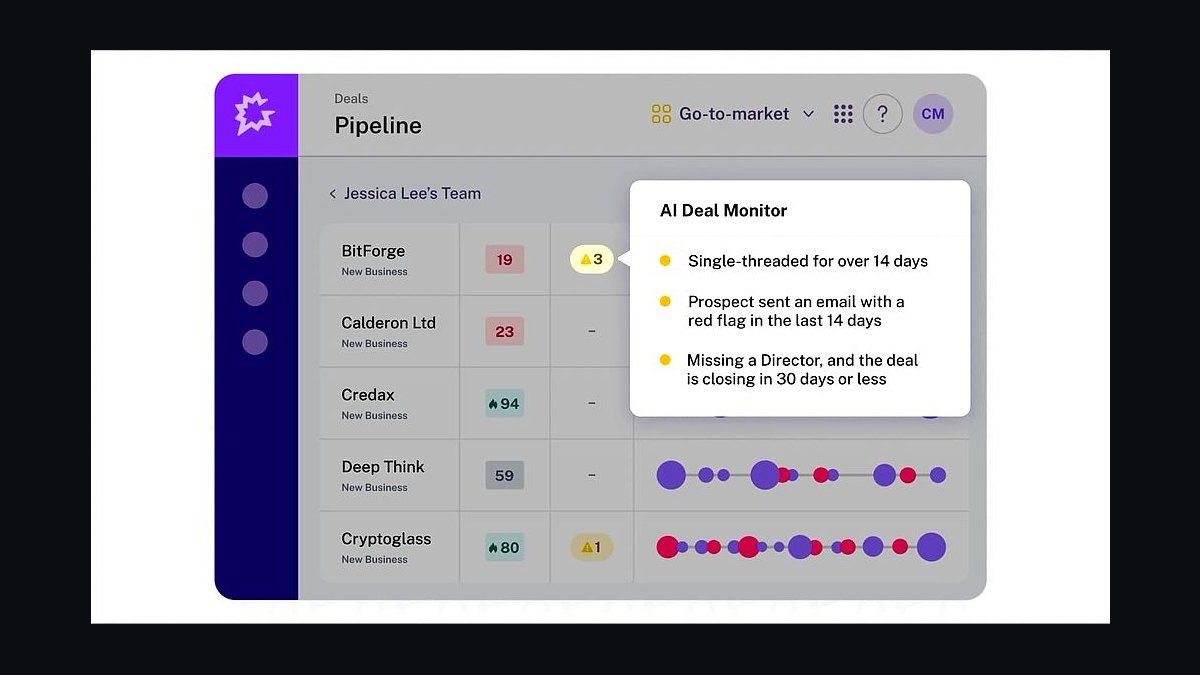
Gong ranks eighth because conversation intelligence became central to telehealth sales execution in 2027, with Gong Labs data showing reps using AI-generated talking points achieve 22% higher win rates. It scores deal risk from call sentiment and stakeholder engagement, and coaches reps on presenting audit-ready documentation during compliance-focused evaluations. For MEDDPICC enforcement, Gong reveals whether the economic buyer and clinical stakeholders were actually engaged.
It fits sales organizations with structured enablement programs and enough call volume to generate reliable coaching insights. The trade-off is scope: Gong analyzes conversations rather than forecasting revenue or managing billing, so it complements rather than replaces Clari. Compared to Clari above it, Gong owns the human conversation layer while Clari owns the predictive pipeline layer, and enterprise telehealth vendors increasingly consolidate both into a single revenue intelligence workflow.
9Vanta
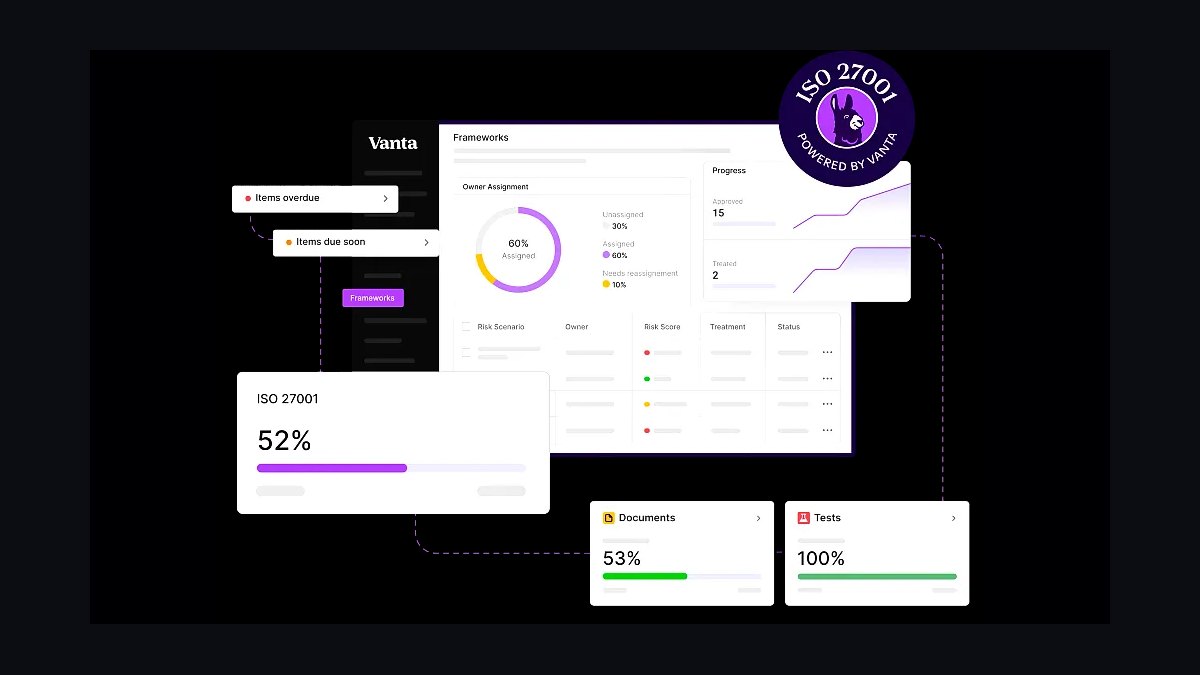
Vanta ranks ninth because SOC 2, HIPAA, and HITRUST certifications are mandatory for enterprise telehealth deals, and security reviews alone consume 4–6 weeks of the sales cycle. Vanta automates compliance monitoring and evidence collection, reducing the burden on internal teams and accelerating those reviews. In MEDDPICC deals, audit-ready documentation is often the gate that determines whether a pilot ever starts.
It fits telehealth vendors selling into hospitals, payers, and enterprise buyers where security questionnaires and certification proof are non-negotiable. The trade-off is that Vanta monitors and evidences compliance rather than replacing legal or security expertise, and it adds recurring cost before revenue arrives. Compared to Drata, its closest competitor, Vanta carries stronger brand recognition with buyers, while Drata is often cited for similar automation at comparable pricing, making the choice largely a procurement preference.
10Stripe Connect
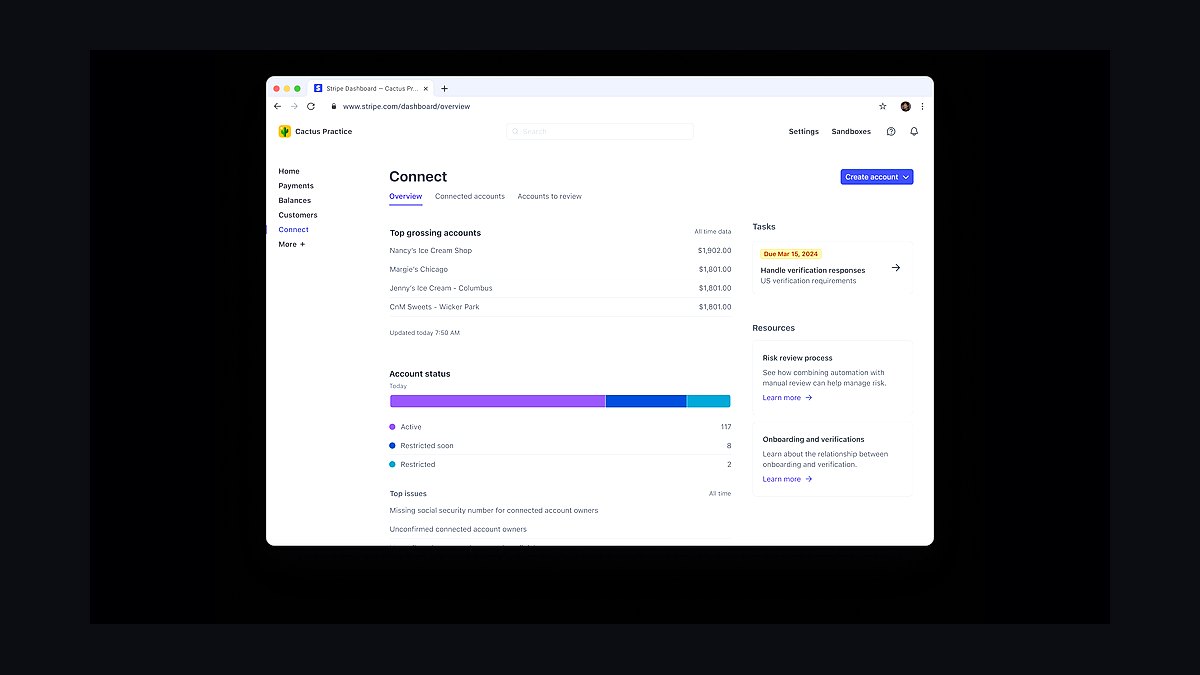
Stripe Connect ranks tenth because provider payments are the final mile of telehealth revenue operations, handling split payments between platform and clinician. It supports the complex per-visit, per-member, and subscription pricing models that telehealth requires, and it integrates with Salesforce Revenue Cloud and CPQ workflows. Without reliable payment splitting, marketplace-style telehealth platforms cannot onboard providers at scale.
It fits telehealth marketplaces and platforms paying distributed clinician networks rather than single-entity providers. The trade-off is that Connect handles payment movement, not billing compliance or CPT validation, so it must sit alongside revenue cycle tools rather than replace them. Compared to Salesforce Revenue Cloud above it, Stripe Connect owns money movement while Revenue Cloud owns pricing and billing logic, and most 2027 stacks run both together.
How we ranked these
We scored each tool across five weighted dimensions: native Epic and Cerner FHIR integration depth (25%), embedded AI capability spanning scribes, prior auth, and churn prediction (25%), compliance coverage for SOC 2, HIPAA, and HITRUST (20%), revenue-cycle and CPQ flexibility for per-visit, per-member, and subscription pricing (15%), and total cost of ownership plus integration overhead (15%). Scores came from vendor documentation, security review timelines, and buyer-reported implementation data.
We deliberately ignored brand recognition, analyst quadrant placement, and raw seat-count pricing, because none predict fit for a 4–7 person buying committee. We also excluded standalone point solutions that cannot pass a 4–6 week security review, and any tool lacking a documented Epic integration path. Marketing claims about "AI-native" architecture were discarded unless the vendor published accuracy benchmarks or audit-ready compliance artifacts.
Related questions
How does vendor consolidation change telehealth stack evaluation in 2027?
The average stack fell from 12 tools to 7 as Amwell and Teladoc bundle video, RPM, and asynchronous messaging. Buyers now weight platform depth and EHR compatibility over breadth of point features. Fewer vendors means fewer security reviews, shorter legal cycles, and lower integration overhead, but it also raises switching costs once a bundled platform owns the clinical workflow.
Which compliance certifications are non-negotiable for enterprise telehealth deals?
SOC 2 Type II, HIPAA, and HITRUST are effectively mandatory. Enterprise security reviews run 4–6 weeks and stall without them. Tools like Vanta and Drata automate evidence collection and continuous monitoring, which shortens that review window. Missing HITRUST rarely kills a deal outright, but it typically pushes signature past the quarter and into the next forecast period.
How do RevOps teams keep 8–14 month telehealth sales cycles on track?
They use Clari for AI-predicted close dates adjusted for security review delays, Gong for deal risk scoring based on call sentiment and stakeholder engagement, and Salesforce validation rules that block stage advancement until MEDDPICC fields are complete. Automated follow-ups trigger when a clinical or compliance stakeholder goes quiet for more than ten days.
What measurable impact do AI scribes have on telehealth revenue cycle performance?
Nuance DAX Copilot and Suki cut clinician documentation time by 30–50%, which raises billable visits per day. Coding accuracy improves, so claim denials drop and reimbursement cycles shorten. Buyers should demand error-rate benchmarks and specialty-specific accuracy data, because generic demo transcripts hide the performance gap that appears in behavioral health or complex chronic care.
How do buying committees score AI agents during telehealth platform evaluations?
Committees use a scorecard covering scheduling accuracy, scribe error rates, prior authorization automation success, and churn prediction precision. Clinical stakeholders weight scribe accuracy; finance weights prior auth and denial reduction; IT weights integration and security posture. Vendors that publish audited benchmarks advance faster than those offering only demo narratives.
What role does Salesforce Health Cloud play in the 2027 telehealth stack?
It anchors patient acquisition, provider management, and revenue tracking. Einstein GPT generates patient summaries, Revenue Cloud handles per-visit, per-member, and subscription billing, and MuleSoft connects Epic, Clari, and Gong. For B2B telehealth sales, Salesforce tracks buying committee members and enforces MEDDPICC fields before opportunities can advance.
Which tools dominate telehealth revenue cycle management in 2027?
Salesforce Revenue Cloud handles CPQ and billing, Stripe Connect powers split provider payments, Clari forecasts recurring and transactional revenue, and Vanta automates compliance monitoring. AI prior authorization tools cut denial rates by 30–50%. Gong coaches reps on presenting audit-ready billing workflows to compliance officers during evaluation.
How does AI churn prediction lift patient lifetime value in telehealth?
Models analyze visit frequency, engagement, and satisfaction signals to flag at-risk patients, then trigger personalized outreach, reminders, and education content. Programs typically lift retention 15–25% while generating referral opportunities. RevOps teams feed those outcomes back into Clari LTV forecasts, giving CFOs concrete evidence that retention spend pays back inside the contract term.
FAQ
What is the biggest change in the telehealth stack between 2025 and 2027?
AI agents moved from chatbots into clinical decision support, revenue cycle management, and compliance automation. In 2025, AI handled scheduling questions; by 2027, it drafts notes, checks CPT codes against payer policy, and predicts churn. Vendor consolidation accelerated alongside it, with the average stack shrinking from 12 tools to 7.
How do buying committees evaluate telehealth platforms in 2027?
They score 5–7 criteria: native Epic or Cerner integration, AI scribe accuracy against published benchmarks, SOC 2 and HITRUST certification status, a quantified ROI model covering no-show reduction and visit volume lift, and pricing flexibility across per-visit and subscription models. Gong data shows CFOs raise total cost of ownership in roughly 80% of closed-won deals.
What role does Salesforce play in the 2027 telehealth stack?
Salesforce Health Cloud serves as the central CRM for patient acquisition, provider management, and revenue tracking. Einstein GPT generates patient summaries, Revenue Cloud handles complex billing, and MuleSoft connects Epic, Clari, and Gong. For B2B telehealth sales, it tracks buying committee engagement and enforces MEDDPICC qualification fields.
How do RevOps teams manage 8–14 month telehealth sales cycles?
They combine Clari's AI-predicted close dates, adjusted for security review delays, with Gong deal risk scoring based on call sentiment and stakeholder engagement. Salesforce validation rules prevent stage advancement without completed MEDDPICC fields. Automated follow-ups trigger when clinical or compliance stakeholders disengage for extended periods, keeping stalled deals visible in forecast.
What are the top tools for telehealth revenue cycle management in 2027?
Salesforce Revenue Cloud for CPQ and billing, Stripe Connect for provider payments, Clari for revenue forecasting, and Vanta for compliance automation. AI prior authorization tools reduce denial rates by 30–50%. Gong coaches reps on presenting audit-ready billing workflows to compliance officers, which shortens the security and legal review phases.
How does AI improve patient retention in telehealth platforms?
Churn prediction models analyze visit frequency, engagement, and satisfaction scores to identify at-risk patients, then trigger personalized follow-ups, reminders, and education content. Retention typically improves 15–25% while generating referral opportunities. RevOps teams feed those outcomes into LTV forecasts, giving finance measurable proof that retention investment pays back.
What integration standard matters most for telehealth platforms in 2027?
Epic's FHIR APIs. Platforms without native Epic integration force manual data entry, create compliance exposure, and fail clinical stakeholder scorecards. Cerner and athenahealth connectivity matters for smaller systems, but Epic remains the gatekeeper for enterprise health system deals and drives the deepest technical due diligence.
How long should buyers budget for telehealth platform implementation?
Plan for 90–120 days for enterprise deployments, including security review, EHR integration testing, and clinician training. Reps also need 90–120 days to ramp on the new stack. Vendors promising 30-day go-lives usually exclude compliance sign-off and FHIR mapping work, which is where timelines actually slip.
What pricing models are common for telehealth platforms in 2027?
Per-visit, per-member-per-month, and platform subscription with usage tiers. Enterprise health systems increasingly demand hybrid contracts blending subscription base with transactional overage. Salesforce CPQ and Revenue Cloud support this complexity, but buyers should confirm the vendor can invoice split provider payments through Stripe Connect without custom development.
Which metrics prove telehealth ROI to a CFO during evaluation?
No-show rate reduction, billable visit volume lift, denial rate decline, and documentation time saved per clinician. CFOs want these tied to a payback period inside the contract term. Vendors that present a modeled ROI calculator with customer-verified inputs advance faster than those offering generic case studies.
Sources
- https://www.gong.io/labs/
- https://www.gartner.com/en/industries/healthcare
- https://www.forrester.com/research/
- https://www.mckinsey.com/industries/healthcare/our-insights
- https://www.salesforce.com/health/
- https://www.clari.com/
- https://www.epic.com/software/
- https://www.hhs.gov/hipaa/index.html
- https://stripe.com/industries/healthcare
- https://www.hitrustalliance.net/
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Seed-Stage Startups in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Personalized Learning Platforms in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Real Estate Brokerages in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Restaurant Operators in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Data Observability Teams in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Nonprofit Operations Teams in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Solo Freelance Web Developers in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for K-12 School Districts in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Luxury Hotels and Concierge Services in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Customer Support Teams in 2027