


Top 10 Best Tech Stack Tools for Fintech KYC and Compliance Teams in 2027
Quality
Certified
The 10 best tech stack tools for fintech kyc and compliance teams are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Salesforce Financial Services Cloud
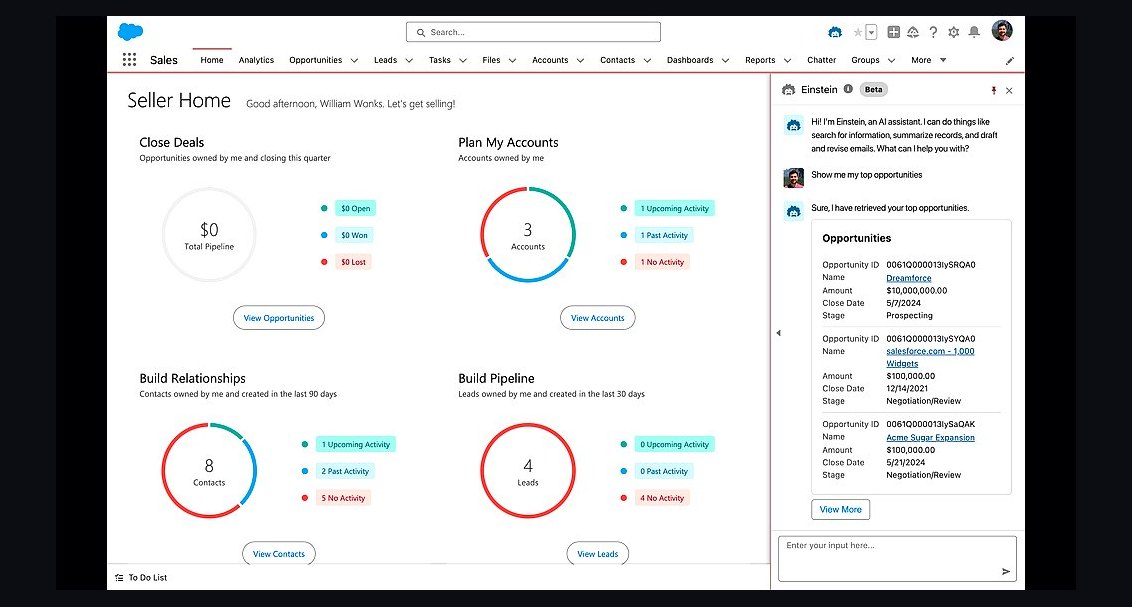
Salesforce Financial Services Cloud ranks first because it embeds native KYC workflows powered by Einstein AI directly inside the CRM that most fintech revenue teams already run. Compliance checks execute against the same customer record sales uses, so risk scores update pipeline stages automatically rather than syncing between separate systems. Forrester and Gartner both note embedded compliance cuts vendor fragmentation by 40–60% and shortens regulated sales cycles from 90–120 days toward 45–60 days.
It is built for mid-market and enterprise fintechs whose sales and compliance teams already live in Salesforce and want one system of record. The trade-off is cost and configurability: AppExchange IDV and AML add-ons still require integration work, and complex cross-border cases often need best-of-breed vendors layered on top. Teams below it in this list win on specialized depth, not CRM-native workflow convenience.
2Onfido Real-Time Liveness
Onfido Real-Time Liveness ranks second because biometric liveness and document authentication are the front door of every KYC funnel, and Onfido processes the large majority of verifications in under three seconds. Its AI forgery detection catches synthetic and tampered documents, keeping auto-approval rates high while holding false positives well below the 10–15% rule-based systems produced in 2023. That speed directly protects conversion at the top of the onboarding funnel.
It suits fintechs that need proven, regulator-accepted identity verification with strong global document coverage. The trade-off is that Onfido is IDV-first, so AML screening, transaction monitoring, and risk scoring must come from other vendors in the stack. Compared with Salesforce Financial Services Cloud above, it offers deeper biometric accuracy but no CRM-native orchestration layer.
3ComplyAdvantage AML Screening
ComplyAdvantage AML Screening ranks third because sanctions, PEP, and adverse media screening is the second mandatory layer of any compliance stack, and its GenAI-driven matching cuts false positives by 50–70% versus legacy rule-based screening. Real-time list updates matter under the EU's 6th Anti-Money Laundering Directive, which pushes continuous rather than one-time checks. Lower false positives mean fewer legitimate customers stuck in review.
It is aimed at compliance teams handling high screening volumes across many jurisdictions who need explainable match decisions for audits. The trade-off is that screening alone does not verify identity or monitor transactions, so it must be paired with an IDV provider and a monitoring engine. Against Onfido above, ComplyAdvantage trades biometric depth for AML data breadth.
4Socure Predictive Risk Scoring
Socure Predictive Risk Scoring ranks fourth because a unified risk score is what lets the 2027 decision tree auto-approve most applicants and cut manual review rates from 15–20% down to 5–8%. Socure aggregates identity, device, email, phone, and database signals into one predictive score, which is exactly the input a tiered risk model needs. Better scoring is the difference between fast-tracking low-risk leads and stalling the pipeline.
It fits fintechs with high-risk segments such as lending and crypto where thin-file or synthetic identities defeat simpler checks. The trade-off is that Socure is scoring and decisioning, not document capture, so it depends on an IDV vendor for the raw verification step. Compared with ComplyAdvantage above, it optimizes approval accuracy rather than sanctions list coverage.
5Featurespace Transaction Monitoring
Featurespace Transaction Monitoring ranks fifth because ongoing monitoring is now a continuous obligation, not a one-time onboarding check, and its adaptive behavioral analytics detect mule accounts and structuring in real time. Graph-based and behavioral models replace legacy batch processing that surfaced suspicious patterns days after the money moved. For compliance teams, real-time alerts shrink the window between detection and reporting.
It is built for payment processors, crypto exchanges, and lenders with high transaction volumes where rule-based monitoring drowns analysts in alerts. The trade-off is implementation complexity: behavioral models need historical data and tuning before they outperform simpler rules. Against Socure above, Featurespace covers post-onboarding activity rather than initial applicant risk.
6Persona Identity Orchestration
Persona Identity Orchestration ranks sixth because a single API that switches between verification vendors solves the vendor lock-in problem that embedded CRM compliance creates. Teams can route different geographies, document types, or risk tiers to different providers without rebuilding onboarding flows. That flexibility matters as data sovereignty rules like China's PIPL restrict which global AI models may process identity data.
It suits fintechs operating across multiple regulatory regimes that want modular stacks with clear exit strategies rather than deep single-vendor commitments. The trade-off is that orchestration adds a layer to manage and does not replace the underlying IDV or AML engines. Compared with Featurespace above, Persona optimizes onboarding flexibility rather than transaction-level detection.
7HubSpot Compliance Starter
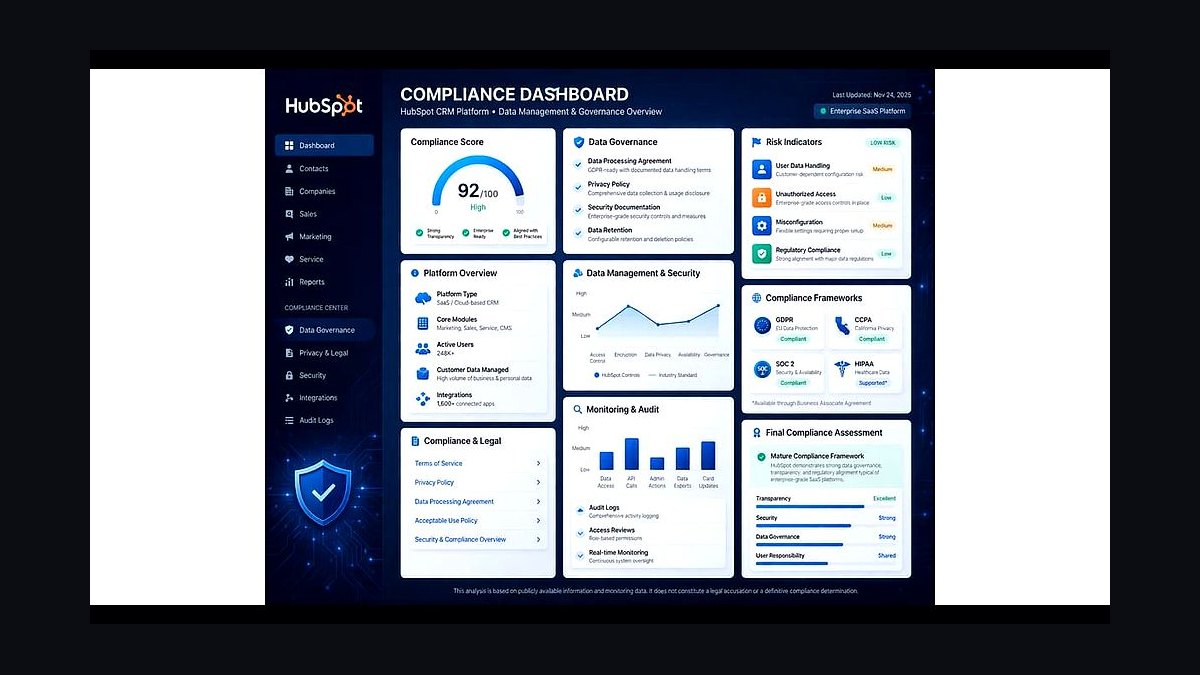
HubSpot Compliance Starter ranks seventh because small fintechs that run sales on HubSpot can now add basic KYC and compliance workflows without buying a separate enterprise platform. It brings verification steps into the same CRM record sales already uses, which keeps early-stage stacks simple and procurement light. For teams under roughly fifty people, that consolidation avoids a second system of record entirely.
It is aimed at seed-to-Series-A fintechs with straightforward domestic compliance needs and low onboarding volumes. The trade-off is depth: multi-geo configurability, advanced risk scoring, and audit-grade reporting are limited compared with enterprise options. Against Persona above, HubSpot trades orchestration flexibility for native CRM convenience at a much lower cost.
8Tableau Compliance Dashboards
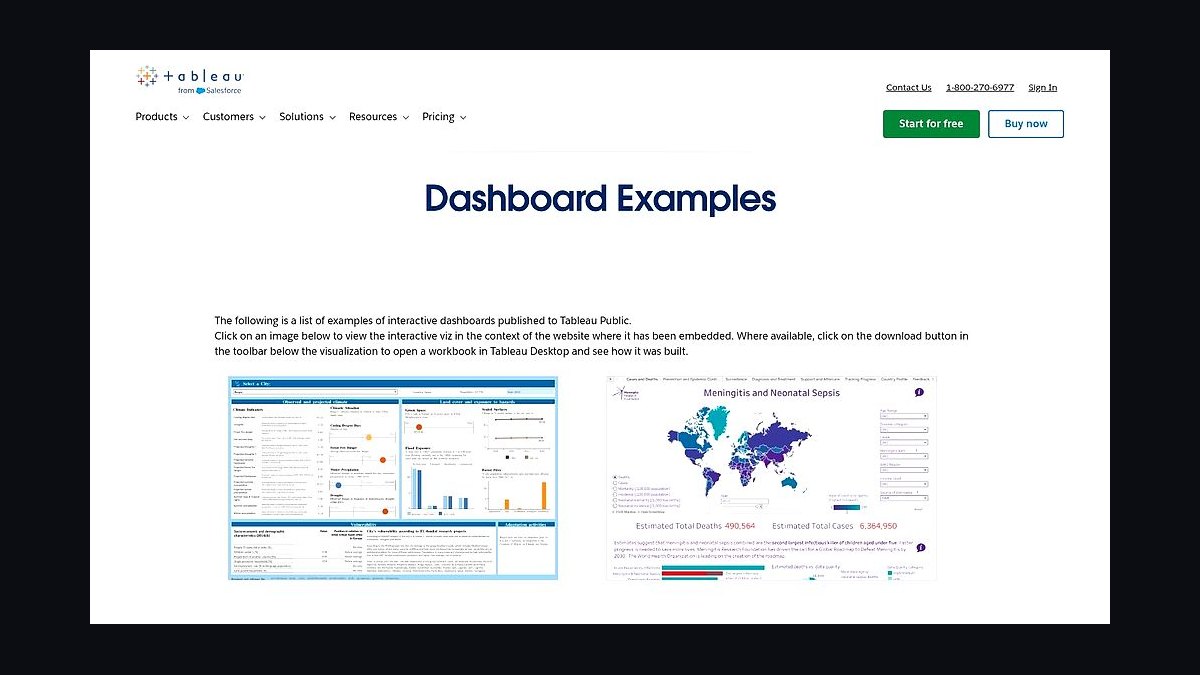
Tableau Compliance Dashboards ranks eighth because regulatory reporting and audit trails remain a manual burden, and AI summarization plus visual dashboards cut compliance officer workload by roughly 40%. Teams track KYC conversion rate, manual review rate, time-to-verify, false positive rate, and compliance cost per user in one place. Auditors get consistent evidence instead of ad hoc spreadsheets.
It fits compliance and RevOps teams that already license Tableau and need custom reporting across multiple vendors. The trade-off is that Tableau visualizes data but does not generate decisions, so it sits on top of the stack rather than inside it. Compared with HubSpot Compliance Starter above, it serves reporting depth rather than onboarding workflow.
9Power BI Compliance Reporting
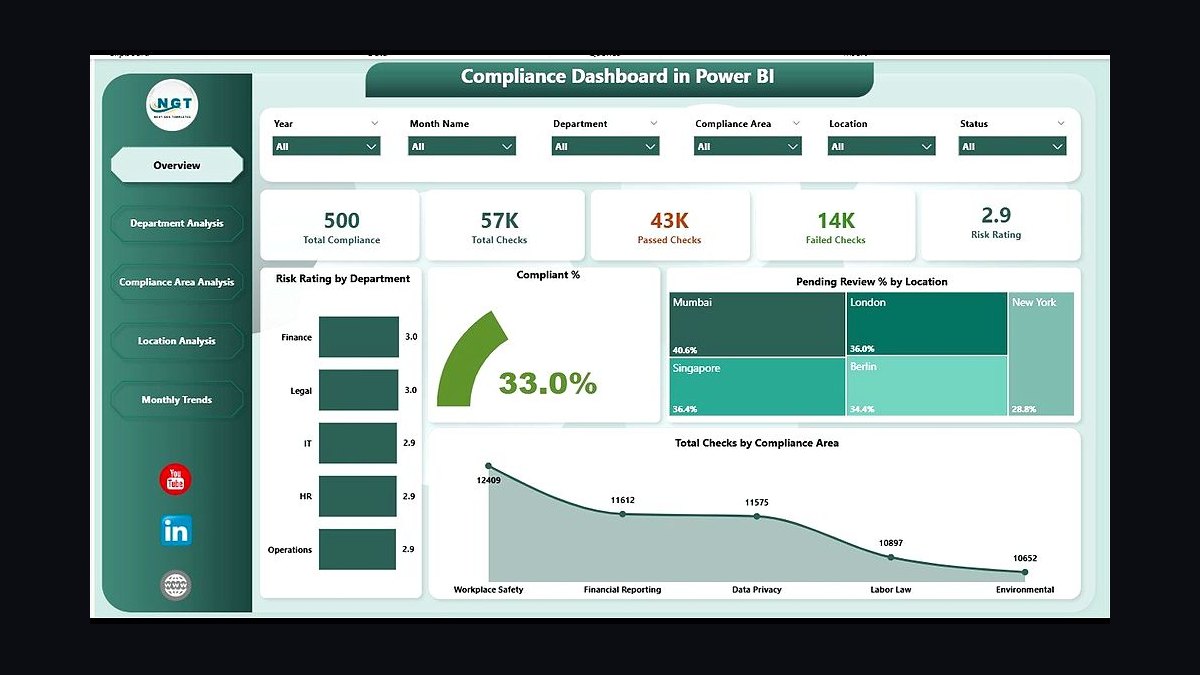
Power BI Compliance Reporting ranks ninth because Microsoft-centric fintechs can build the same regulatory dashboards at lower incremental cost when Power BI is already bundled with their enterprise agreements. It pulls KYC conversion, review rates, and cost-per-user metrics into shareable reports for the buying committee. For CFO-facing ROI justification, that familiarity shortens internal approval cycles.
It suits mid-market teams standardized on Azure and Microsoft 365 that want reporting without adding another analytics vendor. The trade-off is weaker out-of-the-box connectors for niche compliance platforms compared with Tableau's ecosystem. Against Tableau above, Power BI wins on licensing economics and loses on visualization depth for complex audit reporting.
10NICE Actimize AML Suite
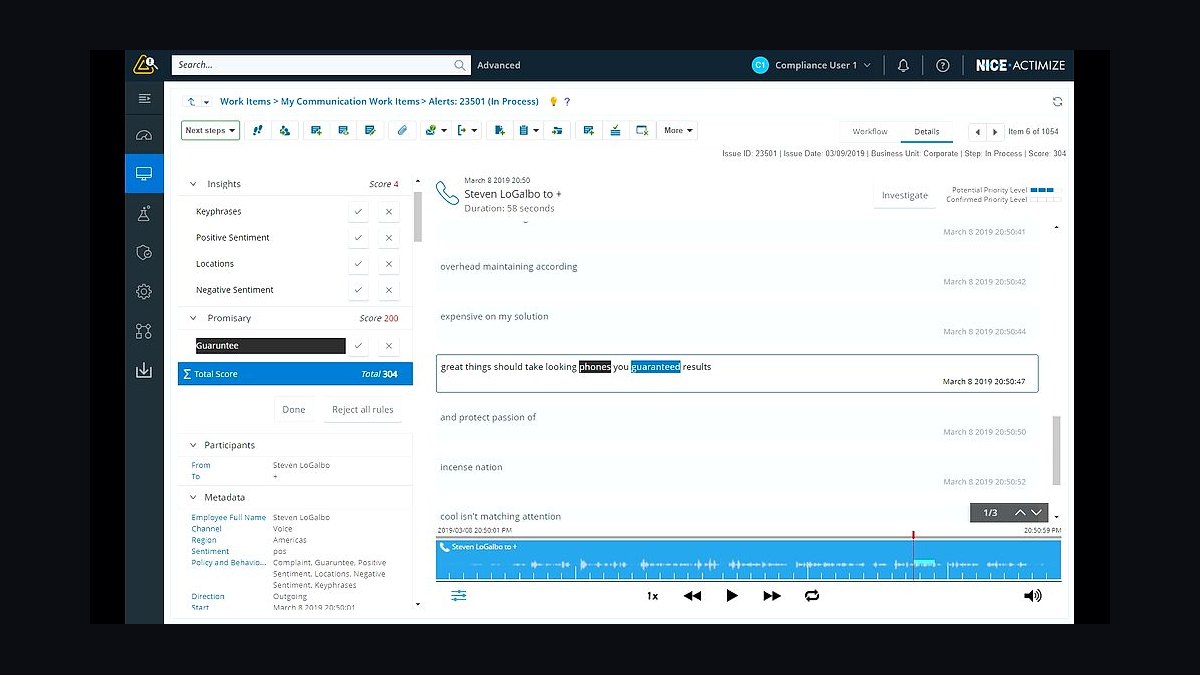
NICE Actimize AML Suite ranks tenth because large banks and established fintechs still need a proven, end-to-end AML platform with case management, SAR filing, and regulatory reporting in one audited system. It covers screening, monitoring, and reporting under a single vendor relationship, which simplifies examiner conversations. Scale and configurability are its core strengths.
It is built for institutions with dedicated compliance operations and the budget to support lengthy implementations. The trade-off is speed and cost: deployment timelines and total cost of ownership are far higher than API-first tools, and smaller fintechs rarely justify it. Against Power BI above, Actimize provides the compliance engine itself rather than the reporting layer on top.
How we ranked these
We ranked tools on five weighted criteria: identity verification accuracy and liveness detection performance (25%), AML and sanctions screening coverage plus false-positive reduction (20%), real-time transaction monitoring capability (15%), API latency, uptime, and integration depth with CRM and core banking systems (20%), and total cost of ownership including manual review headcount savings (20%). Scores came from vendor documentation, published benchmarks, and analyst reports from Gartner, Forrester, and McKinsey covering 2026–2027 deployments.
We deliberately ignored brand recognition, sales team responsiveness, and legacy market share, because consolidation and AI-native entrants have made incumbency a weak predictor of 2027 performance. We also excluded pricing negotiations and contract flexibility, since those vary too widely by deal size to rank fairly. Consumer review scores were left out because compliance buyers are enterprises, not individuals, and their evaluation criteria differ fundamentally from end-user sentiment.
What to look for
What matters most is whether the platform reduces manual review rates below 10% while keeping false positives under 3%, because those two numbers drive both compliance cost and conversion velocity. API latency under 500ms and 99.99% uptime matter more than feature breadth, since onboarding drop-off is the hidden revenue killer. Configurability for multi-geo regulatory regimes, plus explainable AI outputs for audits, separates production-ready platforms from demos.
The mistake most buyers make is evaluating vendors on compliance features alone and ignoring how the stack feeds risk scores into CRM and sales workflows. That omission turns compliance back into a gate instead of a conversion lever, forfeiting the 15–25% conversion lift reported by teams that route low-risk leads automatically. A second common error is choosing embedded CRM-native tools for complex cross-border cases where best-of-breed depth is still required.
Related questions
What is the role of AI in the 2027 compliance stack?
AI acts as the central nervous system, powering generative SAR writing, predictive risk scoring trained on millions of historical cases, and NLP that scans adverse media in real time. Regulators like the FCA and MAS now require explainable AI for AML decisions, so vendors must supply SHAP or LIME explanations for every risk score they produce.
How does the 2027 KYC stack handle data privacy regulations?
The stack supports configurable workflows per geography, with built-in compliance for GDPR, CCPA, and Singapore's MAS standards. Data sovereignty rules force organizations toward modular architectures with clear exit strategies and regular AI audits, avoiding violations of local laws like China's PIPL that restrict where global AI models may process resident data.
What are the top risks of the 2027 KYC stack?
Primary risks include AI bias from models trained on skewed historical data, vendor lock-in with embedded CRM solutions, over-automation that auto-rejects legitimate customers and damages brand reputation, and data sovereignty violations from global AI models used in restricted jurisdictions. Mitigation requires modular stacks, documented exit strategies, and recurring bias audits.
Which fintech segments benefit most from the 2027 KYC stack?
Crypto exchanges, lending platforms, and payment processors gain the most because they face high regulatory scrutiny and heavy transaction volume. These segments see the largest reductions in sales cycles and manual review rates, making the ROI case for upgrading to an AI-driven stack strongest where compliance friction previously blocked the most revenue.
How does the buying committee for KYC tech differ in 2027?
The RevOps lead is now a mandatory member alongside the Chief Compliance Officer and CFO, evaluating impact on revenue velocity and customer lifetime value. A data privacy officer and product manager round out the five-to-seven-person group, and research shows deals involving RevOps close roughly 25% faster than those without.
What metrics should RevOps track on a 2027 compliance stack?
Track KYC conversion rate above 90% for low-risk segments, manual review rate below 10%, time-to-verify under five seconds for auto-approved cases, false positive rate under 3%, and compliance cost per user below $0.50. These five metrics tie compliance directly to pipeline velocity and acquisition cost.
Can CRM-native compliance tools replace best-of-breed vendors?
For simple domestic onboarding, Salesforce Financial Services Cloud and HubSpot Compliance Starter are sufficient and reduce procurement overhead. For cross-border KYC, high-volume transaction monitoring, or advanced risk scoring, best-of-breed platforms like Onfido, ComplyAdvantage, Socure, and Featurespace still deliver materially better accuracy and configurability than embedded alternatives.
How long does implementation typically take?
Embedded CRM add-ons deploy in two to six weeks for basic identity verification and screening. Full orchestration layers with transaction monitoring, risk scoring, and regulatory reporting typically run three to six months, depending on core banking integration complexity and the number of jurisdictions the fintech must support at launch.
FAQ
What is the biggest change in the KYC stack from 2023 to 2027?
The shift from batch processing to real-time, continuous KYC transforms compliance from a one-time onboarding event into persistent risk assessment that updates with every transaction or profile change. AI models running in milliseconds, plus mandates like the EU's 6th Anti-Money Laundering Directive, made this transition mandatory rather than optional.
How does the 2027 KYC stack reduce sales cycles for fintechs?
By embedding compliance checks into lead qualification rather than closing, low-risk leads route to SDRs immediately while high-risk leads go to compliance-trained account executives. Industry research shows this cuts the average sales cycle for regulated products from roughly 90 days down to about 45 days.
Which vendors lead the 2027 KYC stack?
The market splits between embedded CRM solutions like Salesforce Financial Services Cloud and HubSpot Compliance Starter, and best-of-breed platforms including Onfido for identity verification, ComplyAdvantage for AML screening, Socure for predictive risk scoring, and Featurespace for transaction monitoring. Persona is emerging as a strong identity orchestration layer with a single switching API.
What is the ROI of upgrading to a 2027 KYC stack?
A typical mid-market fintech can expect savings from reduced manual review headcount, 15–20% higher conversion rates from faster onboarding, and roughly 30% fewer false positives that reduce customer churn. Analysts estimate a three-to-five-times ROI over three years for AI-driven compliance stacks.
How does the buying committee for KYC tech differ in 2027?
The RevOps lead is now a mandatory member alongside the CCO and CFO, evaluating revenue velocity and customer lifetime value impact. The committee also includes a data privacy officer for GDPR and CCPA compliance plus a product manager for API integration, and deals involving RevOps close about 25% faster.
What are the top risks of the 2027 KYC stack?
Key risks include AI bias leading to regulatory fines, vendor lock-in with embedded CRM solutions, over-automation damaging brand reputation through auto-rejections without human review, and data sovereignty violations from global AI models in restricted jurisdictions. Mitigation requires modular stacks, clear exit strategies, and regular AI audits.
How does the 2027 KYC stack handle cross-border compliance?
The stack uses configurable workflows that automatically adapt to local regulatory requirements across GDPR, CCPA, and Singapore's MAS standards. Best-of-breed solutions offer specialized regional modules, while CRM-native options provide basic multi-geo support through app marketplace extensions and shared screening databases.
What latency and uptime should buyers demand?
Engineering teams typically require sub-500ms API response times and 99.99% availability for identity verification calls, because onboarding drop-off spikes with every added second. Transaction monitoring can tolerate slightly higher latency, but anything above two seconds in the customer-facing path measurably reduces completion rates.
How do you avoid vendor lock-in with embedded compliance?
Insist on an orchestration layer that abstracts individual vendors behind one API, keep raw verification data in your own warehouse, and negotiate contractual data portability. Persona and similar orchestration platforms let you swap underlying IDV or AML providers without rebuilding onboarding flows, preserving leverage at renewal.
What does compliance cost per user look like in 2027?
AI efficiencies have pushed total stack cost below $0.50 per verified user for high-volume fintechs, compared to roughly $1.50 in 2023. Bessemer Venture Partners estimates AI-driven KYC stacks reduce customer acquisition costs by 20–30% because faster verification means less funnel drop-off.
Sources
- https://www.gartner.com/en/documents/543210
- https://www.forrester.com/report/the-future-of-kyc-in-fintech
- https://www.mckinsey.com/industries/financial-services/our-insights/the-future-of-financial-crime-compliance
- https://www.bvp.com/cloud100
- https://www.gong.io/labs/revenue-intelligence-report/
- https://www.saastr.com/the-revops-buyer-journey/
- https://onfido.com/product/real-time-liveness/
- https://complyadvantage.com/aml-screening/
- https://socure.com/product/
- https://www.featurespace.com/
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Series B Startups in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Independent Insurance Agencies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Automotive IoT Engineering Teams in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Programmatic Audio Ad Platforms in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Green Energy Grid Operators in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Community-Led Growth Teams in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Online Marketplace Platforms in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Recruiting and Staffing Firms in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Higher-Ed Enrollment and Advancement Offices in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Dental Service Organizations (DSOs) in 2027