


How do you negotiate a complex enterprise contract when the buyer has more leverage than you in 2027?
Quality
Certified
When the buyer holds more leverage in a 2027 enterprise negotiation, stop competing on price and start competing on risk. Map the buyer's internal approval chain, quantify the cost of no decision, trade concessions for multi-year term and reference rights, and anchor on total cost of ownership rather than unit price. Leverage is rarely absolute — it is borrowed from alternatives.
What it is and why it matters
A complex enterprise contract negotiation in 2027 is not a single conversation about price. It is a multi-threaded process spanning procurement, legal, security, finance, and the economic buyer, often running 90 to 180 days across four to seven distinct approval gates. When the buyer has more leverage — because they are a marquee logo, because your competitor is already incumbent, because your pipeline is thin that quarter, or because their spend represents a large share of your ARR — the naive response is discounting. That response is almost always wrong, because it converts a structural problem into a margin problem and teaches the buyer that pressure works.
Why does leverage asymmetry matter so much more in 2027 than it did five years ago? Three structural shifts. First, procurement teams are larger, more专业化, and more instrumented — most enterprise buyers now run structured scorecards, benchmark your pricing against three or more vendors, and use sourcing tools that surface your discounting history. Second, buying committees have expanded; the average enterprise software decision now involves 8 to 11 stakeholders, and any one of them can stall a deal without ever saying no. Third, CFO scrutiny of software spend has intensified, which means the buyer's own internal leverage problem — justifying the purchase — is often bigger than their leverage problem with you.
That third shift is the opening. When a buyer has more leverage, they usually also have more internal exposure. A procurement lead who squeezes you to a 40% discount still has to defend the deal to a CFO who wants to see payback inside 12 months. Your job is to make their internal defense easier, not to win the argument. The vendor who helps the buyer build their business case becomes the vendor the buyer protects.
Practically, this means reframing what you are negotiating. You are not negotiating a price. You are negotiating a risk allocation: who carries the risk of implementation failure, adoption shortfall, integration breakage, compliance exposure, and changing business conditions. Buyers with leverage push risk onto vendors because risk transfer is cheaper for them than price reduction. If you can absorb risk cheaply — through phased commitments, success-based milestones, or capped remedies — you can hold price while giving the buyer something they value more.
It also means knowing your own BATNA (best alternative to a negotiated agreement) honestly. If you have no alternative to this deal, you have no leverage, and no tactic will manufacture it. The first move in any asymmetric negotiation is to build a real alternative — a second deal in the pipeline, a smaller but profitable segment, a partner channel — so that walking away is a genuine option rather than a bluff. Buyers read desperation. A vendor with a credible alternative behaves differently in the room, and that behavior is what actually shifts the balance.
Finally, understand that enterprise leverage is time-bound. A buyer's leverage peaks at the moment your quarter closes and their fiscal year is comfortable. It collapses when their budget use-it-or-lose-it deadline approaches, when their incumbent vendor's renewal arrives, or when an internal champion's credibility depends on shipping something this year. Mapping those timing asymmetries is often worth more than any concession you could offer.
The step-by-step process
The process below is designed for deals where the buyer clearly has the stronger hand. It assumes a deal size large enough to justify 40 to 80 hours of internal preparation before the first substantive pricing conversation.
Step 1 — Build the leverage map (week 1). List every source of leverage on both sides. Yours typically includes: implementation speed, integration depth with their existing stack, a reference customer they admire, regulatory or security certifications competitors lack, and switching cost. Theirs typically includes: deal size relative to your quota, competitor quotes, incumbent relationship, multi-year commitment they could offer, and payment terms. Score each from 1 to 5. Most vendors discover they have three or four real sources of leverage they were not using.
Step 2 — Identify the real decision-maker and the real blocker (week 1-2). In enterprise deals, the person negotiating price is rarely the person who decides. Find the economic buyer — the executive whose budget line funds the purchase — and find the blocker, the stakeholder who can quietly kill the deal. Then find the champion, the person whose career benefits if this succeeds. Your negotiation strategy should be built around arming the champion, not defeating procurement.
Step 3 — Quantify the cost of no decision (week 2-3). This is the single highest-leverage artifact you can produce. Build a model showing what the status quo costs the buyer per quarter — hours wasted, revenue leakage, error rates, compliance risk. Use their numbers, not yours. A credible model showing $400K of annualized cost from inaction changes the conversation from "why should we pay $200K" to "why are we still paying $400K to wait."
Step 4 — Design a concession ladder, not a discount (week 3). List everything you can give that costs you less than it is worth to them: payment terms, implementation services, training seats, additional sandbox environments, extended pilot, quarterly business reviews, roadmap influence, logo rights, case study participation, early access. Rank by your cost and their perceived value. Never lead with price; lead with the item that has the widest gap between your cost and their value.
Step 5 — Set your walk-away and your target (week 3). Define three numbers: target (what you want), acceptable (what you will sign), and walk-away (below which the deal destroys value). Write them down before the conversation. Vendors who do not write these down concede past their walk-away roughly 30% of the time under pressure.
Step 6 — Open with framing, not numbers (week 4). The first substantive meeting should establish evaluation criteria, not price. Get agreement on what "success" means, who measures it, and by when. If you can co-author the scorecard, you have already won half the negotiation.
Step 7 — Trade, never give (weeks 4-8). Every concession is conditional: "We can do that if we can align on a 24-month term" or "That pricing works with a Q3 start and a named reference." Unconditional concessions signal that more are available.
Step 8 — Escalate deliberately (weeks 6-10). When talks stall, escalate to peers, not to threats. A VP-to-VP call that reframes the deal around business outcomes often unlocks what a rep-to-procurement call cannot.
Step 9 — Paper the deal with precision (weeks 10-16). Legal review is where leverage often shifts back. Vague terms agreed verbally get re-litigated in redlines. Keep a written summary of every agreement and send it within 24 hours of each call.
Costs, timelines, and typical ranges
Understanding what a hard-fought enterprise negotiation actually costs — in money, time, and organizational energy — prevents the most common error, which is over-investing in a deal that cannot be saved.
Timeline ranges. A mid-market enterprise deal ($50K-$150K ACV) with a leveraged buyer typically takes 90 to 120 days from first meeting to signature. A true enterprise deal ($250K-$1M+ ACV) with a formal procurement function runs 150 to 270 days. Deals involving security review, data processing agreements, or regulated industries add 30 to 60 days on their own. If your forecast assumes 60 days for a leveraged enterprise deal, you are forecasting a deal that does not exist.
Internal cost. Budget 40 to 80 hours of pre-negotiation preparation for a deal above $250K: leverage mapping, business case modeling, reference calls, security documentation, legal review of their paper. Add 15 to 25 hours of live negotiation time across all threads. At a fully loaded cost of $150-$250 per hour for the cross-functional team involved, that is $8K to $25K of internal investment before you have a signature. This number matters because it tells you when to walk away: if the maximum achievable deal value does not clear that investment by a wide margin, disqualify.
Discount ranges and what they signal. In competitive enterprise deals, expect the buyer to open with a request for 30% to 50% off list. A typical landing point for a leveraged buyer is 15% to 25% off list, plus non-price concessions. Anything beyond 30% off list usually means one of three things: your list price was fictional, your competitive position is weaker than you thought, or you are buying a logo you cannot service profitably. Multi-year commitments typically justify an additional 5% to 10% — and are almost always worth granting because they convert a one-time negotiation into a three-year annuity.
Non-price concession values. Extended payment terms (net 60 instead of net 30) cost you roughly 1% to 2% of contract value in working capital. A 90-day extended pilot costs 3% to 5% of ACV in delivery time. Adding 20 training seats costs 1% to 3%. A capped liability clause or an uptime SLA with service credits can cost 2% to 8% depending on your reliability. Knowing these numbers lets you trade precisely instead of guessing.
The cost of losing. Losing a leveraged deal you should have won costs far more than the discount you refused. If a $300K ACV deal with a 3-year term and 110% net revenue retention represents roughly $1.1M of lifetime value, refusing a 5% additional discount to protect a 2% margin point is arithmetic that does not survive contact with a spreadsheet. Run the LTV math before you dig in.
The cost of winning badly. A deal signed at 45% off list with unlimited liability, a most-favored-nation clause, and a termination-for-convenience right is not a win — it is a liability with a logo attached. These terms destroy renewals, set precedents your other customers will demand, and consume support capacity disproportionate to revenue. A deal that cannot be renewed profitably should not be signed.
Where teams get it wrong
The failure modes in asymmetric enterprise negotiations are consistent and predictable. Recognizing them in advance is most of the fix.
Mistake 1 — Treating leverage as fixed. Teams assume the buyer's advantage is permanent. It almost never is. Leverage shifts with fiscal calendars, competitor missteps, internal reorganizations, and budget cycles. A vendor who re-maps leverage every three weeks often finds a window that did not exist in week one.
Mistake 2 — Discounting before being asked. The most expensive habit in enterprise sales is pre-emptive discounting. If you open at 20% off, you have set the ceiling for the negotiation at 20% and signaled that more is available. Open at list with a clear value narrative and let them ask.
Mistake 3 — Negotiating with the wrong person. Spending three months convincing a procurement analyst who has no authority to approve anything is a common and costly error. Identify who signs and who can veto, then allocate your time accordingly.
Mistake 4 — Winning the argument, losing the deal. Being right about your value in a meeting feels good and closes nothing. Buyers with leverage do not need to be convinced; they need to be equipped to defend the purchase internally. Your job is to hand them the ammunition.
Mistake 5 — Ignoring the no-decision outcome. Most enterprise deals are not lost to competitors; they are lost to inertia. If your negotiation strategy does not include a concrete cost-of-inaction argument, you are negotiating against yourself while the real opponent — the status quo — goes unchallenged.
Mistake 6 — Conceding on terms that compound. A most-favored-nation clause, a broad audit right, or an unlimited indemnity does not just affect this deal. It becomes the template for every deal your team signs afterward. Legal concessions deserve the same scrutiny as price concessions, and often more.
Mistake 7 — Failing to secure internal alignment before the final round. Vendors frequently discover mid-negotiation that their own legal, security, or finance teams cannot support what sales has promised. Every commitment made in the room must be pre-cleared internally. Surprises at signature are how deals die at the one-yard line.
Mistake 8 — Not documenting verbal agreements. In a 150-day negotiation, memory is unreliable and personnel change. A written recap after every call, sent within 24 hours, prevents the "we never agreed to that" conversation that costs weeks.
The teams that navigate asymmetric deals well share one trait: they treat negotiation as a project with owners, artifacts, and milestones rather than as a series of conversations. That discipline is what converts a weak hand into a signed contract that both sides can live with.
Decision framework: when to choose what
Not every asymmetric deal deserves the same response. The framework below helps you choose deliberately rather than reactively.
Choose to invest and fight when: the deal is strategically important (logo, reference, market entry), your win probability is above 30%, the buyer's leverage is time-bound, and the LTV clears your internal investment by at least 3x. In this scenario, deploy the full process: leverage mapping, business case modeling, champion enablement, and a concession ladder. Be willing to go to your walk-away but not past it.
Choose to trade aggressively when: the deal is winnable but the buyer is purely price-driven and your differentiation is weak. Here, convert price into commitment — multi-year term, prepayment, volume tiers, reference rights, or expansion commitments. If the buyer will not trade anything for the discount, they are not negotiating; they are shopping, and you should price accordingly.
Choose to walk when: the required terms would set a damaging precedent, the buyer demands unlimited liability or MFN clauses you cannot support, the deal cannot be delivered profitably at any defensible price, or the internal investment exceeds a realistic LTV. Walking away from a bad enterprise contract is a strategic win, not a loss — and it is often the move that re-establishes your leverage in the next conversation.
Choose to restructure when: the deal is strategically vital but the terms are unworkable. Restructure rather than discount: phased rollout, success-based pricing, pilot-to-production conversion, or a smaller initial scope with defined expansion triggers. Restructuring preserves price integrity while reducing the buyer's perceived risk.
Choose to delay when: the buyer's leverage is clearly time-bound and your quarter does not force your hand. A deal that is 20% likely to close today at a 35% discount may be 60% likely to close in 90 days at a 15% discount. Patience is a legitimate strategy when you can afford it.
Related questions
How do you build leverage when you have none?
Build alternatives before you need them. A credible second deal in the pipeline, a partner channel, or a profitable smaller segment changes your behavior in the room. Buyers read desperation, so the fastest way to gain leverage is to genuinely not need this specific deal.
What is the cost of no decision and how do you calculate it?
It is the annualized cost of the status quo: wasted labor hours, revenue leakage, error rates, compliance exposure, and delayed initiatives. Use the buyer's own numbers, validated with their team. A credible model showing $400K of annual cost reframes the entire price conversation.
Should you ever accept a deal below your walk-away?
Rarely, and only for a defined strategic reason: market entry, a reference logo that unlocks a segment, or a platform deal with contractual expansion triggers. Document the reason in writing before signing, because below-walk-away deals have a habit of becoming the new baseline.
How do multi-year commitments change the negotiation?
They convert a one-time price fight into a three-year annuity and typically justify an additional 5% to 10% discount. They also reduce the buyer's perceived risk and your churn exposure. Trade them deliberately, and always pair them with a defined expansion mechanism.
When should legal terms stop a deal?
When they create unlimited or uncapped exposure, grant most-favored-nation pricing that resets your entire book, or permit termination for convenience after you have incurred delivery cost. These terms destroy renewals and set precedents. Walk away or restructure.
FAQ
What do you do first when the buyer clearly has more leverage? Build a leverage map. List and score every source of leverage on both sides, then identify the economic buyer, the champion, and the blocker. Most vendors discover they hold three or four real sources of leverage — integration depth, implementation speed, certifications, references — that they were not using.
Is discounting ever the right move in an asymmetric enterprise negotiation?
Only when it is traded for something of comparable value: multi-year term, prepayment, volume commitment, reference rights, or expansion triggers. Unconditional discounting teaches the buyer that pressure works and sets a precedent that follows you into every future renewal.
How long should a leveraged enterprise contract negotiation take? Expect 90 to 120 days for a $50K-$150K ACV deal and 150 to 270 days for deals above $250K with formal procurement. Security review, data processing agreements, and regulated industries add 30 to 60 days. If your forecast assumes 60 days, you are forecasting a deal that does not exist.
How do you handle a most-favored-nation clause demand? Treat it as a pricing precedent, not a legal formality. Either narrow it heavily (specific competitors, defined scope, time-limited), price it explicitly, or refuse. An unlimited MFN clause resets your entire book of business and is rarely worth the logo.
What is the biggest mistake vendors make when outgunned? Pre-emptive discounting and negotiating with someone who cannot decide. Opening below list sets your ceiling, and spending months with a procurement analyst who lacks authority wastes the one resource you cannot recover — time. Identify who signs and who can veto.
How do you protect the deal after signing? Paper every verbal agreement in a 24-hour written recap, pre-clear all commitments with internal legal, security, and finance, and build a 90-day success plan with the champion. Deals signed under pressure are the most likely to churn, so early value delivery is part of the negotiation.
Sources
- https://www.gartner.com/en/sales/insights/b2b-buying-journey
- https://hbr.org/2015/06/the-new-sales-imperative
- https://www.mckinsey.com/capabilities/growth-marketing-and-sales/our-insights
- https://www.bain.com/insights/topics/b2b-sales/
- https://www2.deloitte.com/us/en/insights.html
- https://www.forrester.com/research/
- https://www.pwc.com/us/en/services/consulting.html
- https://www.lawinsider.com/
Related on PULSE
- How do you structure a phased enterprise rollout to reduce buyer risk?
- What concessions should you never trade in a procurement negotiation?
- How do you build a business case that survives CFO scrutiny?
- When should you walk away from a large enterprise deal?
- How do you negotiate multi-year contracts without destroying renewal pricing?
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
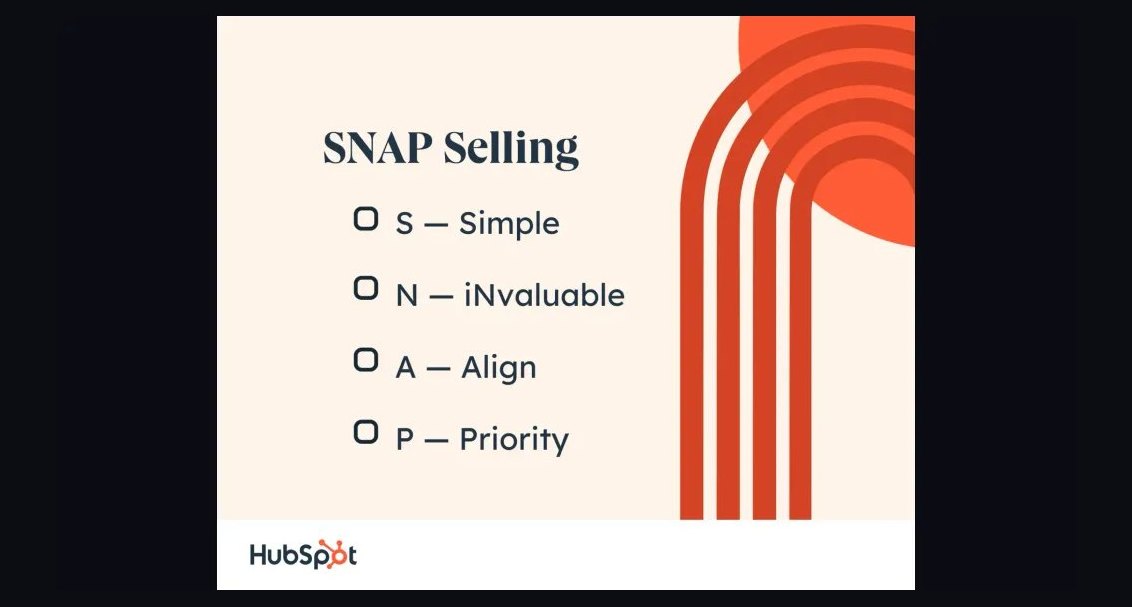 bsHow does *SNAP Selling* simplify complex sales cycles in 2027?
 bsHow do sales leaders build a repeatable outbound prospecting motion without a big SDR team in 2027?
 bsWhat’s the biggest emotional trigger *Gap Selling* says you should never ignore in a buyer conversation?
 bsWhat’s the most actionable chapter in *How to Win Friends and Influence People* for networking in 2027?
 bsHow do you use *Never Split the Difference* to handle difficult conversations with customers in 2027?
 bsWhat’s the most practical technique from *New Sales. Simplified.* for handling a “send me info” objection?
 pulse-booksWhat is the single most counterintuitive piece of advice from Think and Grow Rich for achieving financial goals in 2027?
 bsHow do you forecast sales revenue when your pipeline data keeps changing in 2027?
 bsHow do you apply *The JOLT Effect* to reduce buyer hesitation in enterprise sales?
 bsWhat’s the most actionable chapter in *How to Win Friends and Influence People* for cold calling in 2027?