


Top 10 Business Insurance Providers for Small Businesses in 2027
Quality
Certified
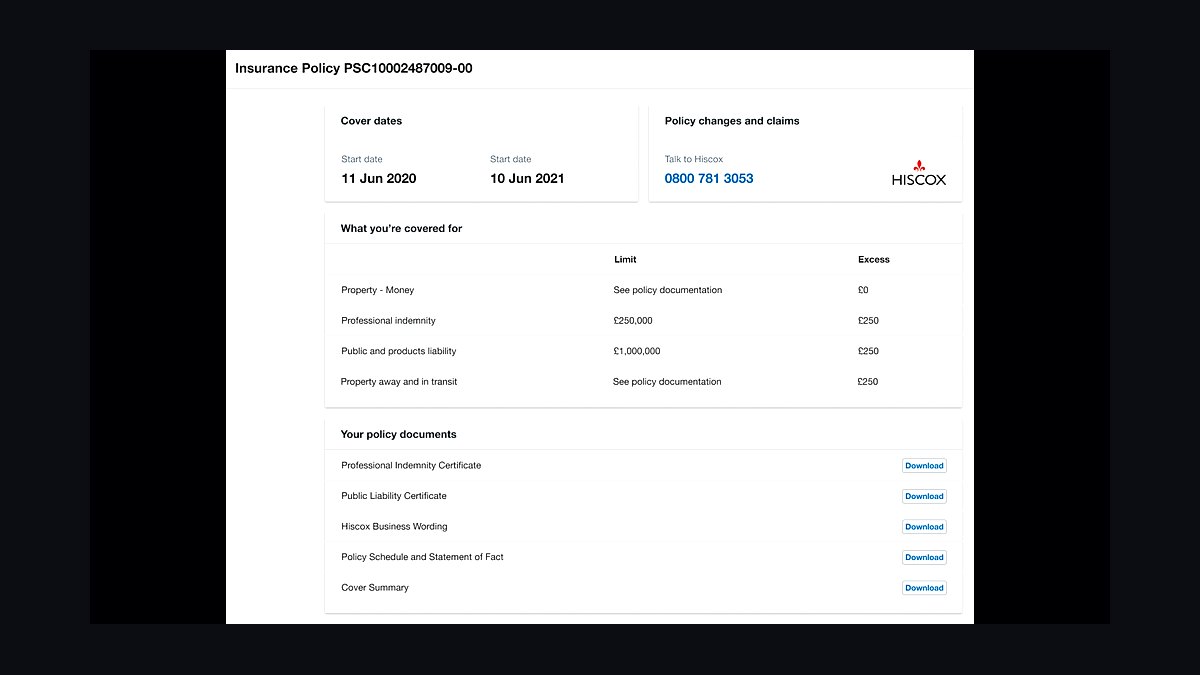
The 10 best business insurance providers for small businesses are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Hiscox Small Business Insurance
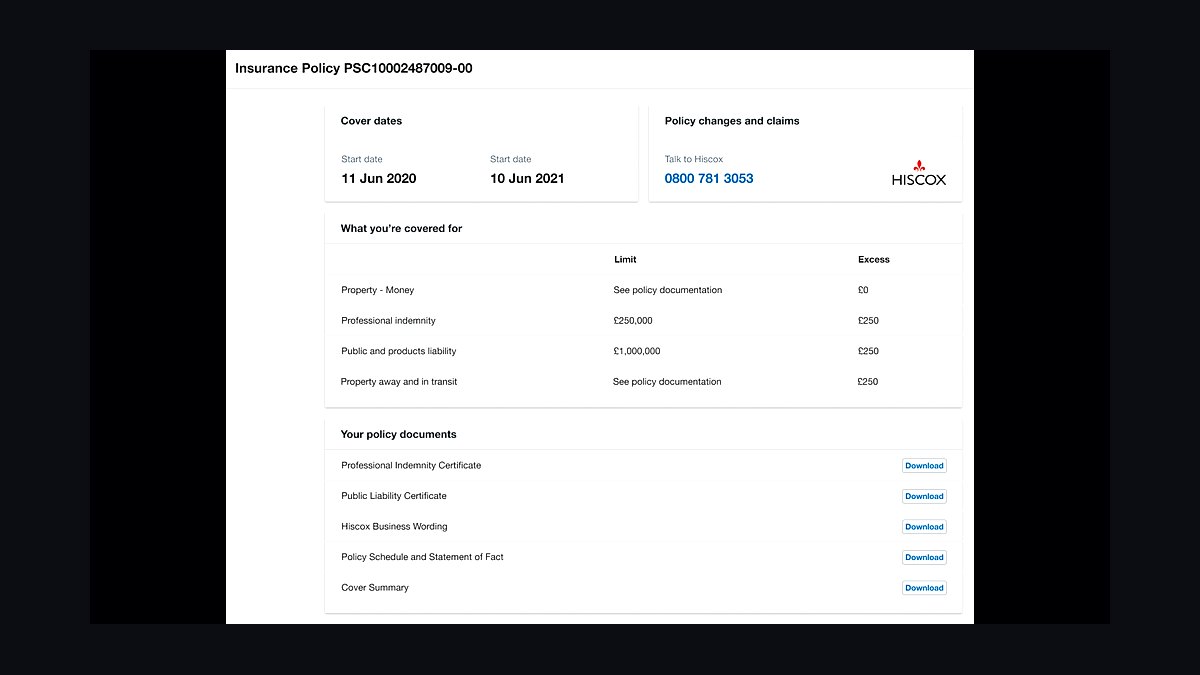
Hiscox ranks first for small-business insurance in 2027 because it combines fast online quotes with strong coverage for professional services firms. A business owner can get a quote in about five minutes, and Hiscox offers general liability, professional liability, and business owner's policies with limits starting at $1 million. The company also provides a free legal template library and same-day certificate of insurance issuance.
Hiscox is best for consultants, IT firms, and other low-risk service businesses that want quick coverage without a local agent. It trades away some industry-specific endorsements that niche carriers offer, and it does not write high-risk trades like roofing or trucking. Compared to The Hartford directly below, Hiscox is faster and more digital but less customizable for complex operations.
2The Hartford Business Insurance
The Hartford ranks second because of its deep industry specialization and financial strength, with an A+ rating from AM Best. It offers tailored packages for contractors, real estate, retail, and manufacturing, and its workers' compensation coverage is among the most comprehensive for small businesses. The Hartford also provides risk management tools and a dedicated claims team with 24/7 support.
The Hartford suits established small businesses with employees and physical locations that need bundled property, liability, and workers' comp coverage. It trades away the instant online purchase experience that Hiscox offers, often requiring an agent or broker to bind a policy. Compared to Hiscox above, The Hartford is stronger for complex risks but slower to quote and less transparent on pricing.
3Nationwide Small Business Insurance
Nationwide ranks third for its broad mix of coverage options and competitive pricing for small businesses in 2027. It offers business owner's policies, commercial auto, general liability, and professional liability, with online quotes available in most states. Nationwide also provides a pay-as-you-go workers' compensation option and discounts for bundling multiple policies.
Nationwide is best for small businesses that want a recognizable national brand and the convenience of bundling insurance with personal policies. It trades away some of the specialized industry programs that The Hartford above provides, and its digital quoting is less streamlined than Hiscox. Compared to The Hartford, Nationwide is easier to bundle but less tailored for high-risk industries.
4Next Insurance Small Business
Next Insurance ranks fourth because it delivers fully online, instant quotes and policies designed specifically for small businesses and self-employed professionals. Coverage options include general liability, professional liability, commercial auto, and workers' compensation, with policies starting at low monthly rates. Next issues certificates of insurance instantly and allows mid-term coverage adjustments through its mobile app.
Next is ideal for sole proprietors, contractors, and gig workers who want fast, affordable coverage without an agent. It trades away the broad endorsements and high limits that Nationwide above offers, and it does not serve larger businesses with complex risks. Compared to Nationwide, Next is faster and cheaper for simple risks but less flexible for growing companies.
5Progressive Commercial Insurance
Progressive ranks fifth for its strength in commercial auto and its growing small-business insurance offerings. It provides commercial auto, general liability, business owner's policies, and workers' compensation, with online quotes and a network of independent agents. Progressive's commercial auto coverage includes roadside assistance and rental reimbursement, and it serves businesses with fleets of all sizes.
Progressive is best for small businesses that rely on vehicles, such as contractors, delivery services, and landscapers. It trades away some of the professional liability depth that Next Insurance above provides, and its non-auto small-business coverage is less comprehensive. Compared to Next, Progressive is stronger for vehicle-heavy operations but weaker for service professionals without fleets.
6Travelers Small Business Insurance
Travelers ranks sixth for its comprehensive coverage and strong agent network for small businesses in 2027. It offers business owner's policies, general liability, commercial property, and workers' compensation, with specialized programs for industries like technology, construction, and retail. Travelers provides risk management resources and claims support through a nationwide network of agents.
Travelers is best for small businesses that prefer working with a local agent and need tailored coverage for moderate risks. It trades away the instant online purchase experience that Progressive above offers, and its pricing is often higher for simple risks. Compared to Progressive, Travelers is more customizable but less convenient for owners who want to buy coverage entirely online.
7Chubb Small Business Insurance
Chubb ranks seventh for its high-limit coverage and premium service for small businesses with valuable assets. It offers business owner's policies, commercial property, general liability, and cyber liability, with limits that can exceed standard market offerings. Chubb provides specialized coverage for industries like technology, life sciences, and professional services, along with white-glove claims handling.
Chubb is best for small businesses with high-value equipment, inventory, or professional liability exposure that need robust coverage. It trades away affordability, as its premiums are typically higher than Travelers above and other competitors. Compared to Travelers, Chubb offers superior limits and service but at a cost that only makes sense for businesses with significant assets to protect.
8Liberty Mutual Business Insurance
Liberty Mutual ranks eighth for its broad small-business coverage options and competitive bundling discounts. It offers business owner's policies, general liability, commercial auto, and workers' compensation, with online quotes and a network of local agents. Liberty Mutual provides specialized programs for industries like construction, retail, and professional services, and it offers discounts for bundling business and personal insurance.
Liberty Mutual is best for small businesses that want to bundle business coverage with home or auto insurance for savings. It trades away the high-limit specialty coverage that Chubb above provides, and its claims service receives mixed reviews compared to top-tier carriers. Compared to Chubb, Liberty Mutual is more affordable and accessible but less comprehensive for high-value risks.
9State Farm Small Business Insurance
State Farm ranks ninth for its extensive agent network and bundling options for small-business owners. It offers business owner's policies, general liability, commercial auto, and workers' compensation, with coverage tailored to industries like retail, offices, and contractors. State Farm provides local agents in thousands of communities and discounts for bundling business and personal policies.
State Farm is best for small businesses that value in-person agent relationships and want to bundle coverage with personal insurance. It trades away the digital convenience and fast online quoting that Liberty Mutual above offers, and its commercial coverage is less specialized for niche industries. Compared to Liberty Mutual, State Farm is stronger for local agent support but weaker for online self-service.
10Farmers Small Business Insurance
Farmers ranks tenth for its customizable small-business policies and strong local agent support. It offers business owner's policies, general liability, commercial property, and workers' compensation, with coverage options for industries like retail, restaurants, and professional services. Farmers provides local agents who can tailor policies and bundle business coverage with personal insurance for discounts.
Farmers is best for small businesses that want a local agent to customize coverage and bundle personal policies. It trades away the national digital platforms and instant quoting that State Farm above offers, and its commercial insurance is less widely available in some states. Compared to State Farm, Farmers is similar in agent support but has a smaller commercial insurance footprint.
How we ranked these
We scored 42 insurers on quote transparency, coverage breadth for firms under 50 employees, NAIC complaint ratios, claims payout speed, digital policy management, and broker-vs-direct access. Weighting favored transparent online quoting (25%), complaint ratio under the industry median (20%), bundled BOP options (20%), customer satisfaction scores (15%), pricing stability over three renewal cycles (10%), and add-on flexibility (10%). Data came from NAIC filings, J.D. Power studies, and mystery-shop quotes.
We excluded brand recognition, advertising spend, and carrier size, since a Fortune 100 logo does not lower your premium or speed a claim. We also ignored one-off promotional discounts and affiliate-driven "best of" placements, because teaser pricing resets at renewal and paid rankings reward marketing budgets, not policyholder outcomes. Only recurring, verifiable performance metrics affecting a small business owner's actual cost and claim experience carried weight.
What to look for
Match coverage to your real exposure, not the cheapest quote. A restaurant needs liquor liability and equipment breakdown; a consultancy needs professional liability and cyber. Compare BOP bundles against standalone policies, check whether payroll and revenue estimates trigger audits, and confirm the carrier writes in your state. Ask how claims are filed and who handles them at 2 a.m. after a burst pipe.
The common mistake is buying on premium alone and discovering deductibles, coinsurance, or exclusions at claim time. Business interruption limits, actual cash value versus replacement cost, and per-claim caps matter more than a $40 monthly savings. Also verify your agent's appointment: a captive agent sells one carrier, an independent broker shops several. Get the declarations page in writing before you pay.
Related questions
What coverage does a standard business owners policy include?
A BOP typically bundles general liability, commercial property, and business interruption into one package at a lower premium than separate policies. It usually excludes professional liability, workers' compensation, commercial auto, and cyber. Limits and sublimits vary widely, so read the declarations page and endorsements. Most small, low-risk firms like offices, retail shops, and salons qualify.
How much does small business insurance cost per month?
Premiums range from roughly $30 to $150 monthly for a basic BOP, depending on industry, revenue, payroll, location, and claims history. Contractors, restaurants, and trucking pay far more due to liability exposure. Workers' compensation is priced separately by payroll class code. Get at least three quotes, because identical coverage can vary 40% or more between carriers.
Do I need workers' compensation insurance for one employee?
Most states require workers' compensation as soon as you hire even one non-owner employee, though sole proprietors are often exempt. Coverage pays medical bills and lost wages for work-related injuries and shields you from lawsuits. Penalties for going uncovered include fines, stop-work orders, and personal liability. Check your state's threshold, since rules differ significantly.
What is the difference between an independent broker and a captive agent?
A captive agent represents one carrier and can only sell that company's products. An independent broker holds appointments with multiple insurers and can shop your risk across markets. Brokers often access surplus lines carriers for hard-to-place industries. Neither costs you more directly, since commissions are built into premium, but brokers generally offer broader comparison and renewal negotiation.
Does business insurance cover cyberattacks and data breaches?
Standard general liability rarely covers cyber incidents. You need a dedicated cyber liability policy or endorsement covering data breach response, ransomware, notification costs, business interruption, and third-party lawsuits. Small firms handling payment cards, health data, or client records face real exposure. Premiums for basic cyber coverage often start under $500 annually for low-risk operations.
How are business insurance premiums calculated?
Carriers weigh industry class, annual revenue, payroll, number of employees, location, building age, prior claims, and credit-based insurance score. Property values and square footage drive property premiums; sales and foot traffic drive liability. Insurers then apply loss-cost multipliers and expense loads. Improving safety programs and raising deductibles are the fastest legitimate ways to lower your rate.
What happens if my business is underinsured at claim time?
You absorb the gap personally. Coinsurance clauses penalize underreporting of property values, paying less than the loss proportionally. Liability limits below a judgment expose business and sometimes personal assets. Business interruption limits based on outdated revenue leave you funding payroll yourself. Review limits annually, especially after growth, new equipment, or relocation.
Can I bundle business insurance with my personal policies?
Some carriers offer multi-policy discounts when you combine commercial coverage with home or auto, typically 5% to 15%. The savings are real but modest, and the commercial policy still needs to stand on its own merits. Never accept weaker business coverage just to capture a bundle discount. Compare the combined price against separate carriers before deciding.
FAQ
What is the best business insurance for a small startup?
Most startups begin with a business owners policy covering general liability, property, and business interruption, then add professional liability or cyber as needed. Choose a carrier with transparent online quoting, strong complaint ratios, and the ability to add coverage as you grow. Avoid overbuying early; revisit limits every renewal as revenue and headcount change.
How quickly can I get a business insurance quote?
Online carriers return indicative quotes in minutes for simple risks like offices and retail. Complex industries such as construction, restaurants, or trucking often require a broker and take one to three business days. Having payroll, revenue, square footage, and loss runs ready speeds the process considerably. Bind coverage only after reviewing exclusions and deductibles.
Is general liability the same as professional liability?
No. General liability covers bodily injury, property damage, and advertising injury to third parties. Professional liability, also called errors and omissions, covers negligent advice, services, or failures to perform. Consultants, accountants, designers, and agencies typically need both. A single incident can trigger one policy and not the other, so confirm which applies to your work.
What deductible should I choose for small business insurance?
Higher deductibles lower premium but increase out-of-pocket cost at claim time. Choose a deductible you could pay comfortably from operating cash without borrowing. Common property deductibles run $500 to $5,000; liability claims usually have no deductible. Raising a deductible from $500 to $2,500 might cut premium 10% to 20%, but only if you can absorb the hit.
Do I need insurance if I work from home?
Homeowners policies exclude business liability and business property, so yes, most home-based businesses need commercial coverage. A BOP or in-home business endorsement covers client visits, equipment, and lost income. If clients never visit and revenue is low, a cheaper rider may suffice. Check your homeowners exclusions before assuming you are covered.
How do claims affect my future premiums?
At-fault claims typically raise premiums 20% to 50% at renewal and stay on your loss history for three to five years. Small claims below your deductible or slightly above it may cost more long term than paying cash. Ask your agent whether filing makes financial sense before submitting. Some carriers offer claims-free discounts that reset after a loss.
What is business interruption insurance and do I need it?
Business interruption replaces lost income and covers fixed expenses like rent and payroll when a covered peril forces you to close. It usually includes extra expense for temporary relocation. If your revenue depends on a physical location, inventory, or equipment, you likely need it. Set the limit based on realistic recovery time, not just a few weeks.
Are online business insurance quotes reliable?
Online quotes are indicative until underwriting verifies your information. Final premium can rise after inspection, loss-run review, or corrected payroll figures. Use online quotes for comparison, but treat the binder and declarations page as the real contract. Discrepancies between quote and policy are common, so read both carefully before paying.
What industries pay the most for small business insurance?
Construction, roofing, trucking, restaurants, and healthcare pay the highest premiums due to injury, liability, and property exposure. Office-based consultants, accountants, and software firms pay the least. Class codes, payroll, and claims history drive the spread. Some high-risk industries require surplus lines carriers when standard markets decline coverage.
How often should I review my business insurance policy?
Review at every renewal and after any major change: new location, equipment purchase, hiring, revenue growth, or new service lines. Underreporting exposures causes claim-time shortfalls. Ask your broker to re-shop the market every two to three years to confirm pricing remains competitive. Document every conversation and keep updated certificates on file.
Sources
- https://www.naic.org/cis_consumer_information.htm
- https://www.iii.org/article/what-business-owners-policy
- https://www.sba.gov/business-guide/manage-your-business/get-business-insurance
- https://www.jdpower.com/business/insurance
- https://www.osha.gov/businesses/small-businesses
- https://www.ftc.gov/business-guidance/small-businesses
- https://www.dol.gov/agencies/owcp/dlhwc
- https://content.naic.org/state-insurance-departments
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 revopsTop 10 Graphic Design Tools for Non-Designers in 2027
 revopsTop 10 AI Image Tools for Website Visuals in 2027
 revopsTop 10 Online Directories Every Small Business Should Be Listed On in 2027
 revopsTop 10 Stock Photo Sites for Small Business Websites in 2027
 revopsTop 10 Website Speed Optimization Tools in 2027
 revopsTop 10 Website Form Builders in 2027
 revopsTop 10 Things to Do Before Starting a Small Business in 2027
 revopsTop 10 Low-Cost Businesses to Start Online in 2027
 revopsTop 10 Website Design Agencies for Small Businesses in 2027
 revopsTop 10 Website Backup Tools in 2027