
Should I open or buy a Wienerschnitzel franchise in 2027?
 Curated byKory White · Fractional CRO · Maryland
 PULSEKNOWLEDGE LIBRARY
Quality
Certified
Only if you are an experienced multi-unit quick-service operator in the Sunbelt with a drive-thru pad and $400,000-plus in liquid capital. A new freestanding Wienerschnitzel franchise runs roughly $478,000 to $1.74 million, pays 9% off the top, and returns median cash flow near $126,000. First-time single-unit buyers should generally pass.
What a Wienerschnitzel franchise actually is, and why the format matters more than the brand
Wienerschnitzel is a hot-dog-led quick-service restaurant brand owned by Galardi Group, Inc., a family business founded in 1961 that has been run by the Galardi family across three generations. The system sits at roughly 325 units as of early 2026, and the geographic concentration is the single most important fact a prospective buyer needs to internalize before anything else: the overwhelming majority of units are in California, with meaningful clusters in Texas, Arizona, Nevada, and New Mexico. This is a regional brand with national ambitions, not a national brand. Every assumption you carry about franchise economics — brand-driven opening-week volume, customer familiarity with the menu, supplier density, the ability to hire a manager who has worked the concept before — is true in Southern California and false in most of the country.
The brand licenses three formats, and they are not economically interchangeable. The freestanding drive-thru is the flagship: a purpose-built pad, typically in the 1,700 to 1,900 square foot range, with a dedicated drive-thru lane. This format carries the system's volume and is what the franchisor's Item 19 average unit volume mostly reflects. The end-cap in-line format sits in a strip center, usually with a smaller footprint and either no drive-thru or a constrained one; it costs less to build and, predictably, generates less. The non-traditional format — travel plazas, stadiums, host locations inside larger retail — carries its own rules, its own host-venue rent structure, and volume that swings on the host's traffic rather than on anything you control.
If you take one thing from this section: the drive-thru is not a feature, it is the business. Quick-service hot dogs are an impulse and convenience purchase with a low average check. The category does not sustain long dwell times or destination dining. Take away the drive-thru lane and you have removed the majority of the transaction volume the pro forma assumes. Every serious Wienerschnitzel operator will tell you the same thing in a validation call: they are running a drive-thru business that happens to sell chili dogs.
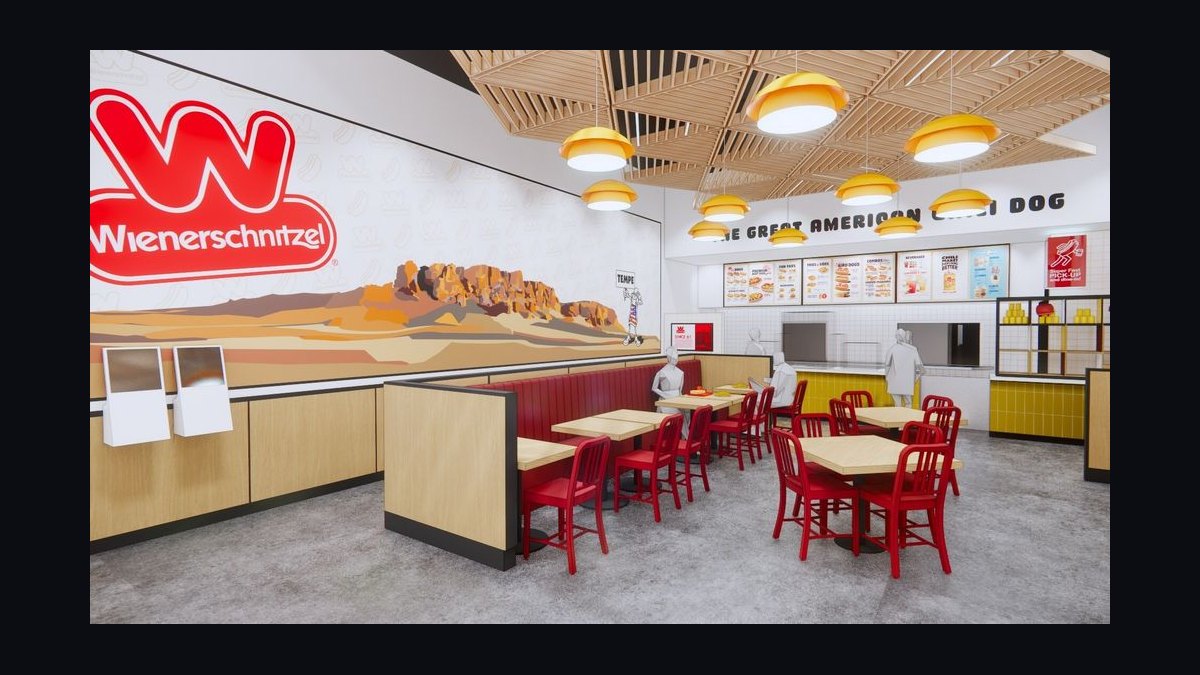
Why this matters for the 2027 decision specifically: Galardi Group has publicly stated an aggressive growth target — a push toward 500 units by 2030, up from the low 300s — and is offering reduced fees on second and subsequent units plus multi-unit development incentives to get there. Franchisor growth targets are a double-edged instrument for a buyer. They mean available territory, real development incentives, and franchisor attention. They also mean the franchisor is motivated to approve sites and candidates it might have declined in a flat year. Your diligence has to be *more* rigorous during a growth push, not less, because the franchisor's screening function is being relaxed at exactly the moment you would most like it tightened.
There is also a RevOps lens worth naming, because it is the honest way to evaluate any multi-unit operating business: a franchise is a revenue system with a fixed cost of goods, a semi-fixed labor model, a contractually fixed royalty stack, and a variable you control almost entirely through site selection. Most buyers spend 80% of their diligence energy on the brand — the menu, the logo, whether they personally like the food — and 20% on the site. The returns run the other way. Two Wienerschnitzel units with identical franchise agreements, identical menus, and identical build specs can differ by a factor of two in annual volume purely on traffic counts, ingress geometry, and daytime population. Underwrite the site, then the brand.
The step-by-step process from first inquiry to open doors
The path from "I am curious" to "I am open" runs 12 to 18 months for a new freestanding build, and the diligence window inside that — the part where you can still walk away cheaply — is the first 90 days. Here is the sequence, with the specific action at each stage.
Stage 1 — Request the Franchise Disclosure Document (days 1 to 10). You submit an inquiry through the brand's franchising site and complete a confidential personal profile covering net worth, liquid capital, operating experience, and target markets. Under the FTC Franchise Rule, the franchisor must give you the FDD at least 14 calendar days before you sign anything or pay any money. Read four items in particular. Item 7 is the estimated initial investment table, which is where the low-to-high range comes from. Item 19 is the financial performance representation — average unit volume and whatever segmentation the franchisor chooses to disclose. Item 20 is the unit count table plus the three-year record of openings, closures, terminations, transfers, and non-renewals, and it is the single most diagnostic page in the document. Item 21 is the franchisor's own audited financials, which tell you whether the entity backing your 20-year agreement is solvent.
Stage 2 — Validate with existing franchisees (days 11 to 25). Item 20 includes a contact list of current franchisees and, separately, of franchisees who left the system in the last fiscal year. Call both lists. Target 8 to 12 conversations, weighted toward operators whose market resembles yours — do not validate a Kansas City project by calling three Orange County legacy operators whose units have been open since the 1980s and whose rent is a fossil. Ask three questions and write the answers down verbatim: What was your trailing-twelve-month sales volume? What was your store-level EBITDA as a percentage of sales? Knowing what you know now, would you sign this agreement again today? That last question is the whole exercise. If materially fewer than seven in ten say yes, you have your answer and you have spent nothing.
Stage 3 — Site analysis (days 26 to 45). Franchisors run site approval using commercial traffic and demographic data. Run your own in parallel rather than accepting theirs. The physical non-negotiables for this format: a drive-thru lane that stacks at least 8 cars without spilling into the parking field or the street; clear pad visibility from the arterial road with long sight lines; and workable ingress, ideally including a left-turn-in, because a pad that can only be entered from one direction loses roughly half its passing traffic. On the demographic side, you are looking for adequate daytime population within a 3-mile radius, household income that supports a value-priced QSR, and a competitive set you can actually beat on speed rather than on price.
Stage 4 — Build the model (days 46 to 60). Build it in a spreadsheet you control, not the franchisor's. Use the median disclosed volume, never the top-quartile number. Model food and paper around 30% of sales, labor at 28% to 30% in Sunbelt markets and materially higher in California, occupancy around 8%, royalty at 5%, and total marketing at 4%. Then run the sensitivity: rebuild the model at bottom-third volume. If the unit does not at least cover debt service and your own draw at bottom-third volume, the deal is not financeable in any honest sense — it is a bet that you land above median in a system where by definition half of units do not.
Stage 5 — Financing (days 61 to 75). Established franchise brands typically appear on the SBA Franchise Directory, which makes SBA 7(a) financing the default structure for a single-unit build. Pre-qualify with at least two SBA-active lenders before you sign the franchise agreement, not after. Expect a meaningful personal equity injection, a full personal guarantee, and a lien on any real estate you own. Lenders will underwrite the *format* as well as the brand — a freestanding pad with a drive-thru finances more easily than an in-line unit precisely because the collateral and the volume history are better.
Stage 6 — Sign or walk (days 76 to 90). Four gates: validation confirmed the disclosed volumes, the site passed your own analysis and the franchisor's, the model clears your cash-flow threshold at median volume and survives at bottom-third, and financing is committed in writing. All four pass, you sign. Any one fails, you walk. There is no deal urgency that justifies a 20-year contract with a personal guarantee on incomplete diligence, and any pressure to move faster than this is itself a data point.
Costs, timelines, and the ranges you should actually budget
The disclosed all-in range for a new freestanding Wienerschnitzel runs roughly $478,200 on the low end to $1,737,700 on the high end. That spread is not noise and it is not a hedge — it is almost entirely real estate and construction. Understanding which end of it you are on is the most consequential number in the entire analysis.
The initial franchise fee is in the tens of thousands, with the brand's current incentive structure pricing the first unit higher than subsequent units — a deliberate lever to convert single-unit buyers into multi-unit developers. Real estate and site work is where the range explodes: a ground lease on an existing pad in a secondary market versus buying dirt and building from scratch on a hard corner in a coastal metro is a six-figure-to-seven-figure swing. Building and leasehold improvements for a new-build freestanding unit sit at the top of the range; converting an existing restaurant shell with usable infrastructure sits far lower. Equipment, signage, point-of-sale, and drive-thru technology is a substantial block on its own and is largely non-negotiable — the drive-thru timing system, the menu boards, the fryer and steam-table line, and the digital ordering stack are specified by the franchisor.
Three lines get systematically under-budgeted by first-time buyers.
Working capital. The disclosed range covers roughly three months, and the top of that range is there for a reason. A new QSR unit does not hit stabilized volume on day one; it spikes on opening novelty, drops, and then grinds upward over 6 to 12 months as it builds a repeat base. You are funding payroll for a team you deliberately overstaff during opening, food cost that runs high while a new crew learns portioning and waste control, and marketing spend during the period when nobody in the trade area has a habit yet. Budget the top of the working-capital range, not the middle. Undercapitalization is the most common proximate cause of first-unit failure across every franchise category, and it rarely presents as "the concept did not work" — it presents as a good unit sold at a loss in month 14 because the owner ran out of runway before the ramp finished.
Pre-opening carrying costs. Rent, insurance, utilities, and loan interest accrue during the construction period. On a 6-to-9-month build, that is a real number that lives outside the operating pro forma and is frequently omitted from a buyer's own model even when the FDD table accounts for parts of it.
Your own living expenses. Not in the FDD, not in the loan, and the reason many otherwise sound deals go sideways. If you are the working owner for the first 18 months, you cannot also be pulling a market-rate salary out of a unit that is still ramping. Have 12 to 18 months of personal expenses funded outside the deal.
Ongoing economics. The royalty is 5% of gross sales, the national marketing fund contribution is 1%, and franchisees carry an additional local cooperative advertising obligation in the low single digits — roughly 9% off the top before a single ingredient or hour of labor is paid. The franchise term is 20 years with a renewal option at the then-current fee schedule, personal guarantees are required, and the franchisor holds a right of first refusal on any resale.
Where that leaves the returns. System average unit volume sits in the neighborhood of $1.05 million, with a top quartile materially above that and a bottom quartile materially below. Store-level EBITDA for the brand historically runs in the 9% to 15% band after royalty and marketing — respectable for the category, below what the highest-performing QSR franchise brands deliver. At median volume and a 12% margin, you are looking at roughly $126,000 in store-level cash flow before debt service and before any owner salary you have not already expensed.
Do the arithmetic honestly. On a $478,000 low-end investment, that is a simple payback near 3.8 years — a good outcome. On a midpoint build near $1 million, payback stretches past 8 years. On a $1.74 million high-end build, simple payback approaches 14 years, which is longer than most operators' patience, longer than a typical lease's initial term, and dangerously close to the 20-year franchise term itself. The brand decision barely moves these outcomes. The format and site decision moves all of them. A buyer who lands a converted shell with an existing drive-thru at the bottom of the cost range and average volume has a genuinely good business. A buyer who ground-up builds at the top of the range and lands average volume has bought himself a job with a long tail of debt service.
Timeline. From signed agreement to open doors, budget 9 to 15 months: site selection and franchisor approval (2 to 5 months), lease negotiation and permitting (2 to 4 months, wildly jurisdiction-dependent — a California coastal city can consume more calendar on entitlements alone than an entire Texas build), construction (4 to 7 months), and the franchisor's multi-week training program somewhere in the middle. Then plan on 12 to 24 months post-opening before the unit stabilizes.
Where buyers get this wrong
Underwriting on the top quartile. Every prospect reads the Item 19 disclosure, sees the top-quartile number, decides they will obviously be an above-average operator, and models accordingly. Half the system is below median by construction. The top quartile is disproportionately composed of legacy Southern California units with decades of brand equity in their trade area and rent structures a new buyer cannot replicate. Model the median. Sensitivity-test the bottom third. Treat any outcome above median as upside you did not pay for.
Buying brand awareness that does not exist in your market. This is the defining error for expansion-market buyers. In Southern California, Wienerschnitzel is a 60-plus-year institution — people have childhood associations with the A-frame buildings. In Omaha, Indianapolis, or Portland, a substantial share of your trade area has never heard of it, and the national marketing fund's dollars are weighted toward the DMAs where the units already are. You are not buying brand-driven traffic; you are buying an operations playbook, a supply chain, and a menu, and you are personally funding awareness out of your own local marketing budget. That is a legitimate business — it is just a different business than the one the brand sells, with a longer ramp and a much larger local marketing line than the pro forma suggests. Historically, when units in this system have closed, they have skewed toward expansion markets rather than the Southern California core. That pattern is worth checking in the current Item 20 table before you sign, because it is the cleanest available signal on how expansion-market economics have actually performed.
Planning to operate absentee. The labor model on a value-priced QSR does not have room in it for both a general manager at market wage and an owner drawing a salary for supervision. Operators who install a GM and visit twice a week reliably run labor several points above system and food cost a point or two above system, because nobody is counting the waste bin at close. On a 12% margin, three points of labor and two points of food is the entire margin. The unit does not "underperform" — it goes to zero. If you cannot commit to being in the building 50-plus hours a week for the first 18 months, buy something else or buy into an existing multi-unit operation as a passive partner.
Getting the seasonality backwards. Hot dogs and quick-service in general are warm-weather businesses. The strong stretch runs from roughly Memorial Day through Labor Day, when foot and vehicle traffic peak and people eat out more; the soft stretch is the late-fall and winter months, when the fourth quarter and the dead weeks of January and February pull volume down. Build your working-capital plan around the cold months being the drain, not the warm ones. Operators who front-load spending in the summer on the assumption that the strong season is still ahead of them find themselves short in the exact months when they need cushion. Cold-weather expansion markets compound this: a Midwest unit does not just have a soft winter, it has a soft *long* winter, which widens the annual swing and raises the working-capital floor by a meaningful margin versus a Phoenix or San Diego unit.
Treating the drive-thru as optional. Covered above, but it belongs on the mistakes list because it is the error that most often gets rationalized. An in-line end-cap comes at a lower build cost, which makes the initial investment math look better, which makes an undercapitalized buyer feel like they found a workaround. They found a lower-volume format. The build savings do not compensate for the transaction volume you gave up, and the resale is harder because the next buyer's lender will underwrite the same way.
Skipping the departed-franchisee calls. Item 20 lists franchisees who left the system. Those are the highest-information calls available to you and the ones nobody makes, because the conversation is uncomfortable. Make them.
Signing before the lease is nailed. The franchise agreement and the lease are two contracts, and the order matters. If you sign the franchise agreement first, you have committed to a 20-year obligation with no site, which hands every remaining piece of negotiating leverage to the landlord and the clock. Negotiate lease terms — including a franchisor-required conditional assignment clause, a co-tenancy or traffic clause if applicable, and a build-out allowance — in parallel with, not after, the franchise decision.
Decision framework: when to open, when to buy existing, and when to walk
There are four viable paths and they are not equally good for the same buyer.
Path 1 — Build a new freestanding unit. Right for the experienced multi-unit Sunbelt operator with real estate capability, existing back-office infrastructure, and access to the second-unit fee discount and development incentives. You get to pick the site, you control the build quality, and if you own the pad, you have stacked a real estate position underneath an operating business — the rent stops being a P&L drain and becomes an internal transfer building your own equity. This is the highest-ceiling path and the highest capital requirement. It is the wrong path for a first-timer.
Path 2 — Buy an existing unit. Structurally the most underrated option and the right default for most single-unit buyers who are set on this brand. You acquire trailing sales history instead of a pro forma, an existing crew, an established trade-area habit, and a build that is already paid for by someone else. Resale QSR units in established markets typically trade at a multiple of store-level EBITDA — a fraction of new-build cost for a unit that is already producing. The friction: the franchisor holds a right of first refusal, charges a transfer fee, and will require you to complete the full training program regardless of your background. Your diligence shifts from site analysis to books analysis — get three years of tax returns and POS exports, not a broker's summary, and understand precisely *why* the seller is selling. Deferred maintenance and a looming remodel requirement are the two landmines; both are quantifiable if you look.
Path 3 — Territory-grab in an expansion market. Right only for a well-capitalized operator taking a multi-unit development agreement, not for a single-unit buyer. The logic is real: sub-saturation density, first-mover position, and locked development rights across a metro. But the first unit in a market with zero brand awareness carries the entire cost of building that awareness, and it does so alone. If you are going to do this, do it with a 3-to-5-unit commitment and a marketing budget that assumes zero brand-driven traffic in year one — because that assumption is close to correct.
Path 4 — Walk. Entirely legitimate and, for most inquirers, correct. If you are a first-time single-unit buyer in a cold-weather market with $150,000 in liquid capital and a plan to keep your day job, this is not your deal. That is not a knock on the brand; it is a knock on the fit. Compare against QSR franchise brands with materially higher average unit volumes and stronger store-level margins on similar or lower build costs — several exist in the fast-casual and chicken segments — and against buying an existing unit in *any* brand rather than building new in this one. And compare against the independent path: an owner-operator with genuine restaurateur and local-marketing chops can open an independent concept for a fraction of the franchise build with no royalty, no marketing fund, and no 20-year term, at the cost of having no playbook and a longer ramp. Franchises reward systems-executors. Independents reward marketers. Be honest about which one you are.
The tiebreaker question across all four paths: does the deal still work at bottom-third volume? Every buyer who has ever gotten hurt in franchising got hurt because the answer was no and they signed anyway.
Related questions
How much liquid capital does the franchisor require?
Franchisors screen on net worth and liquid capital, and the FDD or the franchise-development team will state current thresholds. Practically, budget at least $400,000 liquid for a freestanding build, plus 12 to 18 months of personal living expenses funded entirely outside the deal.
Is buying an existing unit really cheaper than building?
Usually yes, and materially so. Resale QSR units trade at a multiple of store-level EBITDA rather than replacement cost, which typically lands well below a new-build number — and you buy trailing sales data instead of a pro forma. Expect a transfer fee and franchisor right of first refusal.
Does California's fast-food wage law change the math?
Substantially. California's fast-food minimum wage puts a structural floor under unit labor several points above Sunbelt states. That single line has shifted new-build economics toward Texas, Arizona, and Nevada, and it is the main reason the growth push is aimed outside California.
How long until the unit stabilizes?
Plan on 12 to 24 months. Openings spike on novelty, drop within weeks, then grind upward as repeat frequency builds. Expansion markets with no brand awareness sit at the long end of that range; established Southern California trade areas at the short end.
Can I finance this with an SBA loan?
Typically yes for established franchise brands listed on the SBA Franchise Directory. Expect 7(a) structure, a significant equity injection, a full personal guarantee, and liens on available collateral. Pre-qualify with two lenders before signing anything.
FAQ
What is the total investment needed to open a Wienerschnitzel?
The disclosed all-in range for a new freestanding unit runs roughly $478,200 to $1,737,700, per the franchisor's Item 7 estimated initial investment table. The spread is driven almost entirely by real estate and construction — a ground lease on an existing pad sits near the bottom, a ground-up build on owned dirt in a coastal metro near the top. Confirm current figures in the most recent FDD, since Item 7 is updated annually.
What can I realistically expect in the first year?
System average unit volume is in the neighborhood of $1.05 million with store-level EBITDA historically in the 9% to 15% range after royalty and marketing. At median volume and a 12% margin, that is roughly $126,000 in store-level cash flow — before debt service and before any owner salary you have not already expensed. A ramping first-year unit typically lands below its own stabilized run rate.
How long does it take to break even?
Simple payback depends far more on what you spent than on how you operate. At the low end of the investment range against median cash flow, payback lands near four years. At a midpoint build it stretches past eight. At the high end it approaches fourteen. Cash-flow breakeven on operations alone typically arrives within the first year; recovering the invested capital is the long number.
What are the ongoing fees?
A 5% royalty on gross sales, a 1% national marketing fund contribution, and a local cooperative advertising obligation in the low single digits — roughly 9% off the top in total, before food, labor, or occupancy. The term is 20 years with a renewal option at the then-current fee schedule, and personal guarantees are required.
Is this a good first franchise?
Generally no. The economics reward operators who already run quick-service units in the brand's core Sunbelt states — they bring supplier relationships, trained shift leaders, and back-office overhead spread across multiple units, which is worth several margin points a single-unit first-timer simply cannot manufacture. A first-time buyer who is set on the brand is usually better served buying an existing unit than building a new one.
Which locations perform best?
Freestanding pads with a drive-thru in California, Texas, Arizona, and Nevada. The physical predictors matter more than the state: an 8-plus-car drive-thru stack, long sight lines from an arterial road, workable left-turn ingress, and adequate daytime population within three miles. Two units with identical agreements can differ by a factor of two on site geometry alone.
Sources
- Federal Trade Commission — Franchise Rule compliance guide and the 14-day FDD disclosure requirement: https://www.ftc.gov/business-guidance/resources/franchise-rule-compliance-guide
- U.S. Small Business Administration — SBA Franchise Directory and 7(a) loan program terms: https://www.sba.gov/document/support-sba-franchise-directory
- California Department of Financial Protection and Innovation — franchise registration and public FDD filings: https://dfpi.ca.gov/
- Wienerschnitzel franchise development — official brand franchising site: https://www.wienerschnitzelfranchise.com/
- International Franchise Association — franchise business economic outlook and industry data: https://www.franchise.org/
- Nation's Restaurant News — Galardi Group and Wienerschnitzel brand coverage: https://www.nrn.com/
- Restaurant Dive — Wienerschnitzel growth strategy and unit-count reporting: https://www.restaurantdive.com/
- QSR Magazine — quick-service industry and Wienerschnitzel leadership coverage: https://www.qsrmagazine.com/
- U.S. Bureau of Labor Statistics — Quarterly Census of Employment and Wages, NAICS 722513 limited-service restaurants: https://www.bls.gov/cew/
- California Department of Industrial Relations — fast food minimum wage requirements: https://www.dir.ca.gov/dlse/Fast-Food-Minimum-Wage.htm
Related on PULSE
- Should I open or buy an Oxi Fresh Carpet Cleaning franchise in 2027?
- Should I open or buy an Oil Can Henry's franchise in 2027?
- Should I open or buy a KidStrong franchise in 2027?
- Should I open or buy a Premier Garage franchise in 2027?
- Should I open or buy a Jazzercise franchise in 2027?
- Should I open or buy a Nekter Juice Bar franchise in 2027?
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-qShould I open or buy a Minuteman Press franchise in 2027?
 pulse-qShould I open or buy a Glory Days Grill franchise in 2027?
 pulse-qShould I Repair or Replace My Delivery Fleet Vehicles as My Landscaping Business Scales in 2027?
 pulse-qHow Do I Tie Commission to More Than One Product in 2026?
 pulse-qShould I open or buy a Pollo Tropical franchise in 2027?
 pulse-qHow Many Employees Should I Schedule Each Shift at My Hot Pot Restaurant in 2026?
 pulse-qShould I open or buy a Bob Evans franchise in 2027?
 pulse-qShould I open or buy a Goddard School franchise in 2027?
 pulse-qShould I open or buy a Cookies Crumbl alternative — Insomnia Cookies — franchise in 2027?
 pulse-qShould I open or buy a Buca di Beppo franchise in 2027?