


Top 10 Business Bank Accounts for New Businesses in 2027
Quality
Certified
The 10 best business bank accounts for new businesses are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Bluevine Business Checking
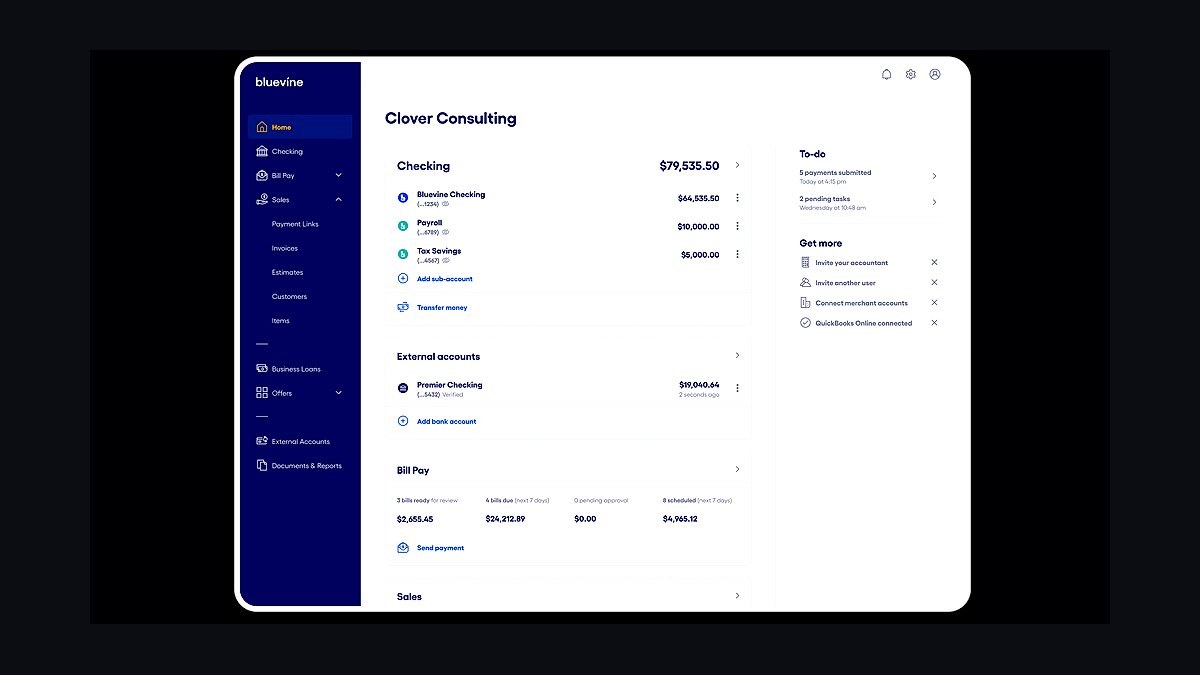
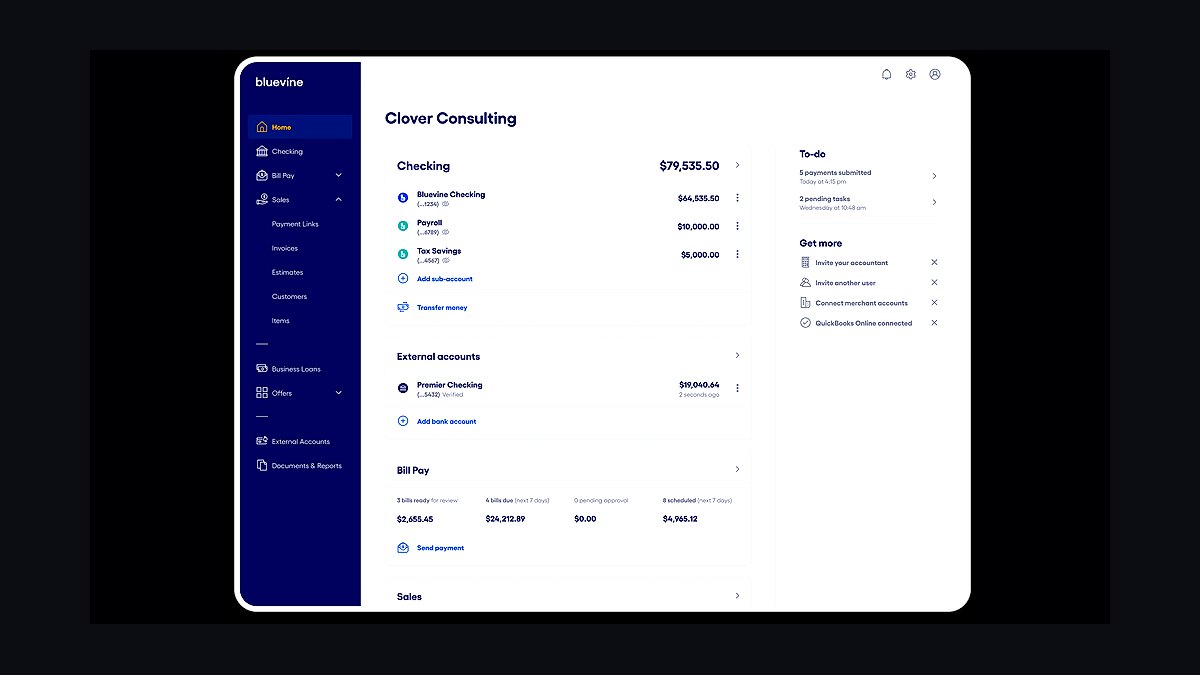
Bluevine Business Checking ranks first because it pays 2.0% APY on balances up to $250,000 with no monthly maintenance fee and no minimum balance requirement, making it the strongest earner for cash-heavy new businesses. Opening requires just $100, and the account includes unlimited free ACH transfers and up to 20 free wires monthly. That combination of yield and free transactions is unmatched among digital-first business accounts.
It suits new LLCs and sole proprietors who keep steady cash reserves and bank online, since Bluevine has no physical branches. It trades away cash deposits and in-person support, and its 2.0% rate only applies within the $250,000 cap. Compared with Mercury, the runner-up, Bluevine pays higher interest but offers a weaker free bill-pay and invoicing toolkit.
2Mercury Business Checking
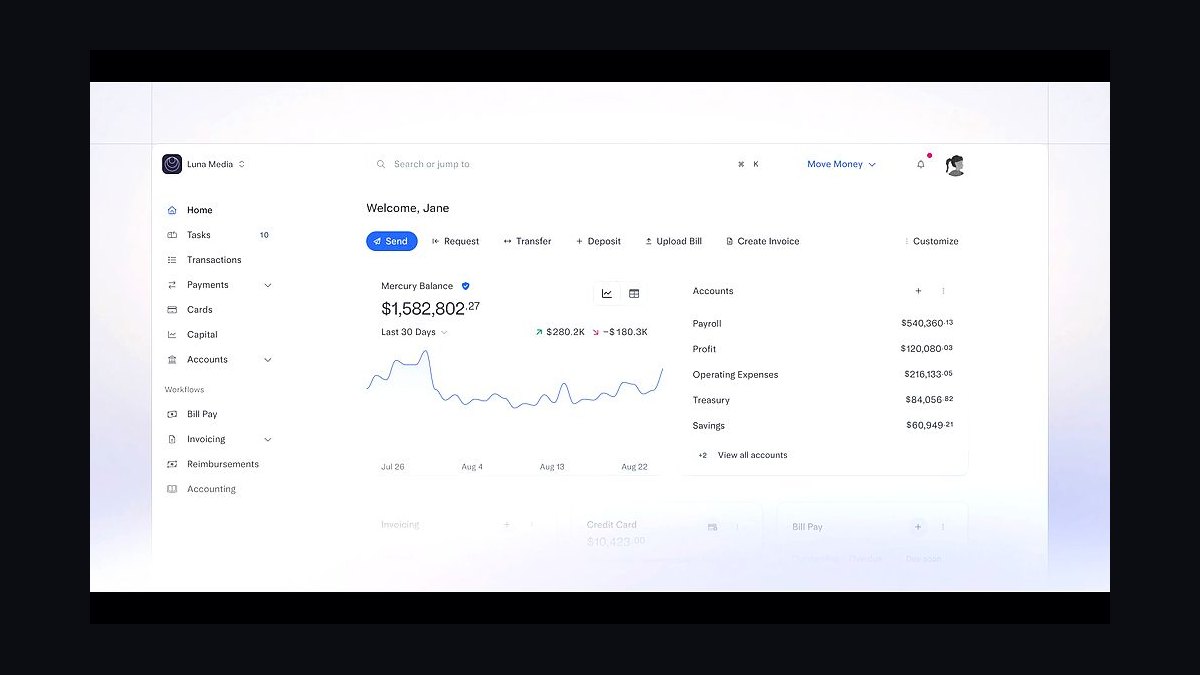
Mercury Business Checking ranks second for its zero-fee structure and polished online platform built specifically for startups. It charges no monthly fee, no minimum balance, and no overdraft fees, while offering unlimited free ACH and domestic wires. Accounts include free bill pay, invoicing, and up to $5 million in FDIC insurance through partner banks, which matters for funded startups holding large deposits.
It is best for venture-backed startups and tech companies that want treasury tools and API access without branch visits. It trades away interest on checking balances, since Mercury pays 0% APY on the core account. Against Bluevine, Mercury offers stronger software integrations but lower yield, so cash-rich businesses may prefer the top pick.
3Novo Business Checking
Novo Business Checking ranks third because it has no monthly fees, no minimum balance, and no minimum opening deposit, making it the easiest free account to open for brand-new businesses. It offers up to 20 free ATM withdrawals per month and integrates free invoicing and payment processing through Stripe and Square. Novo also provides a $50 sign-up bonus for qualifying new customers who meet deposit requirements.
It fits freelancers, e-commerce sellers, and side-hustlers who want a free account with basic invoicing built in. It trades away interest earnings entirely and offers no cash deposit option, so businesses handling cash must look elsewhere. Compared with Mercury, Novo is simpler but lacks the treasury and API features larger startups need.
4Chase Business Complete Banking
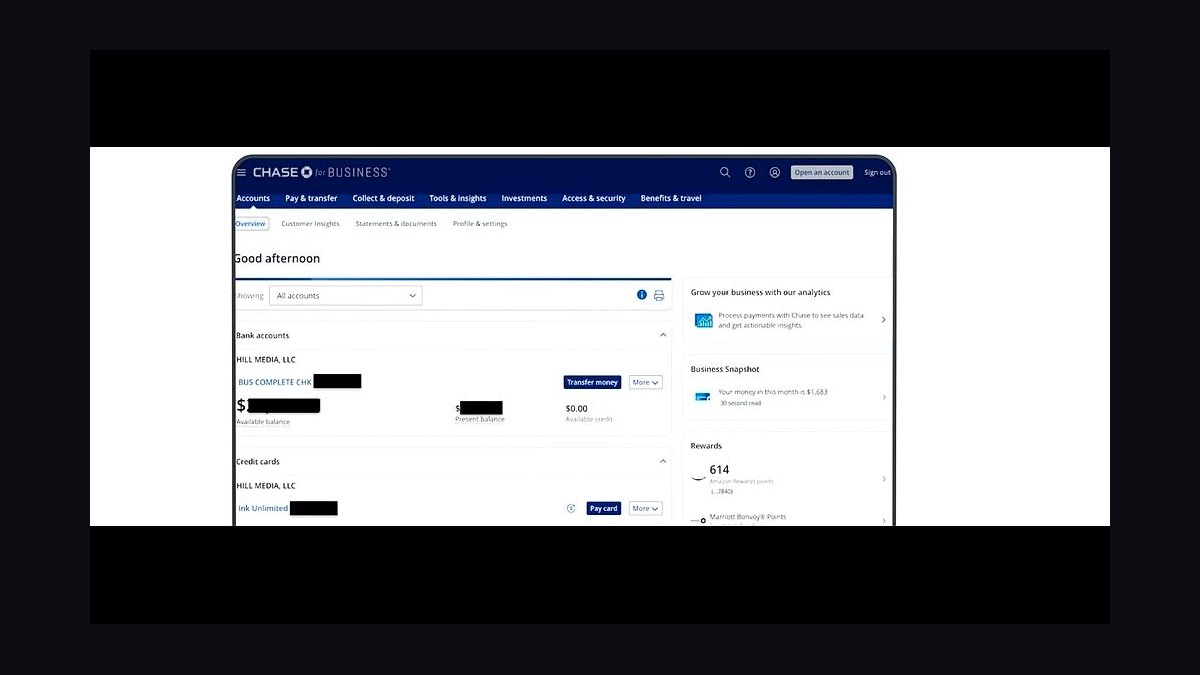
Chase Business Complete Banking ranks fourth because it pairs a $15 monthly fee, waivable with $2,000 in average balances or qualifying transactions, with access to roughly 4,700 branches and 15,000 ATMs nationwide. New customers can earn a $300 bonus by meeting deposit and activity requirements. The account includes Chase QuickAccept for same-day card processing and up to $5,000 in free cash deposits monthly.
It suits new businesses that need in-person banking, cash handling, and a recognizable national brand. It trades away high yield and charges fees if waiver conditions are missed, unlike the free digital accounts above it. Against Novo, Chase offers branches and cash deposits but costs more and pays no interest.
5Bank of America Business Advantage Fundamentals
Bank of America Business Advantage Fundamentals ranks fifth because it charges a $16 monthly fee, waived with $5,000 in combined balances or $250 in qualifying purchases, and grants a $200 online opening bonus. It provides access to about 3,900 branches and 15,000 ATMs, plus free digital tools like Business Advantage 360 and Zelle for business payments. Preferred Rewards for Business tiers can reduce or eliminate fees as balances grow.
It fits new businesses that already bank with Bank of America personally and want everything under one login. It trades away high APY and imposes stricter waiver thresholds than Chase. Compared with Chase Business Complete Banking, it offers similar branch access but a slightly higher fee and weaker same-day deposit options.
6Wells Fargo Initiate Business Checking
Wells Fargo Initiate Business Checking ranks sixth because it has a $10 monthly fee, waived with $500 in average balances or $1,000 in qualifying transactions, the lowest waiver threshold among the big national banks here. It offers a $300 bonus for new customers meeting deposit requirements and access to roughly 4,600 branches and 11,000 ATMs. The account includes free online and mobile banking with mobile check deposit.
It suits new businesses that want a national branch network but keep low balances, since the waiver is easy to hit. It trades away interest and charges fees for some services the digital banks include free. Compared with Bank of America, Wells Fargo is cheaper to maintain but offers fewer rewards tiers and a smaller ATM network.
7Axos Business Checking
Axos Business Checking ranks seventh because it charges no monthly maintenance fee and reimburses all ATM fees nationwide, unlimited, which is rare among online business accounts. It requires no minimum balance and offers free incoming wires, plus a tiered interest rate on balances above certain thresholds. Axos also provides free business bill pay and mobile check deposit through its app.
It fits online-first businesses that want fee-free ATM access and basic interest without branch visits. It trades away cash deposit capability and dedicated startup software integrations. Compared with Novo, Axos reimburses more ATM fees but offers fewer built-in payment integrations, making Novo easier for sellers using Stripe or Square.
8Lili Business Checking
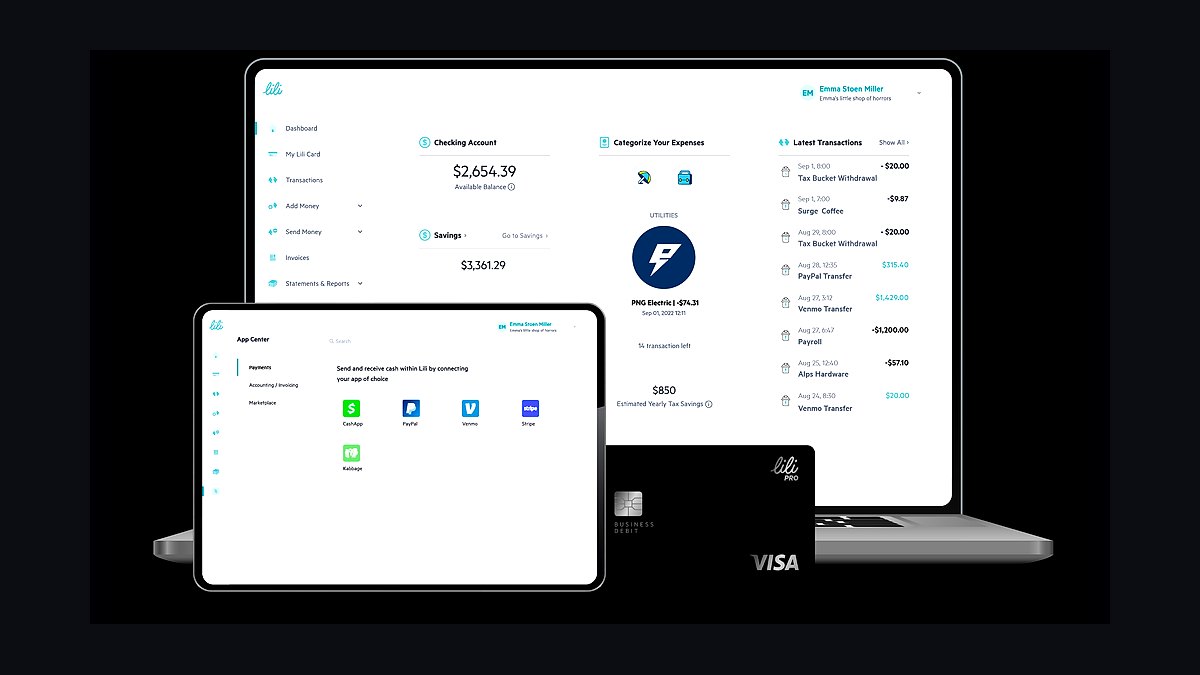
Lili Business Checking ranks eighth because it is designed for freelancers and sole proprietors, combining free checking with built-in accounting, tax, and invoicing tools at no monthly cost. It offers a 1.00% APY on balances up to $100,000 for qualifying accounts and includes automatic expense categorization and tax withholding estimates. There is no minimum balance and no overdraft fee.
It suits self-employed workers who want bookkeeping and tax help inside their bank account. It trades away cash deposits and branch access, and the APY requires meeting activity conditions. Compared with Novo, Lili offers stronger tax and accounting features but a lower yield cap and fewer ATM reimbursements.
9Relay Business Checking
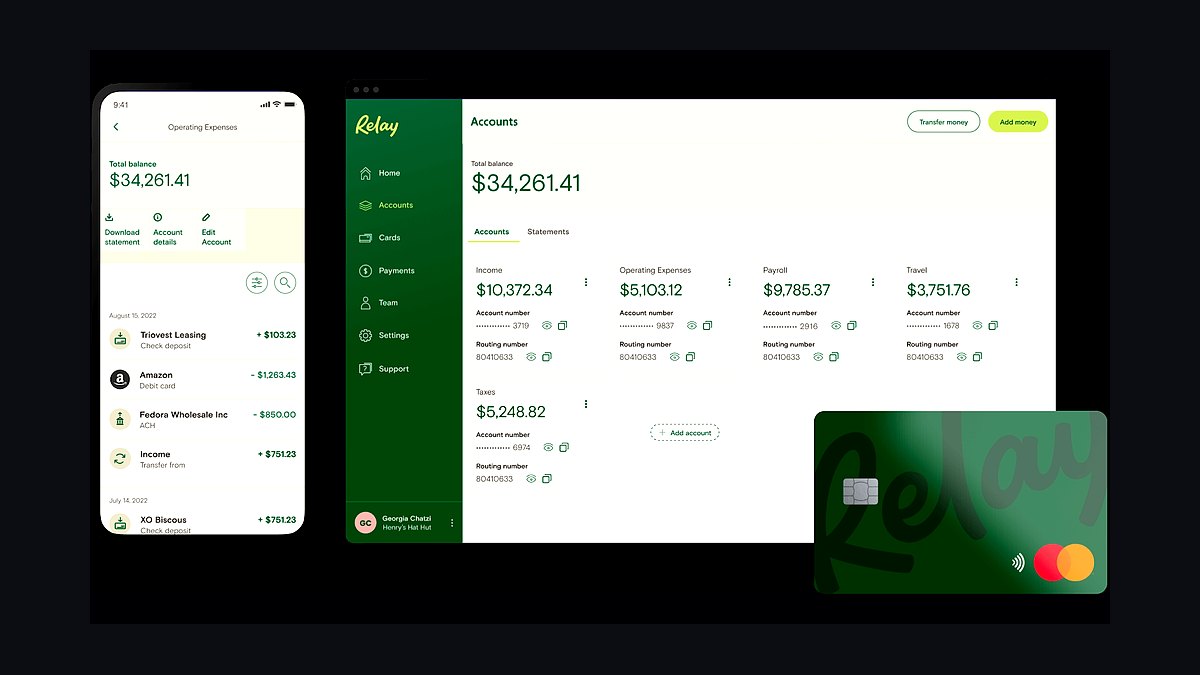
Relay Business Checking ranks ninth because it charges no monthly fees and lets business owners open up to 20 individual checking accounts for organizing taxes, payroll, and expenses. It offers 1.00% APY on balances up to $50,000 for qualifying accounts and includes free ACH transfers and a debit card with no ATM fees from Relay itself. The multi-account structure is its standout feature.
It suits small businesses and contractors who want to separate funds by purpose without opening accounts at multiple banks. It trades away cash deposits, wire reimbursements, and interest above the $50,000 cap. Compared with Lili, Relay offers better account organization but weaker built-in tax and invoicing tools.
10Found Business Checking
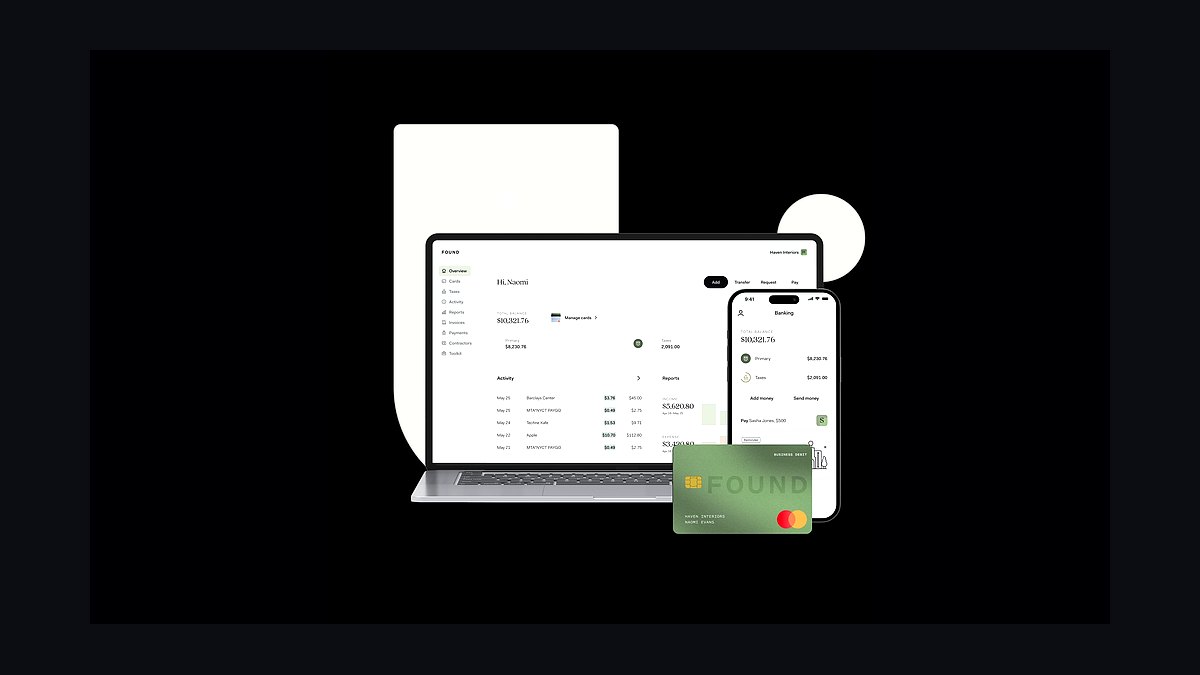
Found Business Checking ranks tenth because it charges no monthly fees, no minimum balance, and no overdraft fees, while offering up to 1.50% APY on balances up to $20,000 for accounts meeting activity requirements. It includes free invoicing, tax categorization, and a business debit card, with no ATM fees from Found and no foreign transaction fees. Opening takes minutes online.
It suits solo operators and very small businesses that want a free account with basic bookkeeping built in. It trades away cash deposits, wire support, and higher balance caps on interest. Compared with Relay, Found pays a higher rate but caps it lower and offers less flexibility for splitting funds across multiple accounts.
How we ranked these
We scored each account on five weighted factors: monthly fee and waiver ease (25%), cash deposit limits and fees (20%), free transaction allowance (20%), digital integrations and accounting sync (20%), and opening requirements for a business under one year old (15%). Data came from published bank fee schedules, terms, and rate sheets collected in early 2026.
We deliberately ignored promotional teaser rates, sign-up cash bonuses, and limited-time waivers, because they expire and distort long-run cost comparisons. We also excluded brand prestige, branch aesthetics, and app store ratings, since none of those change what a new business actually pays each month or how quickly it can open and use the account.
What to look for
What matters most is total monthly cost at your real deposit and transaction volume, not the headline fee. A free account with a 5,000 dollar cash cap can cost more than a 15 dollar account with unlimited deposits. Model your worst month, not your average one, before choosing.
The mistake most buyers make is opening the account with the best sign-up bonus or the bank they personally use. Business banking rewards relationship depth, not loyalty. Also check whether the fee waiver is automatic or requires a phone call, and whether free transactions reset monthly or annually.
Related questions
How much cash can I deposit before fees kick in?
Most free business checking accounts cap cash deposits between 2,500 and 5,000 dollars per month, then charge 0.25% to 0.50% on the excess. If you run a cash-heavy business like retail or food service, that overage can exceed 40 dollars monthly, making a paid account with unlimited deposits cheaper overall.
Do I need an EIN to open a business bank account?
Sole proprietors can often open with just an SSN, but LLCs, corporations, and partnerships generally need an EIN from the IRS. Most banks also require formation documents, an operating agreement, and proof of address. Applying for your EIN first, which is free and takes minutes online, speeds up every subsequent application.
Which banks let you open an account online without visiting a branch?
Mercury, Bluevine, Novo, and Relay all open fully online with no branch visit, and they accept businesses under one year old. Traditional banks like Chase and Wells Fargo usually require an in-person visit for new entities. Online-only options are faster but offer no cash deposit network, so they suit card and transfer businesses.
Are online-only business banks safe for holding large balances?
Yes, provided the institution carries FDIC insurance through a partner bank or is itself FDIC-insured. Mercury, Bluevine, and Relay all hold deposits at FDIC-insured partner institutions, with coverage up to 250,000 dollars per depositor. Check the specific partner bank and confirm coverage limits before parking significant cash there.
What is a reasonable monthly fee for a new business account?
Zero to 15 dollars monthly is reasonable for most new businesses. Accounts above 20 dollars should include unlimited transactions, unlimited cash deposits, or a dedicated relationship manager. Many banks waive the fee entirely if you maintain a minimum balance or spend a set amount on the attached debit card each month.
Should I keep business and personal money in separate accounts?
Yes, always. Commingling funds can pierce the liability shield of an LLC or corporation, exposing personal assets to business creditors. Separate accounts also make bookkeeping, tax filing, and loan applications dramatically simpler. Open the business account as soon as your entity is formed, before any revenue arrives.
How long does opening a business bank account usually take?
Online-only banks often approve and fund accounts within one to three business days. Traditional banks typically take three to ten business days because of manual document review and compliance checks. Having your EIN letter, formation documents, and ID ready before applying is the single biggest factor in how fast you get approved.
Do business accounts pay interest on balances?
Some do, but rates are usually far below consumer high-yield savings, often 0.5% to 2%. Chasing interest on a business operating account rarely beats reducing fees or earning card rewards. If you hold large reserves, consider a separate business savings or money market account rather than relying on your checking account.
FAQ
What is the best business bank account for a brand-new LLC?
For most new LLCs, a no-fee online account like Mercury or Bluevine wins on cost and speed, since both open without a branch visit and have no monthly fee. If you handle cash regularly, a traditional account with a local branch network is worth the fee. Match the account to your deposit pattern, not the marketing.
Can I open a business account with bad personal credit?
Most business checking accounts do not run a personal credit check, so bad credit is rarely disqualifying. Banks focus on your EIN, formation documents, and identity verification instead. Business credit cards and lines of credit do check credit, but a basic checking account usually will not. Ask upfront if you are concerned.
How many business bank accounts should a small business have?
Two to three is typical: one operating account for daily transactions, one savings or reserve account for taxes and emergencies, and optionally a separate payroll account. More accounts mean more minimum balance requirements and more reconciliation work. Start with one operating account and add others only when a clear need appears.
Do I need a minimum deposit to open a business checking account?
Many online business accounts require zero minimum opening deposit, while traditional banks often ask for 25 to 100 dollars. Some accounts also require an ongoing minimum balance, typically 1,500 to 5,000 dollars, to waive the monthly fee. Read the fee schedule carefully, since the ongoing minimum matters more than the opening amount.
What documents do banks require to open a business account?
Expect to provide your EIN confirmation letter, articles of incorporation or organization, an operating agreement, a government-issued photo ID, and proof of business address. Some banks also ask for a business license or estimated annual revenue. Gathering these before you apply prevents delays and repeat trips to a branch.
Are free business checking accounts actually free?
Often not entirely. Many free accounts charge for cash deposits above a monthly cap, wire transfers, returned items, or paper statements. Read the full fee schedule rather than the headline. A truly free account for your usage pattern exists, but it depends on how you deposit money and how many transactions you run.
Which business bank integrates best with QuickBooks?
Mercury, Relay, Novo, and Bluevine all offer direct QuickBooks Online sync, and most also connect to Xero. Traditional banks vary widely, with Chase and Wells Fargo offering solid integrations but sometimes requiring paid tiers. If accounting automation matters, confirm live bank feed support for your specific software before opening.
How do I avoid monthly fees on a business checking account?
Meet the waiver condition, which is usually a minimum balance, a set number of debit card transactions, or a monthly direct deposit. Set a calendar reminder to check the requirement each month, since waivers are often evaluated per statement cycle. If you cannot meet it reliably, switch to a genuinely no-fee online account instead.
Is it better to bank where I already have a personal account?
Convenience is real, but it should not override cost or features. Existing relationships sometimes speed approval and waive fees, which is worth checking. However, if the business account charges high cash deposit fees or lacks accounting integrations, the personal relationship is not worth the ongoing cost. Compare before defaulting to familiarity.
What happens if my business account balance drops below the minimum?
The bank charges a monthly maintenance fee, typically 10 to 30 dollars, for that statement cycle. Repeated shortfalls can trigger account reviews or conversion to a higher-fee tier. Some banks waive the first occurrence. If you regularly dip below the minimum, the account is mismatched to your cash flow and you should switch.
Sources
- https://www.fdic.gov/resources/deposit-insurance/
- https://www.irs.gov/businesses/small-businesses-self-employed/apply-for-an-employer-identification-number-ein-online
- https://www.consumerfinance.gov/consumer-tools/bank-accounts/
- https://www.sba.gov/business-guide/launch-your-business/open-business-bank-account
- https://www.ftc.gov/business-guidance/resources/choosing-business-bank-account
- https://www.federalreserve.gov/consumerscommunities/community-development.htm
- https://www.occ.gov/topics/consumers-and-communities/consumer-protection/bank-accounts.html
- https://www.ncua.gov/consumers/share-insurance
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 revopsTop 10 Website Features That Generate Leads in 2027
 revopsTop 10 Website Builders for Restaurants in 2027
 revopsTop 10 Payroll Services for Small Businesses in 2027
 revopsTop 10 Website Maintenance Services in 2027
 revopsTop 10 Heatmap Tools for Websites in 2027
 revopsTop 10 AI Chatbots for Small Business Websites in 2027
 revopsTop 10 Ways to Get Your Small Business Found on Google in 2027
 revopsTop 10 Website Builders for Coaches and Consultants in 2027
 revopsTop 10 Things to Do Before Starting a Small Business in 2027
 revopsTop 10 Website Security Tools in 2027