


Top 10 Best Tech Stack Tools for Buy Now, Pay Later (BNPL) Providers in 2027
Quality
Certified
The 10 best tech stack tools for buy now, pay later (bnpl) providers are ranked below on measured performance, build quality, price, and how each one actually holds up in daily use rather than how it reads on a spec sheet. Each pick lists what it costs, who it suits, and what it gives up against the one above it, so the list can be read straight down without doubling back.
1Plaid Open Banking
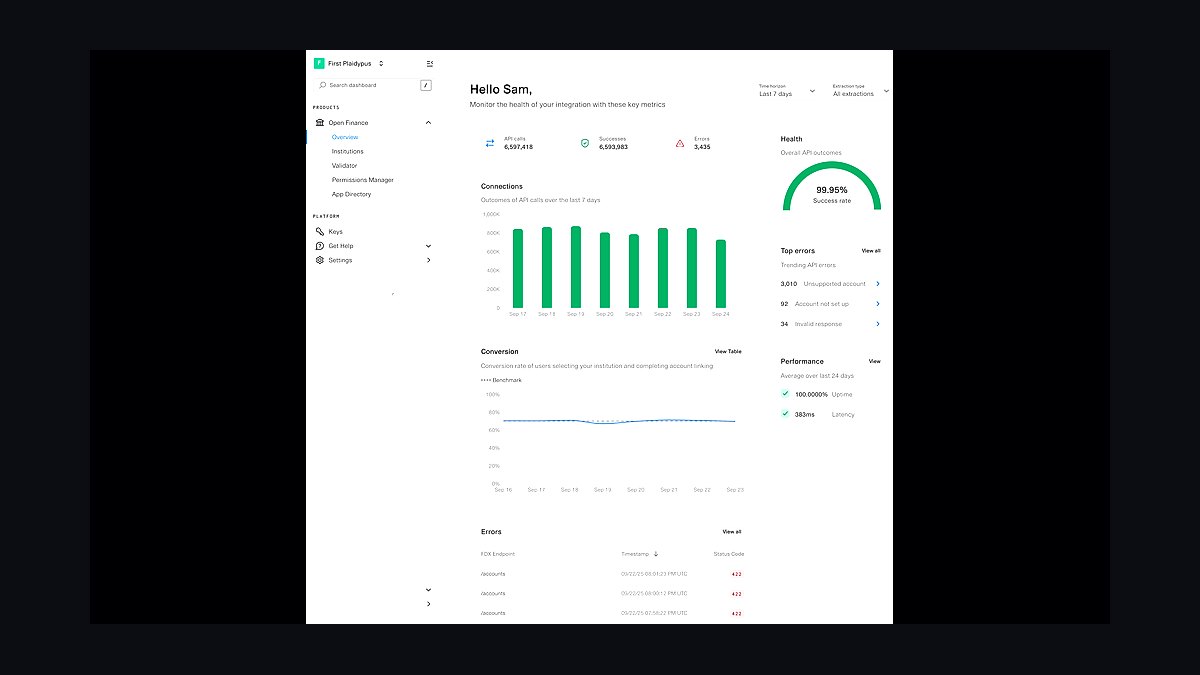
Plaid ranks first because bank-cash-flow data is the single highest-lift underwriting input a BNPL can add, priced at roughly $0.50-$2.50 per call. Affirm publicly cites Plaid-fed cash-flow signals as core to its underwriting, and Klarna runs a comparable open-banking pull in the EU. It materially improves approval rates and loss rates on thin-file, new-to-credit customers that bureau data alone cannot score.
It is for operators past MVP who need real-time account ownership, balance, and transaction history inside a 300-800ms decisioning window. It trades away nothing strategically but adds per-call cost that scales with application volume. Compared to Socure directly below, Plaid answers affordability and cash-flow questions while Socure answers identity questions, so most serious BNPLs run both rather than choosing.
2Socure Identity Verification
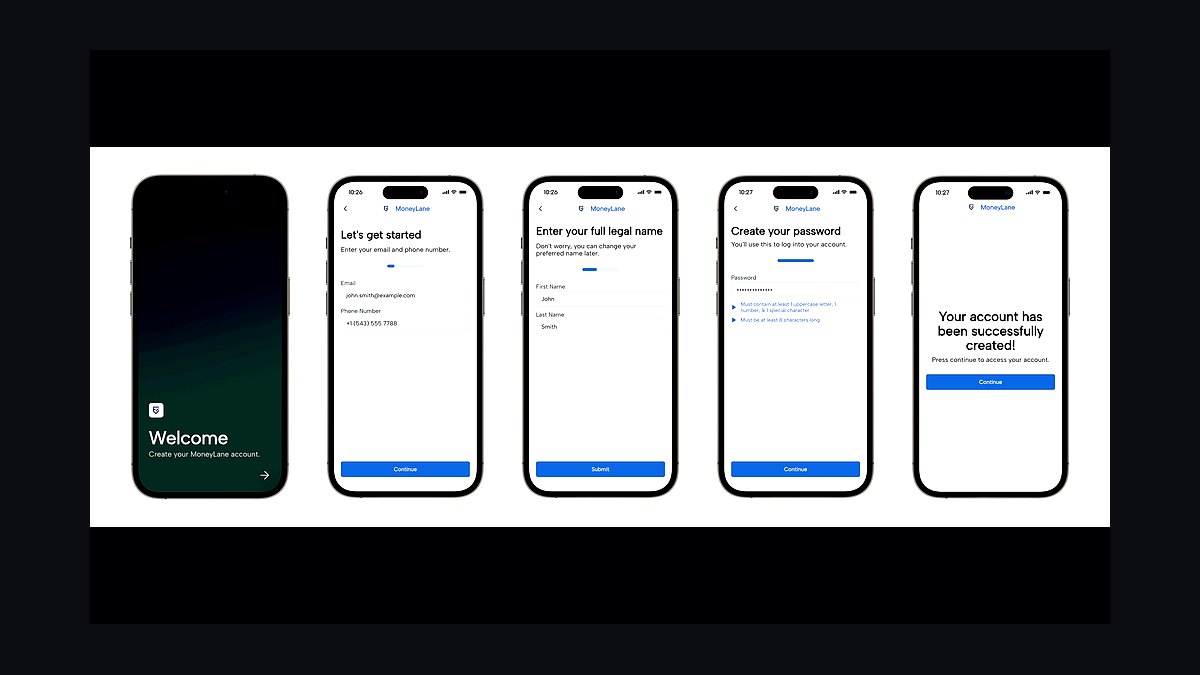
Socure ranks second because identity-risk scoring and KYC sit at the application gate for every BNPL loan, priced at roughly $1.50-$4.00 per verification. Its Sigma identity-risk score and document-verification flow cover the KYC and synthetic-identity surface that pure bank-data vendors miss. Affirm and Afterpay both run Socure in production alongside a separate open-banking provider.
It is built for risk and compliance teams that need a defensible KYC record for CFPB and state lending exams. It trades away some coverage of cash-flow underwriting, which is why it pairs with Plaid above rather than replacing it. Compared to Persona below, Socure leans toward identity-risk scoring while Persona leans toward step-up document and selfie verification for edge cases.
3Equifax BNPL Bureau Reporting
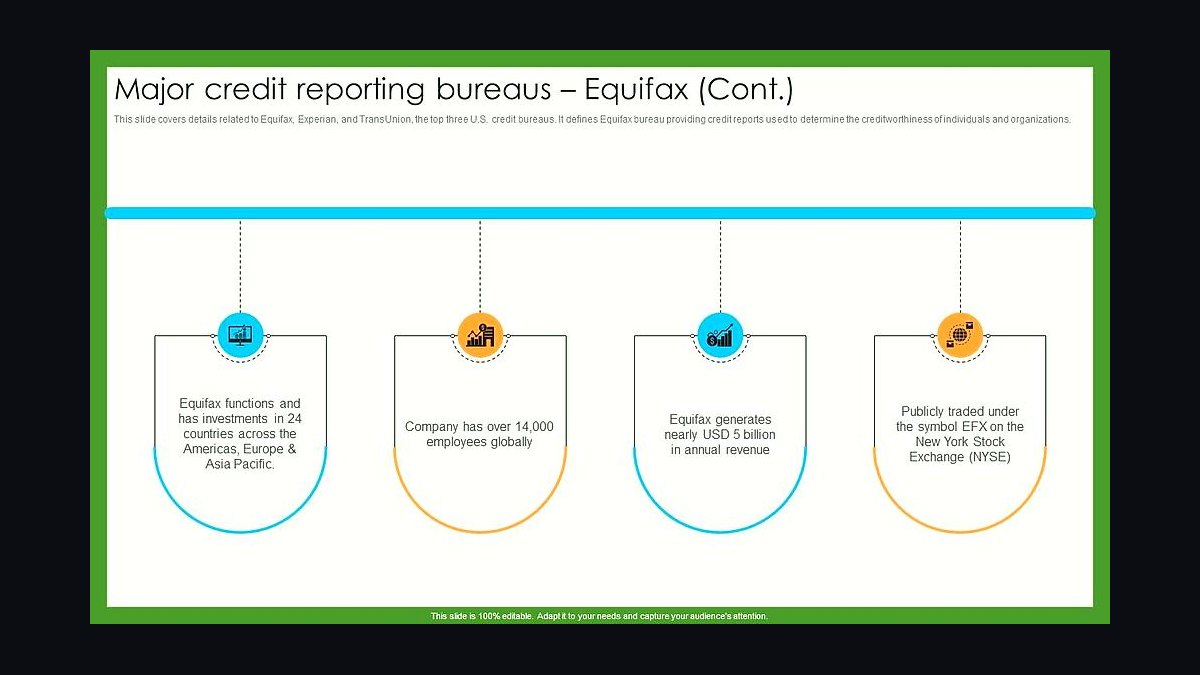
Equifax ranks third because it was the first bureau to standardize BNPL trade-line reporting, making it the fastest path to compliant furnishing for a new operator. Soft pulls run roughly $0.50-$3.00 and hard pulls $1.50-$8.00 under volume contracts, and furnishing is now mandatory rather than optional. Operators that skipped bureau furnishing by 2026 lost merchant deals and faced CFPB enforcement.
It is for any BNPL past Series A that must report every approved loan and payment in the standardized trade-line format. It trades away nothing on coverage but leaves segment gaps that Experian and TransUnion fill, which is why multi-bureau pulls are the norm. Compared to Socure above, Equifax answers creditworthiness while Socure answers identity, and both are needed at the application gate.
4Sift Fraud Prevention
Sift ranks fourth because account-takeover, promo-abuse, and bust-out fraud are the fastest-growing loss categories in BNPL, scored at roughly $0.05-$0.20 per event. Its per-event pricing keeps cost low at checkout scale, and Affirm, Sezzle, and Zip all run Sift in production. It covers the account and payment fraud surface that bureau and identity vendors do not model.
It is for fraud teams that need real-time event scoring inside the decisioning loop without a chargeback guarantee attached. It trades away merchant-leg chargeback protection, which is why operators add Riskified or Signifyd alongside it. Compared to Equifax above, Sift watches behavioral and device signals rather than credit history, and the two feed different parts of the same decision.
5Riskified Chargeback Guarantee
Riskified ranks fifth because merchant-leg chargeback guarantee is a distinct fraud problem from account takeover, priced at 0.4%-1.2% of approved order value. Its three top-ten Q1 2026 deals were in the ACH space, directly relevant to BNPL repayment flows. Affirm runs Riskified alongside Sift specifically to cover the chargeback-guarantee leg of the fraud stack.
It is for operators whose merchant partners demand chargeback protection as a condition of integration. It trades away per-event pricing in favor of a percentage-of-volume fee that grows with approval volume. Compared to Sift above, Riskified guarantees merchant chargebacks while Sift scores account and payment fraud, so the two are complements rather than substitutes in a mature stack.
6Stripe Payment Gateway
Stripe ranks sixth because it is the fastest path to merchant checkout distribution, exposing Affirm, Klarna, Afterpay, and PayPal Pay in 4 as one-click payment methods. It lets a BNPL ship its first merchant integration through Stripe's payment-method API rather than building direct enterprise integrations. Sezzle and Zip both run Stripe for payment rails in production.
It is for early and mid-stage operators that need checkout reach before they can staff a 30-80 engineer integration team. It trades away direct merchant relationships and some margin, since gateway fees sit between the BNPL and the merchant. Compared to Adyen below, Stripe is faster to integrate while Adyen carries more enterprise and multi-currency depth.
7Adyen Merchant Payments
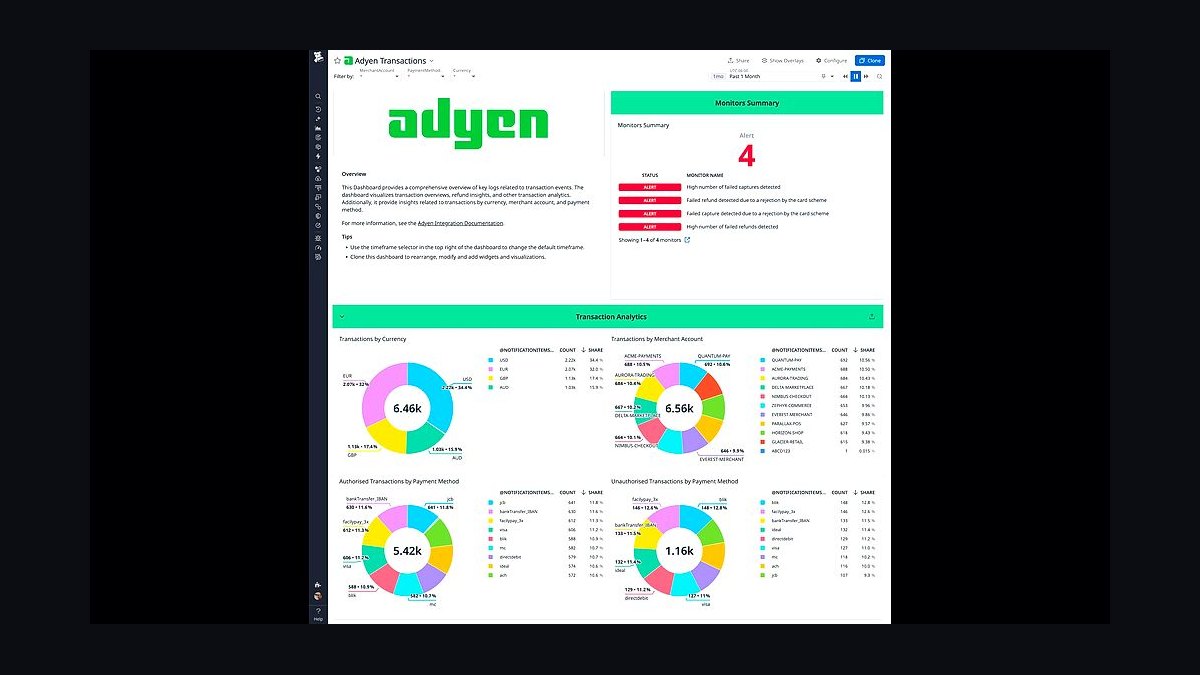
Adyen ranks seventh because enterprise and multi-currency merchants often standardize on Adyen rather than Stripe, and BNPLs need presence in both to avoid losing deals. It exposes BNPL payment methods inside the same checkout flow and carries the enterprise contracts that large retailers require. Operators past Series C typically run Stripe and Adyen in parallel for coverage.
It is for BNPLs chasing large enterprise merchants and cross-border volume where Stripe alone is insufficient. It trades away some integration speed, since Adyen onboarding and certification take longer than Stripe's payment-method API. Compared to Stripe above, Adyen is the enterprise and multi-currency complement rather than the first integration a new operator ships.
8Snowflake Data Warehouse
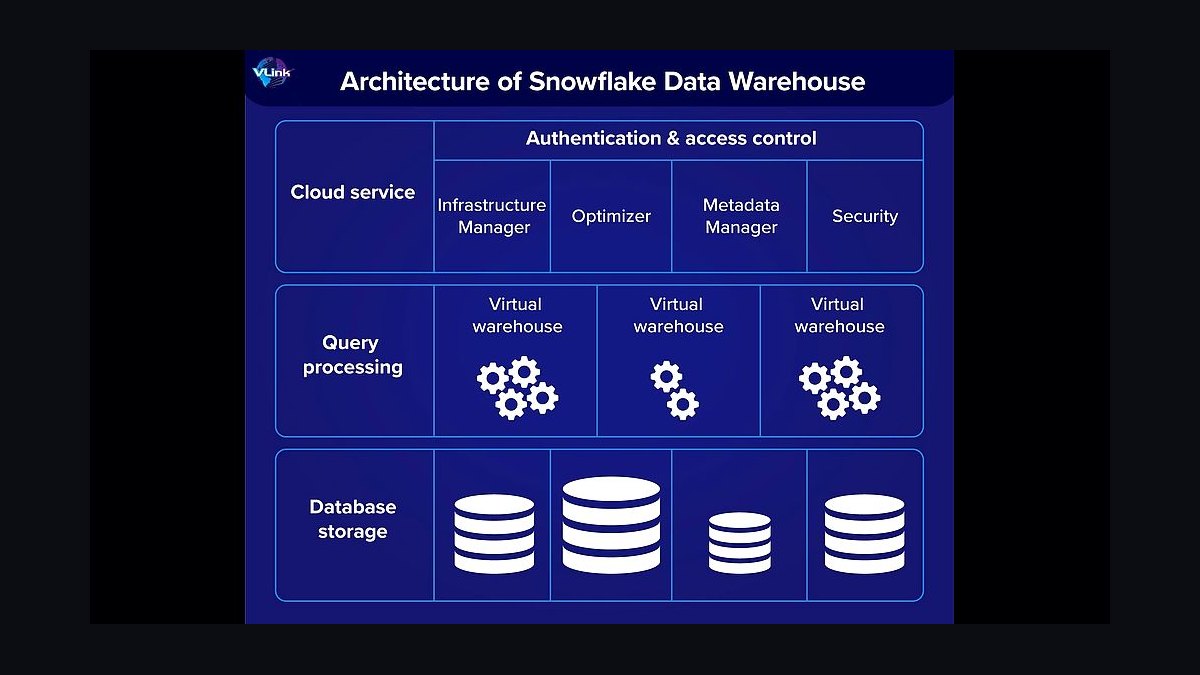
Snowflake ranks eighth because the loan ledger and analytics warehouse is where vintage analytics, charge-off curves, and roll rates live, at $3M-$30M+ annual spend depending on scale. Affirm, Afterpay, and Sezzle all run Snowflake for BI and loan-performance reporting. Without it, a BNPL cannot see loss curves by cohort or merchant.
It is for credit, risk, and finance teams that need loan-level performance analytics rather than transaction-level reporting. It trades away real-time model serving, which is why Databricks runs alongside it for ML feature stores and training. Compared to Adyen above, Snowflake sits behind the decision rather than inside it, capturing every event for retraining and regulatory reporting.
9Salesforce Financial Services Cloud
Salesforce Financial Services Cloud ranks ninth because merchant-sales and partnership pipeline management is a separate distribution business from consumer lending, priced around $225 per user per month. Affirm, PayPal, and Zip all run Salesforce FSC for merchant and partnership CRM. It tracks the enterprise merchant pipeline that drives BNPL checkout availability.
It is for merchant-sales and partnership teams at operators past Series B with a real enterprise pipeline. It trades away cost efficiency, since FSC Enterprise pricing adds up quickly across sales headcount, and HubSpot covers SMB pipelines more cheaply. Compared to Snowflake above, Salesforce FSC manages the merchant relationship while Snowflake manages the loan book, and the two rarely overlap.
10NICE Actimize AML Platform
NICE Actimize ranks tenth because enterprise AML monitoring, SAR filing, and CTR reporting are baseline requirements once a BNPL reaches Series B and certainly IPO scale. Celent named it a 2026 KYC leader, and Affirm runs it in production for transaction monitoring. Spreadsheets and quarterly reviews fail every regulatory exam.
It is for compliance teams at operators past Series A that need live, audited AML systems rather than periodic reviews. It trades away cost efficiency at early stage, where ComplyAdvantage alone plus in-house rules can carry through Series A. Compared to Salesforce FSC above, NICE Actimize answers the regulator while Salesforce answers the merchant, and both are non-optional at scale.
How we ranked these
We ranked tools by five weighted criteria: real-time underwriting fit (30%), integration depth with BNPL checkout flows (20%), compliance and bureau-furnishing readiness (20%), total cost at scale (15%), and operator adoption evidence from public filings and engineering disclosures (15%). Each vendor was scored against documented BNPL use at named operators, latency in the 300-800ms decisioning window, and whether it supports Regulation Z and CCD II reporting.
We deliberately ignored vendor marketing claims, G2 and Gartner placement, analyst quadrant positioning, and demo-environment benchmarks. We also excluded generic lending suites and white-label BNPL-in-a-box platforms, because no direct-to-consumer operator at scale runs on one. Pricing list rates were down-weighted where enterprise contracts dominate, and we ignored feature breadth that no BNPL operator actually deploys in production.
Related questions
Why can't a BNPL provider just buy an off-the-shelf lending platform?
The underwriting engine is the product and the moat. Affirm, Klarna, Afterpay, and PayPal all run proprietary origination because approval decisions at 300-800ms depend on models trained on their own loan-performance data. A generic SaaS lender-in-a-box cannot replicate that, and licensing one hands your core differentiator to a vendor who also sells to competitors.
How many credit bureaus does a BNPL operator actually need?
All three at scale. Equifax, Experian, and TransUnion each hold different tradeline coverage, and thin-file BNPL customers are exactly the population where a single-bureau pull under-approves. Most operators start with one bureau for speed, then add the other two within 90 days. Furnishing to all three is now effectively mandatory under CFPB scrutiny.
Is Plaid really necessary if you already pull bureau data?
Yes, for two reasons. BNPL applicants skew thin-file and new-to-credit, so bureau data alone both under-approves good borrowers and over-approves bad ones. Bank cash-flow signals from Plaid materially improve both approval rate and loss rate. Affirm has publicly cited Plaid-fed cash-flow data as core to its underwriting, and Klarna runs a similar open-banking pull in the EU.
Why do operators run Sift and Riskified and Signifyd together?
Because the fraud problem splits into three distinct surfaces: account takeover and promo abuse, payment fraud, and merchant-leg chargebacks. Sift scores the first at low per-event cost. Riskified and Signifyd provide chargeback guarantees on the merchant leg for a percentage of approved order value. One vendor cannot cover all three models well.
What does bureau furnishing actually require in 2027?
A live pipeline that reports every approved loan, every payment, and every delinquency to Equifax, Experian, and TransUnion in the standardized BNPL trade-line format the bureaus finalized in 2025-2026. It must run continuously, not quarterly. Operators that skipped furnishing lost merchant deals and drew CFPB attention. It is the hardest piece to retrofit, so build it before volume scales.
Do BNPL operators need NICE Actimize or is ComplyAdvantage enough?
They solve different problems. ComplyAdvantage handles sanctions, PEP, and adverse-media screening at onboarding and ongoing. NICE Actimize handles transaction monitoring, suspicious-activity detection, and SAR filing across the live loan book. Most serious operators run both, plus an in-house compliance-engineering team that wires Regulation Z disclosures and furnishing into the same event stream.
How much does the full recommended stack cost at mid-market scale?
A $500M-$10B GMV operator should budget roughly $2M-$10M per month across software and cloud combined. That covers all three bureaus, Plaid, Socure, Persona, SentiLink, Sift plus a chargeback-guarantee vendor, Stripe plus Adyen plus Cybersource, Marqeta, Snowflake plus Databricks, Salesforce FSC, Iterable, NICE Actimize, and Workday. Cloud runs 30-45% of the total.
What is the single biggest stack mistake BNPL operators make?
Underwriting on bureau data alone. It produces the worst of both worlds: approval rates 10-20 points lower than peers and charge-off rates 2-4x higher, because thin-file applicants are exactly where bureau-only models fail. Adding Plaid cash-flow signals and SentiLink synthetic-identity detection is the highest-ROI fix available to any BNPL operator.
FAQ
What is the recommended BNPL tech stack in 2027?
An in-house loan-origination and ML underwriting engine as the core, wrapped by Plaid plus Socure plus Persona for identity and open banking, all three bureaus plus FICO plus LexisNexis plus SentiLink for credit and synthetic-fraud signals, Sift plus Riskified plus Signifyd for transaction fraud, Stripe plus Adyen plus Cybersource for merchant checkout, NICE Actimize plus ComplyAdvantage for AML, and Snowflake plus Databricks plus Looker for data and BI.
Why is the origination engine built in-house instead of bought?
Because real-time underwriting at 300-800ms is the product. Affirm, Klarna, Afterpay, and PayPal all run proprietary decisioning engines trained on their own loan-performance data. No vendor sells an equivalent, and white-label BNPL-in-a-box platforms have not been adopted by any direct-to-consumer operator at scale. The model is the moat, so it stays in-house.
How fast does a BNPL approval decision need to be?
Between 300 and 800 milliseconds at merchant checkout. Inside that window the system must fan out to Plaid, Socure, the credit bureaus, FICO, LexisNexis, and the in-house ML model, then return an approval or decline before the merchant times out. This latency constraint is what forces the architecture toward a real-time event stream like Kafka rather than batch processing.
Does CFPB Regulation Z apply to pay-in-4 BNPL products?
Yes, under the 2024 interpretive rule most pay-in-4 products are treated as credit cards for Regulation Z purposes, which triggers disclosure, dispute, and billing-error requirements. Combined with state lending licenses, BSA/AML obligations, and mandatory credit-bureau furnishing, compliance reporting is now a first-class system rather than a quarterly spreadsheet exercise.
What changed for EU BNPL operators in 2026?
The Consumer Credit Directive II came into force, extending consumer-credit rules to BNPL and short-term installment products across the EU. That means affordability checks, standardized pre-contractual disclosures, and creditworthiness assessments for products that previously sat outside the directive. Klarna and other EU operators had to rebuild onboarding and disclosure flows to comply.
Can a BNPL operator run on Stripe alone for merchant integration?
No. Stripe is the fastest path to the long tail of merchants, but enterprise merchants like Walmart, Amazon, and Peloton require direct API integrations, and many mid-market merchants run Adyen or Cybersource. Serious operators maintain Stripe plus Adyen plus Cybersource gateway integrations plus native SDKs for Shopify, BigCommerce, WooCommerce, and Magento, with a 30-80 engineer integration team.
Why did Apple Pay Later shut down if the stack is well understood?
Because the servicing layer is operationally heavy. Apple Pay Later ran on an in-house Goldman Sachs-backed underwriting stack, and Apple still chose to exit rather than maintain the loan book, collections, and regulatory reporting. It is the clearest evidence that BNPL is a lending business with a payments front end, not a payments business with installments bolted on.
What role does Snowflake play versus Databricks in a BNPL stack?
Snowflake is the loan-ledger and analytics warehouse, holding every origination, payment, and delinquency event for reporting and merchant dashboards. Databricks handles the ML feature store and model training, often running in parallel. Both are typically present at mid-market scale, with Snowflake spend running $3M-$30M+ annually depending on loan volume.
How important is the BNPL card and wallet layer?
It has moved from optional to a core growth lever. Affirm Card and Klarna's wallet extend BNPL beyond integrated merchants into any store, and Affirm Card volume crossed double-digit billions in annualized GMV in 2026. Both are built on issuing-processor primitives like Marqeta or Galileo, with loan decisioning and rewards logic owned in-house at roughly $0.20-$1.00 per card per month.
What is the hardest piece of the stack to retrofit later?
Credit-bureau furnishing. Reporting every approved loan, payment, and delinquency to Equifax, Experian, and TransUnion in the standardized BNPL trade-line format requires a live pipeline wired into the origination and servicing systems from day one. Operators that deferred it faced merchant losses and CFPB enforcement, and rebuilding it after volume scales is far more expensive than building it early.
Sources
- https://www.consumerfinance.gov/rules-policy/regulations/1026/
- https://www.affirm.com/
- https://www.klarna.com/international/
- https://plaid.com/
- https://www.socure.com/
- https://www.equifax.com/business/
- https://www.experian.com/business/
- https://www.transunion.com/business
- https://www.niceactimize.com/
- https://www.complyadvantage.com/
Related on PULSE
This page will be disappearing soon. Save it to your device for $1 — or read it free while it is here.
@Kory-White- · if Venmo asks, the last 4 of my number are 2012
This page is gone.
This one is off the shelf now. $1 keeps it on your phone for good — the whole page, pictures and diagrams included.
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Movie Theaters in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for HVAC Equipment Distributors in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Independent Driving Schools in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Mobile Threat Defense (MTD) Vendors in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for MSP and IT Services Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Pilates Studios in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Embeddings API Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for AI Document Intelligence Companies in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Threat Intelligence Vendors in 2027
 pulse-tech-stacksTop 10 Best Tech Stack Tools for Bars and Pubs in 2027